Can You Claim Back Employer NI? Yes, in These Cases
You cannot claim back employer NI just because you paid it. But you can often get money back if you overpaid by mistake, missed Employment Allowance, used the wrong category letter or paid statutory pay that you can recover. HMRC normally lets you go back four tax years. This page lists each case, shows what it is worth and gives the steps.
In this guide15 sections
The situations where you can get money back
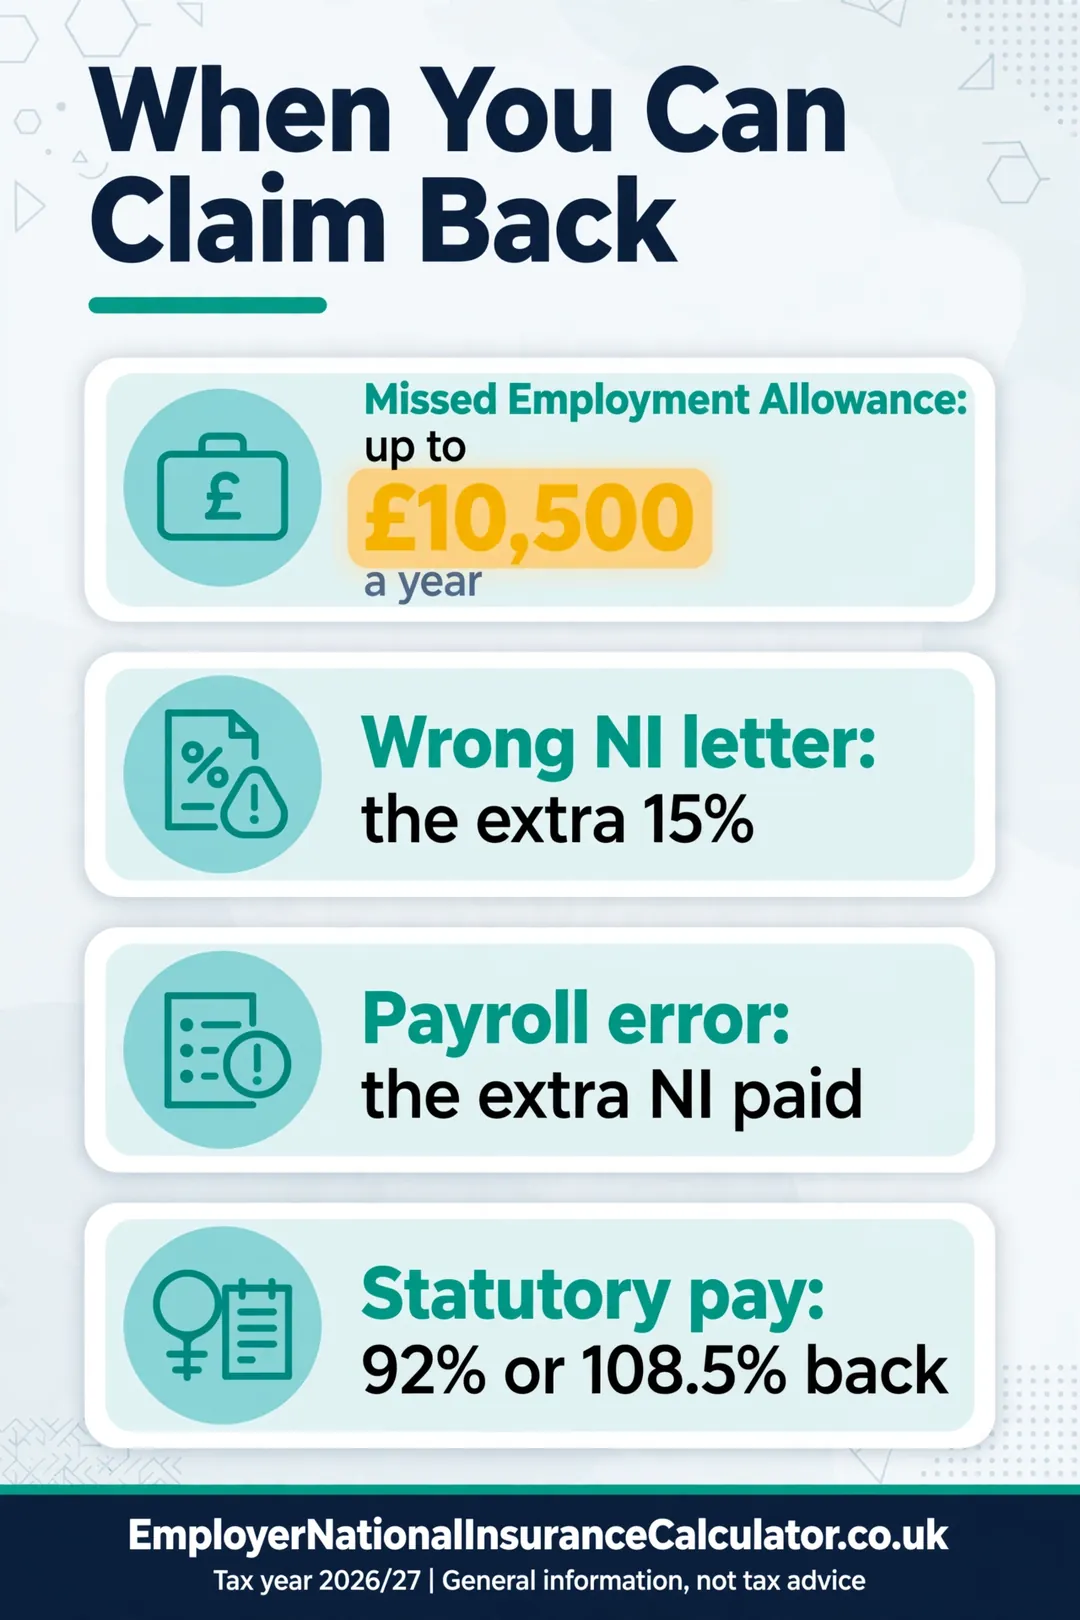
| Situation | What you can recover | How |
|---|---|---|
| You did not claim Employment Allowance | Up to £10,500 a year for 2025/26 onward, £5,000 for earlier years | Send an amended Employer Payment Summary |
| Wrong NI category letter | The extra NI paid at 15% | Correct payroll and tell HMRC |
| Payroll error, such as pay entered twice | The extra NI on the overpaid pay | Correct the next run, or contact HMRC for earlier years |
| Statutory pay paid to staff | The recoverable share of the pay (92%, or 108.5% for small employers) | Deduct it from your PAYE payment |
| Director’s NI worked out monthly by mistake | The extra NI paid | Recalculate on the annual basis and correct payroll |
| A relief such as Freeport or veterans not applied | The extra NI at 15% | Correct the letter and ask for a refund or offset |
Worked example: missed Employment Allowance
A café with four staff on £28,000 pays £13,800 of employer NI in 2025/26 and never claims the allowance. It is eligible. It sends an amended Employer Payment Summary and claims £10,500. HMRC credits £10,500 to its account. The café can leave it against later PAYE bills or ask for a refund.
If the café also missed 2024/25 and 2023/24, it could claim those too, at up to £5,000 for each year, if it was eligible and its bill was big enough.
Worked example: wrong category letter
A company treats a 20-year-old as category A for a full year. Their pay is £28,000. The company paid (£28,000 − £5,000) × 15% = £3,450, when it should have paid nothing under category M. To fix it, the company changes the letter in payroll, corrects earlier submissions and asks HMRC to refund or offset £3,450. See the category letters guide.
Worked example: a payroll error
A bookkeeper enters a £4,000 bonus twice in the same month. Employer NI of £600 is paid on the extra £4,000. The employer corrects the next payroll run. The extra NI is taken off the next bill.
Which case is worth the most?
| Case | Typical value |
|---|---|
| Missed Employment Allowance, 2025/26 and 2026/27 | Up to £10,500 each year |
| Missed Employment Allowance, earlier years | Up to £5,000 each year |
| Wrong category letter for one employee on £28,000 | £3,450 a year |
| Wrong category letter for one employee on £40,000 | £5,250 a year |
| Pay entered twice | 15p for each £1 of overpaid pay |
What you cannot claim back
- Correctly paid employer NI on normal pay. It is a cost of doing business.
- Employer NI because an employee left or you made a loss.
- Employment Allowance you were not eligible for.
- Anything beyond the four-year limit, in most cases.
Steps to take
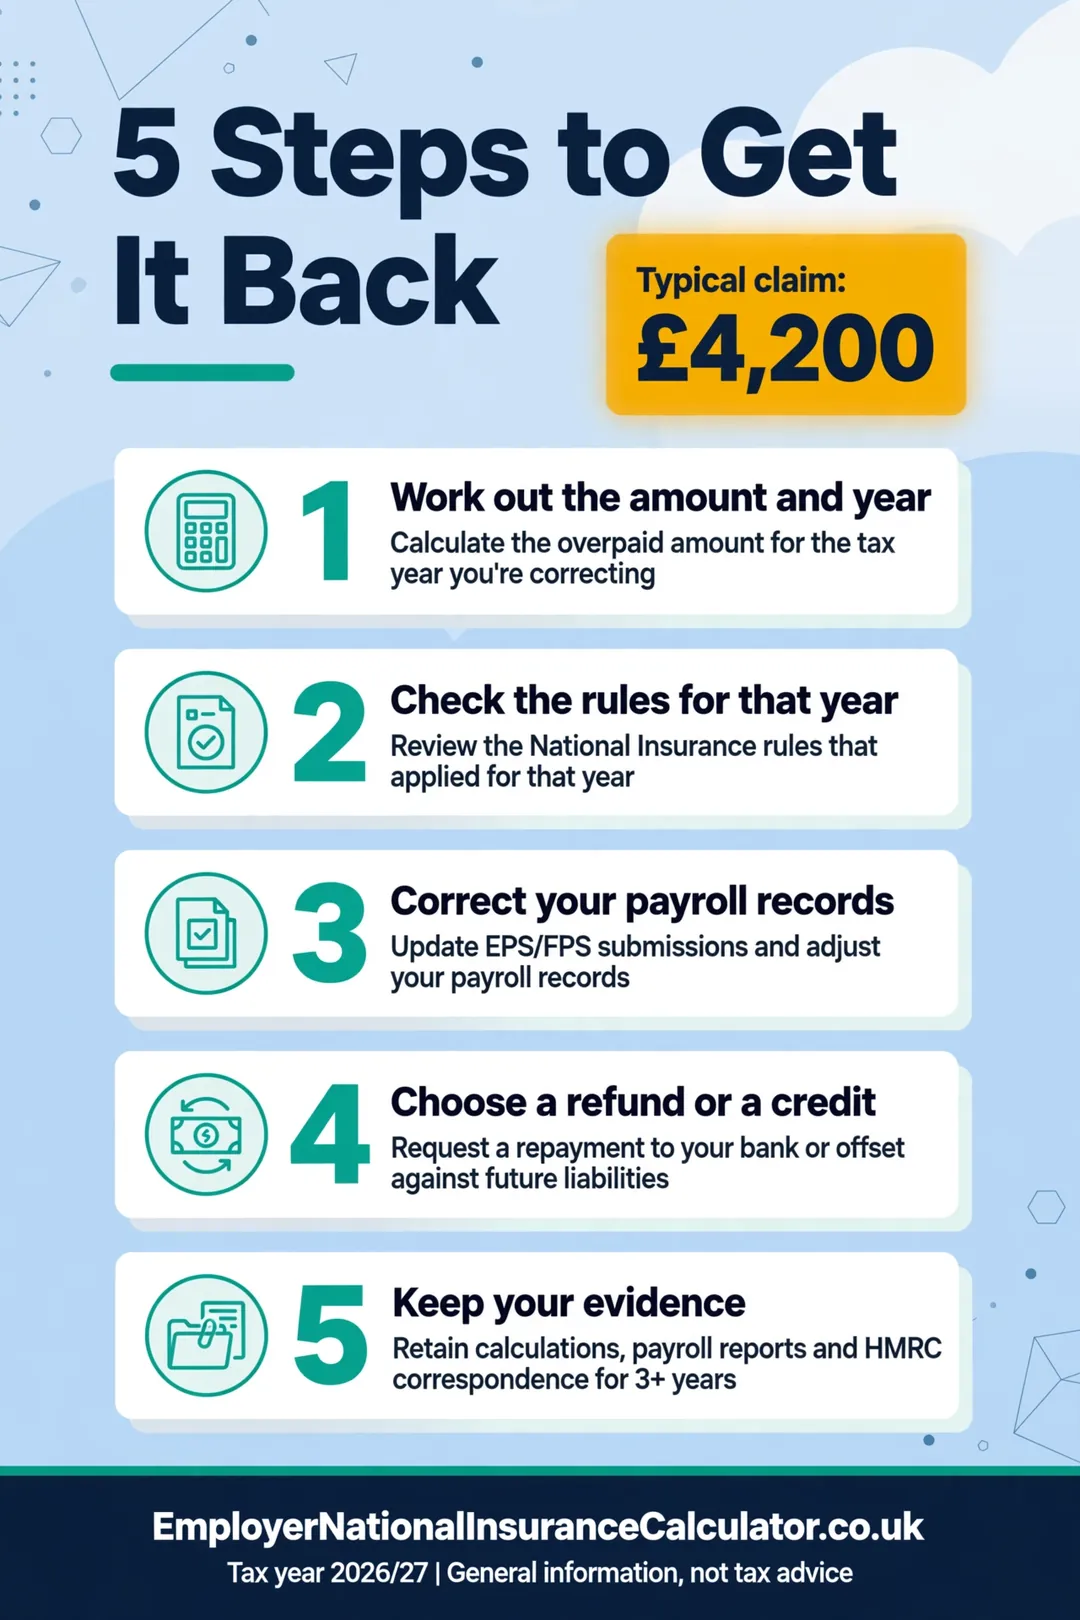
- Work out the amount and the year it relates to.
- Check the rules for that year. Rates and thresholds change. See the rates history.
- Correct your payroll records. For the current year, fix it in your software. For earlier years, send an amended submission or contact HMRC.
- Decide whether to take a refund or keep the credit against future bills.
- Keep the evidence, such as payslips, letters and eligibility checks.
Tax deduction and refunds
If you get a refund of employer NI that you earlier deducted as an expense, tell your accountant. The earlier deduction may need adjusting.
Preventing future overpayments
- Review category letters every April.
- Check Employment Allowance is switched on in the first payroll run of each tax year.
- Reconcile your payroll NI total against the amount HMRC shows on your account every quarter.
- Keep a log of corrections and why you made them.
When to involve an adviser
If the amount is large, or if the problem goes back several years, ask an accountant or payroll specialist. They can prepare the submission and deal with HMRC. See the allowance guide, the letters guide and the claim steps for the basics.
Common mistakes when claiming back
- Claiming for a year in which you did not qualify.
- Using the wrong amount for the year. Use £5,000 for 2024/25 and earlier, and £10,500 from 2025/26.
- Forgetting that the allowance cannot be more than the NI you paid.
- Missing the four-year time limit.
- Claiming Employment Allowance for a company where the only paid employee is the director.
What if you underpaid?
The same rules work in reverse. If you find you underpaid, correct it as soon as you can. HMRC can charge interest and penalties on late payments, and the sooner you correct it the lower the cost. See how to pay employer NI.
Frequently asked questions
Can I claim back employer NI I have already paid?
Only if it was overpaid by mistake, or if a relief such as Employment Allowance applied and you did not claim it.
How far back can I claim?
Usually four tax years from the end of the tax year concerned.
How do I get a refund from HMRC?
Correct your payroll records, then ask HMRC for a refund or let the credit offset your next bills.
Can I claim back employer NI on a salary sacrifice scheme?
Not as a refund. Salary sacrifice lowers the NI you pay going forward. See salary sacrifice savings.
Is employer NI refundable if my company makes a loss?
No. It is based on payroll, not profit.
Who do I contact?
HMRC’s employer helpline can help with corrections. Have your PAYE reference ready.
Will HMRC pay interest on a refund?
HMRC can pay interest on some repayments. The rules depend on the cause and the timing.
What evidence does HMRC want?
Payroll records, proof of who was paid and when, and the reason for the correction.
Can I claim back NI on an employee who was not entitled to be paid?
The rules depend on the facts. Speak to HMRC or an adviser, because the question may involve employment status.
Is a refund taxable income?
It reduces an expense you earlier claimed, so it affects your taxable profit. Ask your accountant.
Related guides
- How to Claim Employment Allowance (Step by Step)
- Employment Allowance 2026/27: £10,500 Off Employer NI
- NI Category Letters for Employers (2026/27)
- Employer NI on Statutory Pay and Redundancy (2026/27)
- Employment Allowance Eligibility: Who Can Claim?
Official sources
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
2 Comments
Comments are closed.