Employer NI on Bonuses (2026/27)
Employer NI on a bonus
The real cost of a bonus, and what the employee keeps.
Loading the calculator…
Estimate only. Independent tool, not affiliated with HMRC. Rates checked 20 October 2026. Real payroll rounds each pay period.
A cash bonus attracts employer National Insurance at 15% in 2026/27. For a standard employee already earning above £5,000, the whole bonus is charged. A £3,000 bonus costs the employer £450 in NI on top. Use the calculator above to see the total for any bonus, then read on for the rules, the director case and ways to cut the cost.
In this guide15 sections
How employer NI works on a bonus
A bonus counts as earnings in the pay period when you pay it. Employer NI is worked out on pay for that period above the threshold. If the employee’s salary is already above the threshold, every pound of the bonus is charged at 15%.
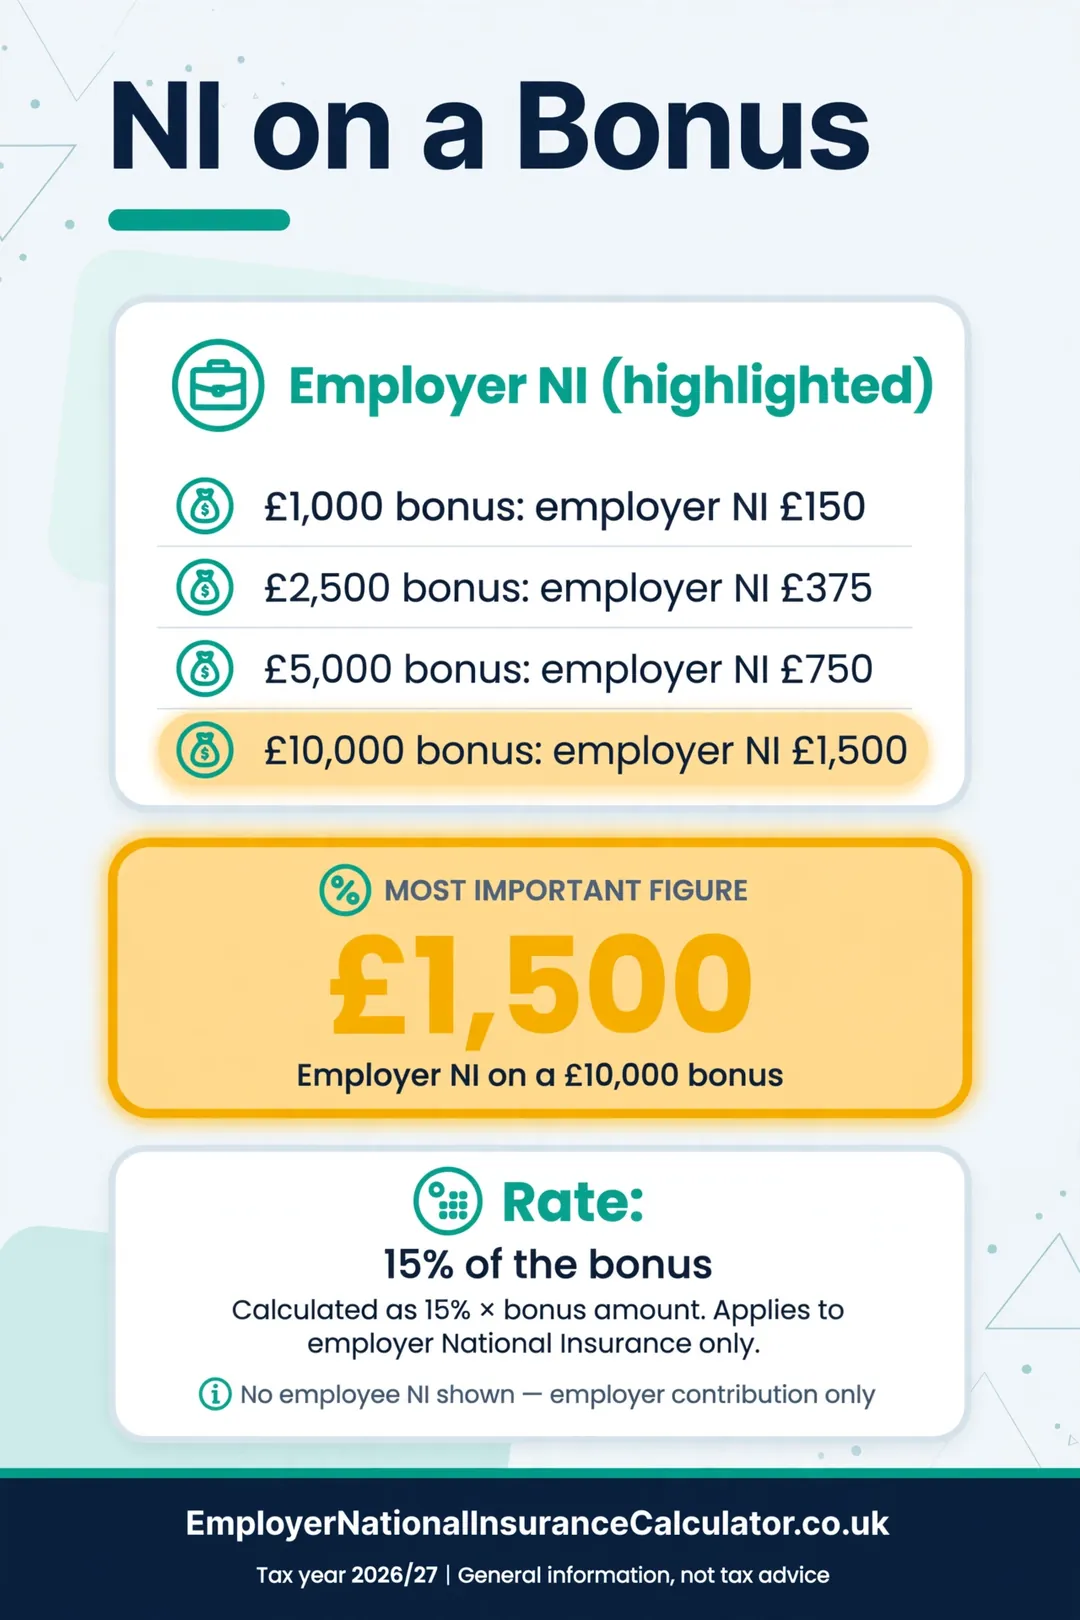
Employer NI on a bonus = bonus × 15%
This applies to a standard employee whose normal pay already uses up the threshold. The employee also pays NI: 8% on the bonus if their pay is within the £12,570 to £50,270 band, and 2% above £50,270.
Examples
| Bonus | Employer NI | Employee NI at 8% | Total cost to the employer |
|---|---|---|---|
| £1,000 | £150 | £80 | £1,150 |
| £2,500 | £375 | £200 | £2,875 |
| £5,000 | £750 | £400 | £5,750 |
| £10,000 | £1,500 | £800 | £11,500 |
Only the employer NI is an extra cost to you. The employee NI comes out of the bonus.
Monthly payroll and bonuses
On monthly payroll, the bonus is added to the pay for the month it is paid. A £2,000 bonus in December, on top of £2,500 normal pay, means December pay of £4,500. Employer NI is £4,500 − £417 = £4,083 × 15% = £612.45, against £312.45 in a normal month. The £300 gap is 15% of the bonus.
What if the employee earns little?
If an employee’s pay is low, part of the bonus may fall below the threshold. This matters mostly for part-time and seasonal staff.
| Monthly pay | Bonus | Employer NI on pay plus bonus | Extra for the bonus |
|---|---|---|---|
| £300 | £500 | £57.45 | £57.45 |
| £400 | £500 | £72.45 | £72.45 |
| £800 | £500 | £132.45 | £75 |
| £2,500 | £500 | £387.45 | £75 |
The first two rows show a bonus charged on less than the full 15%, because part of it uses up the £417 threshold for the month.
Directors and bonuses
A director’s NI is based on the whole year. A bonus adds to annual pay, so employer NI on a bonus is 15% provided the director’s pay is already above £5,000. For a director on a low salary, part of the bonus fills the gap below the threshold first.
| Director salary | Bonus | Employer NI on the bonus |
|---|---|---|
| £4,000 | £5,000 | £600 |
| £12,570 | £5,000 | £750 |
| £30,000 | £5,000 | £750 |
Ways to reduce the NI on a bonus
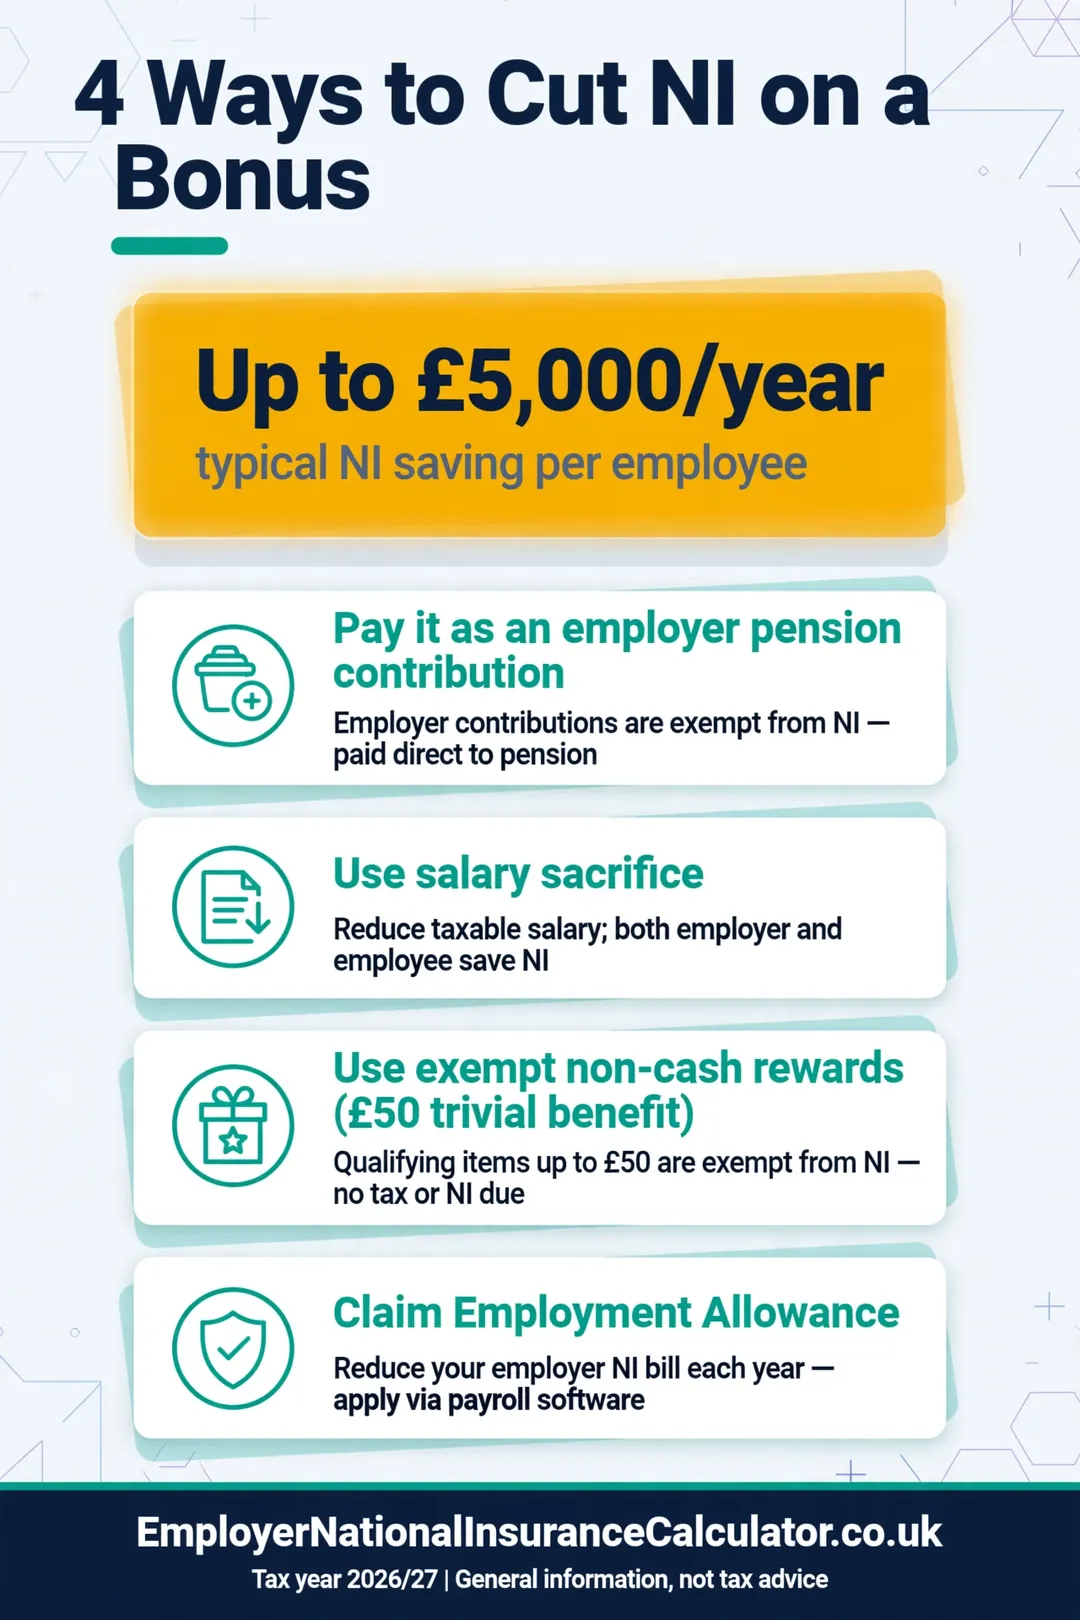
- Pay it as a pension contribution. An employer contribution carries no NI. A £5,000 bonus as a pension payment costs £5,000, not £5,750. The employee can choose it if it suits them.
- Use salary sacrifice. The employee gives up a bonus in return for a pension payment. The 2029 cap will apply later. See the 2029 cap.
- Use non-cash rewards that are exempt. A trivial benefit of £50 or less, and an annual party up to £150 a head, are exempt when conditions are met.
- Claim Employment Allowance. If your NI bill is under £10,500, a bonus may cost no extra NI.
Case study: sales commission
A firm pays five sales reps £12,000 of commission each in March. All five are already above the Secondary Threshold.
| Item | Amount |
|---|---|
| Commission paid | £60,000 |
| Employer NI at 15% | £9,000 |
| Total cost | £69,000 |
If the firm paid the same commission in April instead, the NI would fall into the next tax year. The rate does not change, but the next year’s Employment Allowance may have room left. Moving a payment for tax reasons alone is unwise, and it must reflect when the commission is earned and due.
Bonuses and Employment Allowance
A bonus adds to your NI bill and uses up the allowance faster. A firm with a £9,000 NI bill and a £10,500 allowance has £1,500 left. A £10,000 bonus costs £1,500 in NI, which is covered. A £20,000 bonus costs £3,000 in NI, and £1,500 of it is paid out of pocket.
Mistakes to avoid
- Assuming a bonus is taxed in the same way as a pension contribution.
- Paying a bonus into a different tax year to “save” NI without checking the effect.
- Forgetting that holiday and overtime pay count too.
- Treating vouchers as exempt without checking that they are not convertible to cash.
- Counting a bonus as a one-off with no NI.
- Forgetting the effect on director NI.
Bonus planning for a team
A firm wants to pay a year-end bonus of £1,500 to each of 25 staff, who all earn above the NI thresholds.
| Route | Cost to the firm | What the staff receive |
|---|---|---|
| Cash bonus | £43,125 | £27,000 after 20% tax and 8% NI |
| Pension contribution of the same amount | £37,500 | £37,500 in the pension |
| Mix: £750 cash, £750 pension | £40,312.50 | £13,500 in hand plus £18,750 in pension |
Before April 2029, a salary sacrifice route can also give staff more because it saves them NI. After April 2029, only the first £2,000 each is free of NI under salary sacrifice.
Timing a bonus
NI is due when the bonus is paid. Paying it in March rather than April moves the NI to the earlier tax year. The rates are the same, so the main effect is on which year’s Employment Allowance covers it and on cash flow.
Who to tell
Staff should see the gross amount, the tax, the NI and the net figure. A short note avoids surprise on payday. Keep a record of how you decided the amount, particularly for directors and owners.
Frequently asked questions
Do employers pay NI on bonuses?
Yes. Cash bonuses are earnings, so employer NI at 15% applies.
How much is employer NI on a £5,000 bonus?
£750, for a standard employee already above the £5,000 threshold.
Is NI charged on a bonus paid into a pension?
Not if the employer pays it as a pension contribution. Employer contributions carry no NI.
Do employees pay NI on bonuses?
Yes. They pay 8% on earnings between £12,570 and £50,270 and 2% above.
Is a Christmas gift taxable?
A small gift of £50 or less can qualify as a trivial benefit. Cash and vouchers convertible into cash are earnings.
Does a bonus affect Employment Allowance?
It increases your employer NI bill, so it uses up the allowance faster.
Can I pay a bonus in shares or gifts to avoid NI?
Some non-cash items are treated differently, but cash-like gifts are still pay. Check the rules before you rely on an exemption.
Does a bonus affect Statutory Maternity Pay?
It can, if it is paid in the period used to work out average weekly earnings.
Is NI due when a bonus is paid or when it is earned?
It is due when the bonus is paid or when the employee is entitled to it, whichever comes first. See how NI is calculated.
Related guides
- Monthly Employer NI Calculator 2026/27
- Salary Sacrifice Employer NI Savings (2026/27)
- Director National Insurance Calculator 2026/27
- How Employer National Insurance Is Calculated
- Employer NI Exemptions and Reliefs 2026/27
Official sources
- National Insurance rates and categories
- HMRC guidance on earnings and NI
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
3 Comments
Comments are closed.