Director National Insurance Calculator 2026/27
Director NI calculator
Employer and director NI on any salary, with a State Pension year check.
Loading the calculator…
Estimate only. Independent tool, not affiliated with HMRC. Rates checked 20 October 2026. Real payroll rounds each pay period.
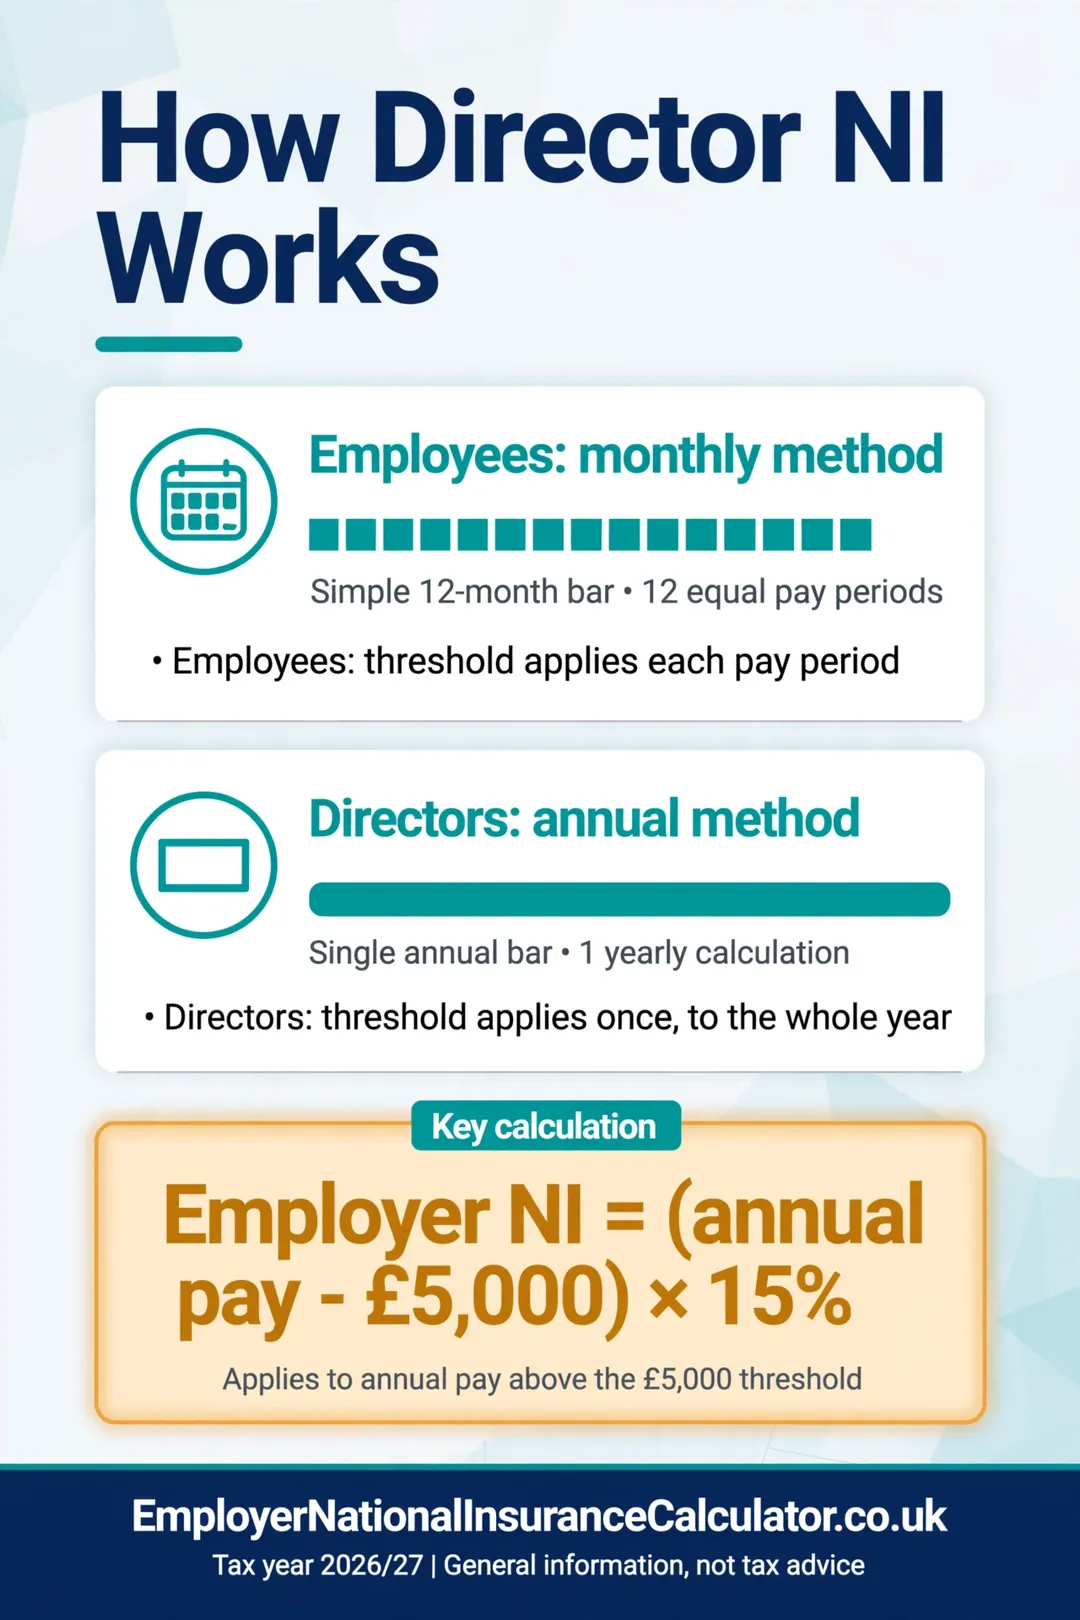
Company directors use an annual earnings period for National Insurance, not a monthly one. In 2026/27, the company pays 15% on director pay above £5,000 for the year, and the director pays 8% above £12,570. Use the calculator to see the cost of any director salary, then read on for how the annual method works and what changes it.
In this guide14 sections
How the director method works
Most employees have NI worked out each pay period, so the threshold applies again each month. Directors do not.
Their NI is based on total pay for the whole tax year, and the yearly thresholds apply. If a director is paid £1,000 a month, no NI is due in the first five months, because the year’s pay has not passed £5,000. The bill starts once the running total passes the threshold.
Employer NI = (annual pay − £5,000) × 15%
Employee NI = (annual pay − £12,570) × 8%, with 2% above £50,270
Common director salaries compared
| Annual salary | Employer NI | Employee NI | Qualifying year for State Pension? |
|---|---|---|---|
| £5,000 | £0 | £0 | No, below £6,708 |
| £6,708 | £256.20 | £0 | Yes |
| £9,100 | £615 | £0 | Yes |
| £12,570 | £1,135.50 | £0 | Yes |
| £20,000 | £2,250 | £594.40 | Yes |
| £50,270 | £6,790.50 | £3,016 | Yes |
A salary of £6,708 or above counts as a qualifying year. A salary below it does not. For help with choosing, read our director salary guide.
What about the Employment Allowance?
A company with only one paid employee who is also a director cannot claim Employment Allowance. That means a one-person company normally pays the full employer NI on the director’s pay. If the company has another employee paid above £5,000, it can claim up to £10,500, which would cover the director’s employer NI as well. See eligibility.
| Company | Employer NI before | After allowance |
|---|---|---|
| One director on £12,570 | £1,135.50 | £1,135.50 (no claim) |
| One director on £12,570 plus an employee on £8,000 | £1,585.50 | £0 |
Example: two directors and one employee
A company pays Director A £12,570, Director B £12,570 and an employee £20,000.
| Person | Pay | Employer NI |
|---|---|---|
| Director A | £12,570 | £1,135.50 |
| Director B | £12,570 | £1,135.50 |
| Employee | £20,000 | £2,250 |
| Total | £4,521 | |
| Employment Allowance | −£4,521 | |
| Employer NI to pay | £0 |
The company pays nothing in employer NI, because more than one person is paid above £5,000.
Month-by-month example
A director takes £1,500 a month, £18,000 for the year. NI is based on the running total.
| Month | Pay to date | Employer NI that month |
|---|---|---|
| April | £1,500 | £0 |
| May | £3,000 | £0 |
| June | £4,500 | £0 |
| July | £6,000 | £150 |
| August to March (8 months) | £7,500 to £18,000 | £225 each |
The year total is £150 + 8 × £225 = £1,950, which matches (£18,000 − £5,000) × 15% = £1,950. The first three months cost nothing because the director has not yet passed £5,000. Payroll software may also offer an alternative method that spreads the threshold across pay periods. The year-end result is the same.
Directors who join or leave mid-year
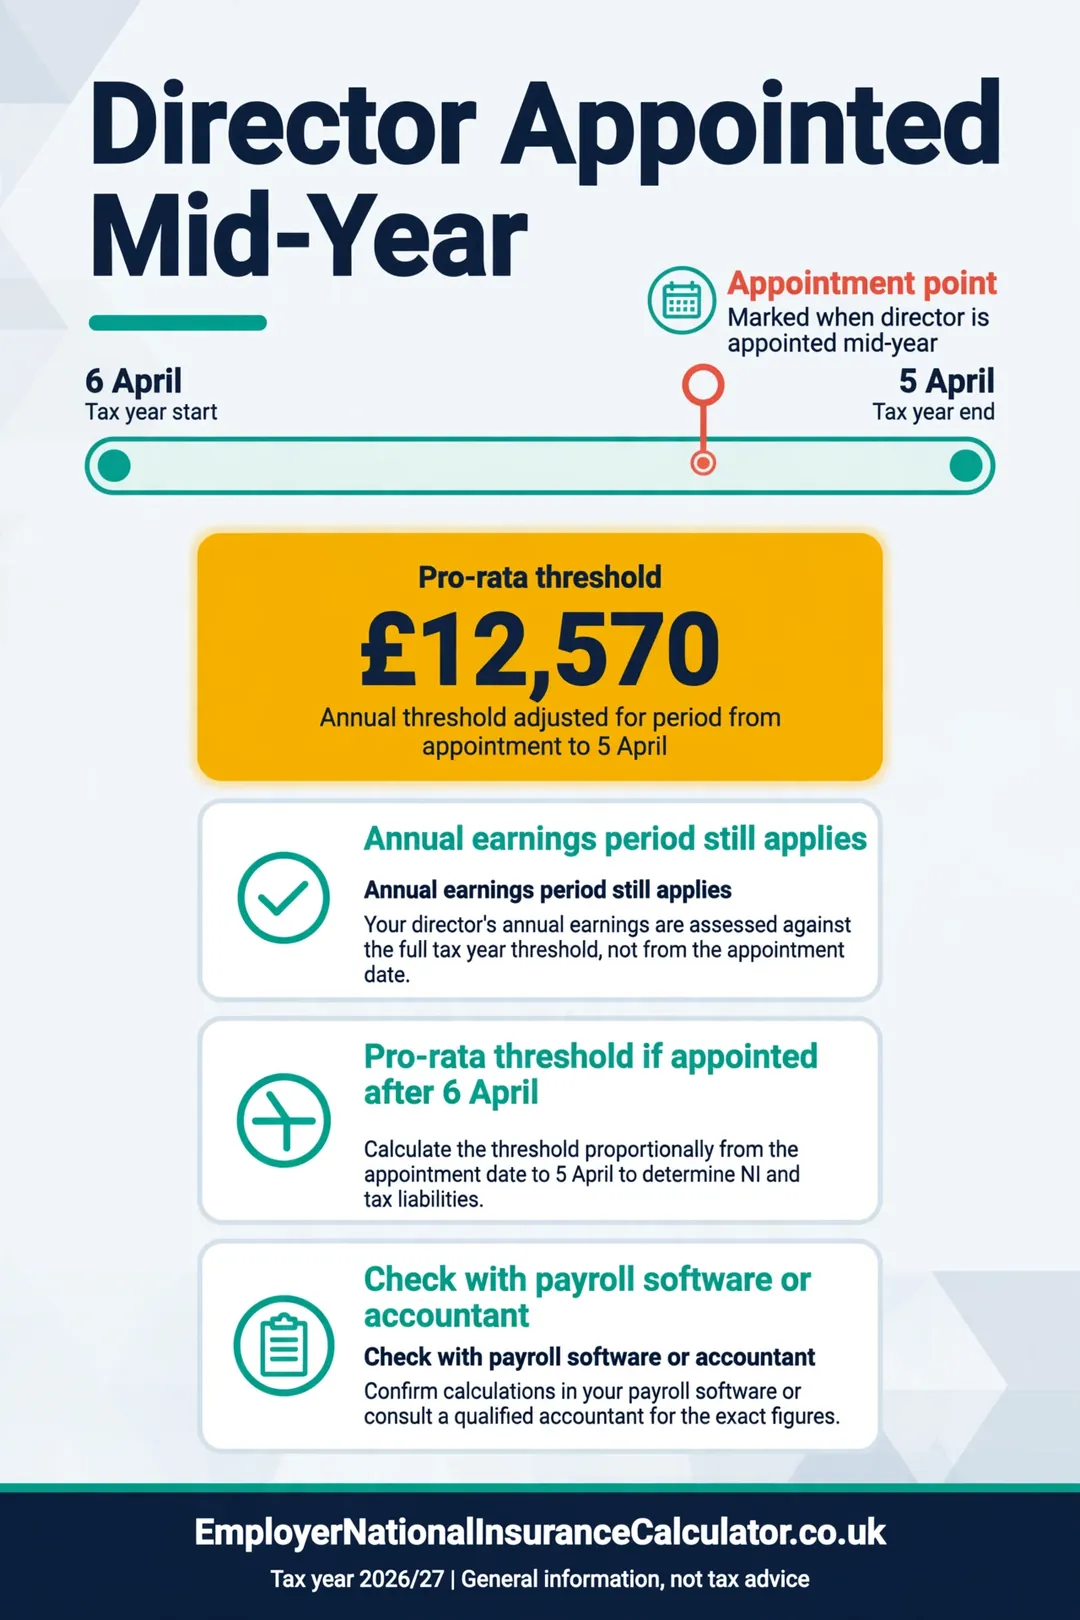
If a director is appointed part-way through the tax year, there are special rules. An annual earnings period normally applies, but the annual thresholds are reduced in proportion to the weeks left in the year. Ask your payroll software or accountant to check this.
Bonuses and dividends
A bonus paid to a director is part of annual pay and increases the NI on that year. Dividends are not pay, so they carry no NI. They are taxed under dividend rules instead. A director taking a mix of low salary and dividends should look at the whole picture, including corporation tax.
| £10,000 extra paid to a director on £12,570 | Employer NI | Employee NI |
|---|---|---|
| As a bonus | £1,500 | £800 |
| As a dividend | £0 | £0 (dividend tax applies instead) |
See employer NI on bonuses and director pension contributions.
Using the result in your planning
For the cost of a full personal-allowance salary, see employer NI on a £12,570 salary.
Add the figure to the company’s cash forecast. A late-year bonus or dividend plan does not change employer NI unless it is paid as salary. If your accountant suggests a different salary, rerun the calculator and compare. For the choice between the three common salaries, read the director salary guide.
Three real director set-ups
| Set-up | Pay | Employer NI | Employee NI | Total NI |
|---|---|---|---|---|
| Sole director, small salary | £6,708 | £256.20 | £0 | £256.20 |
| Sole director, full allowance | £12,570 | £1,135.50 | £0 | £1,135.50 |
| Director with bonus | £12,570 plus £10,000 | £2,635.50 | £800 | £3,435.50 |
The third set-up shows why bonuses cost more than salary at the same level. The director pays 8% on the extra pay above £12,570, and the company pays 15% on all of it above £5,000.
What to do at the year end
- Add up every payment made to the director, including bonuses and fees.
- Run the calculator for the annual total.
- Compare it with the NI payroll has recorded.
- Fix any gap before the final Full Payment Submission.
Common director NI mistakes
- Treating a director as a monthly employee.
- Forgetting that dividends are not pay, but loans written off can be.
- Setting the salary after the year has started without recalculating.
- Assuming the company can claim Employment Allowance as a one-person company.
See the director salary guide to choose a salary.
Frequently asked questions
How is NI worked out for a director?
On annual earnings. The company pays 15% on pay above £5,000 for the year, and the director pays 8% on pay above £12,570.
Can a director be paid monthly?
Yes. NI is still based on the annual total, so it may only start once the running total passes the thresholds.
What is the best director salary for NI?
It depends on whether the company can claim Employment Allowance. See our salary guide.
Do dividends attract NI?
No. Dividends are not subject to employer or employee NI, but are taxed under dividend tax rules.
Does my company pay employer NI on my salary if I am the only employee?
Yes, on pay above £5,000. As the sole paid employee, the company also cannot claim Employment Allowance.
Do directors need NI category letters?
Yes. Most directors are category A, and payroll uses the annual method for them.
Why is a director’s NI zero for the first few months?
Because NI is based on the running total for the year. It only starts once the total passes the threshold.
Does the alternative method change the yearly total?
No. By the end of the tax year, the total employer NI is the same under both methods.
What counts as director pay for NI?
Salary, bonuses and fees. Dividends do not count.
Can I pay myself less than £5,000?
Yes, but the year may not count towards your State Pension unless pay reaches £6,708. See the salary guide.
Related guides
- Director Salary 2026/27: £5,000, £6,708 or £12,570?
- Employment Allowance Eligibility: Who Can Claim?
- Employer NI on Bonuses (2026/27)
- How Employer National Insurance Is Calculated
- Company Pension Contributions for Directors and NI
Official sources
- National Insurance rates and categories
- HMRC: Rates and thresholds for employers 2026 to 2027
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.