Do Employers Pay NI on Pension Contributions?
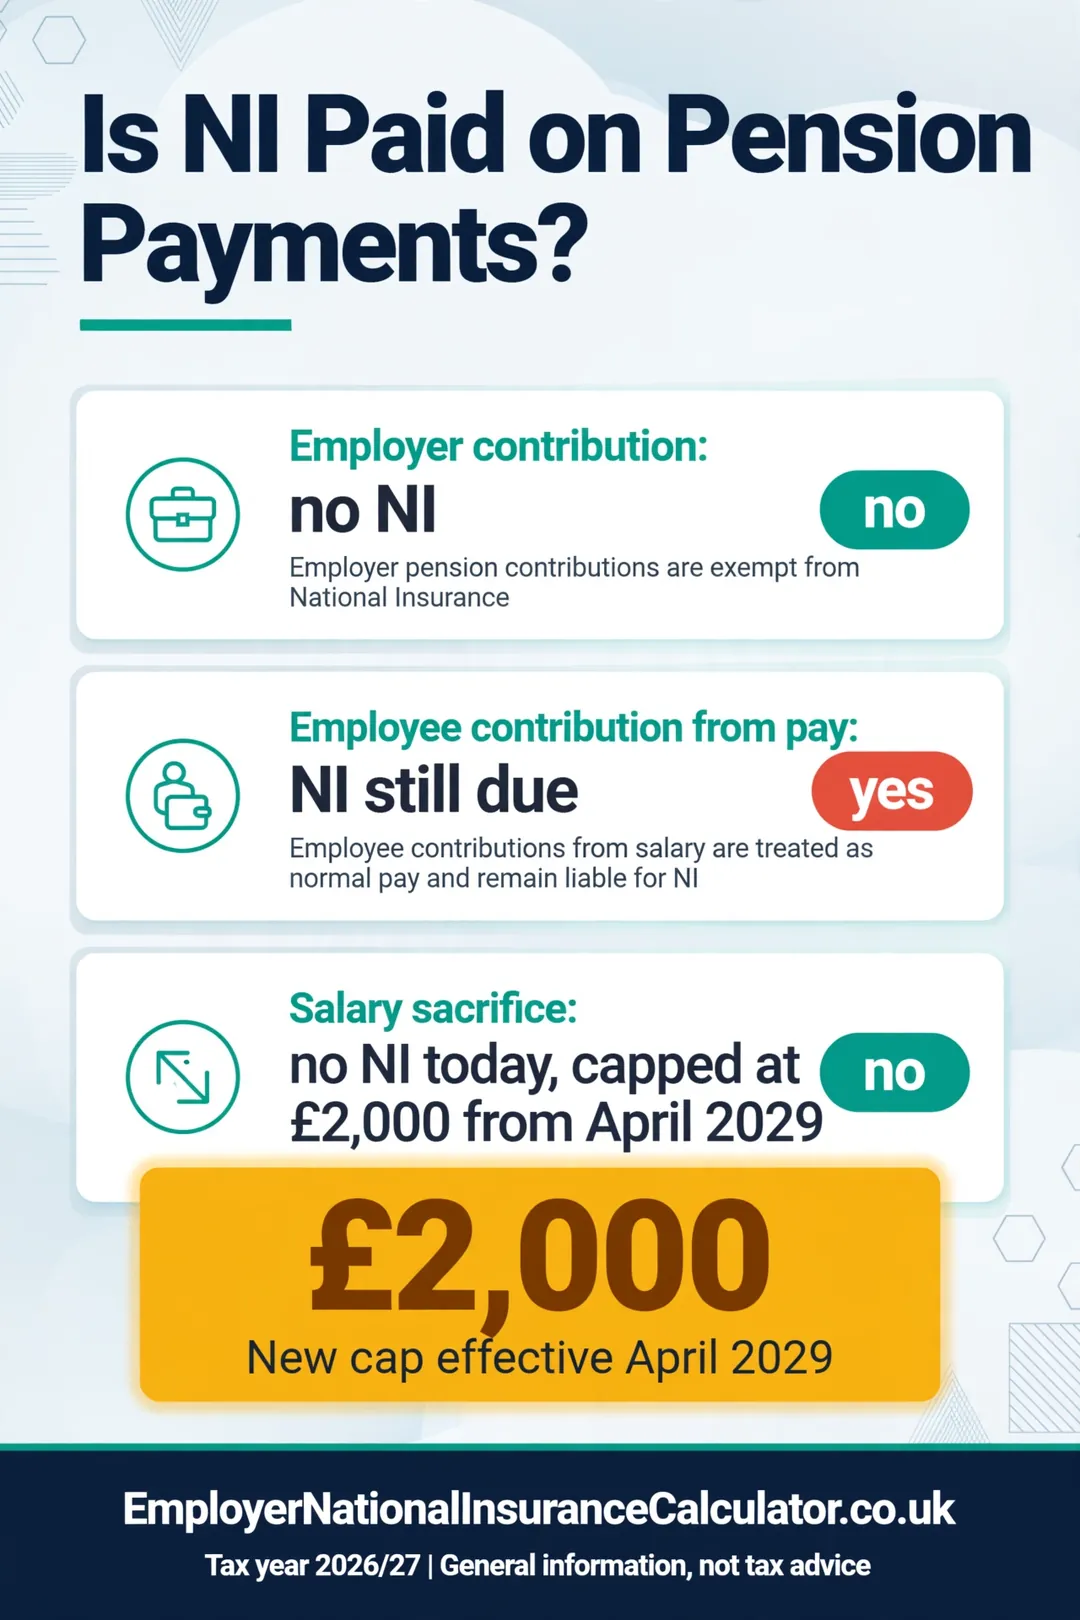
No. Employers do not pay National Insurance on their own contributions to an employee’s registered pension. Employees do pay NI on pension contributions taken from their pay, unless they use salary sacrifice. From April 2029, a £2,000 cap will limit the NI-free amount under salary sacrifice. This page sets out each case with numbers.
In this guide14 sections
Employer contributions
When you pay into a staff pension, that payment is not earnings. So it carries no employer NI and no employee NI. Under auto-enrolment, a minimum employer contribution of 3% of qualifying earnings is required, and it adds nothing to your NI bill.
| Example: employee on £30,000 | Cost |
|---|---|
| Employer NI on salary | £3,750 |
| Employer pension at 3% of qualifying earnings (£6,240 to £30,000) | £712.80 |
| NI on the pension | £0 |
| Total cost of employment | £34,462.80 |
The qualifying earnings band is £6,240 to £50,270 at the time of writing. Check the current figures on GOV.UK.
Employee contributions
The picture changes when the employee pays into their own pension from their wages. There are two main ways:
- Net pay arrangement. The employer takes the employee’s contribution from pay before income tax. NI is still worked out on the full pay, so NI is the same.
- Relief at source. The employer deducts the contribution after tax, and the pension provider claims basic-rate relief. NI is also on full pay.
Employee contributions do not reduce employee or employer NI, under either method.
Salary sacrifice is different
With salary sacrifice, the employee gives up salary and the employer pays that amount into the pension. Now the contribution is an employer one, so no NI is due today. The employer saves 15%, and the employee saves 8% (or 2% above £50,270).
| £3,000 into a pension | Employer NI | Employee NI at 8% |
|---|---|---|
| Employee pays from net pay | No change | No change |
| Salary sacrifice | £450 less | £240 less |
This is covered in full in salary sacrifice savings.
From April 2029: the £2,000 cap
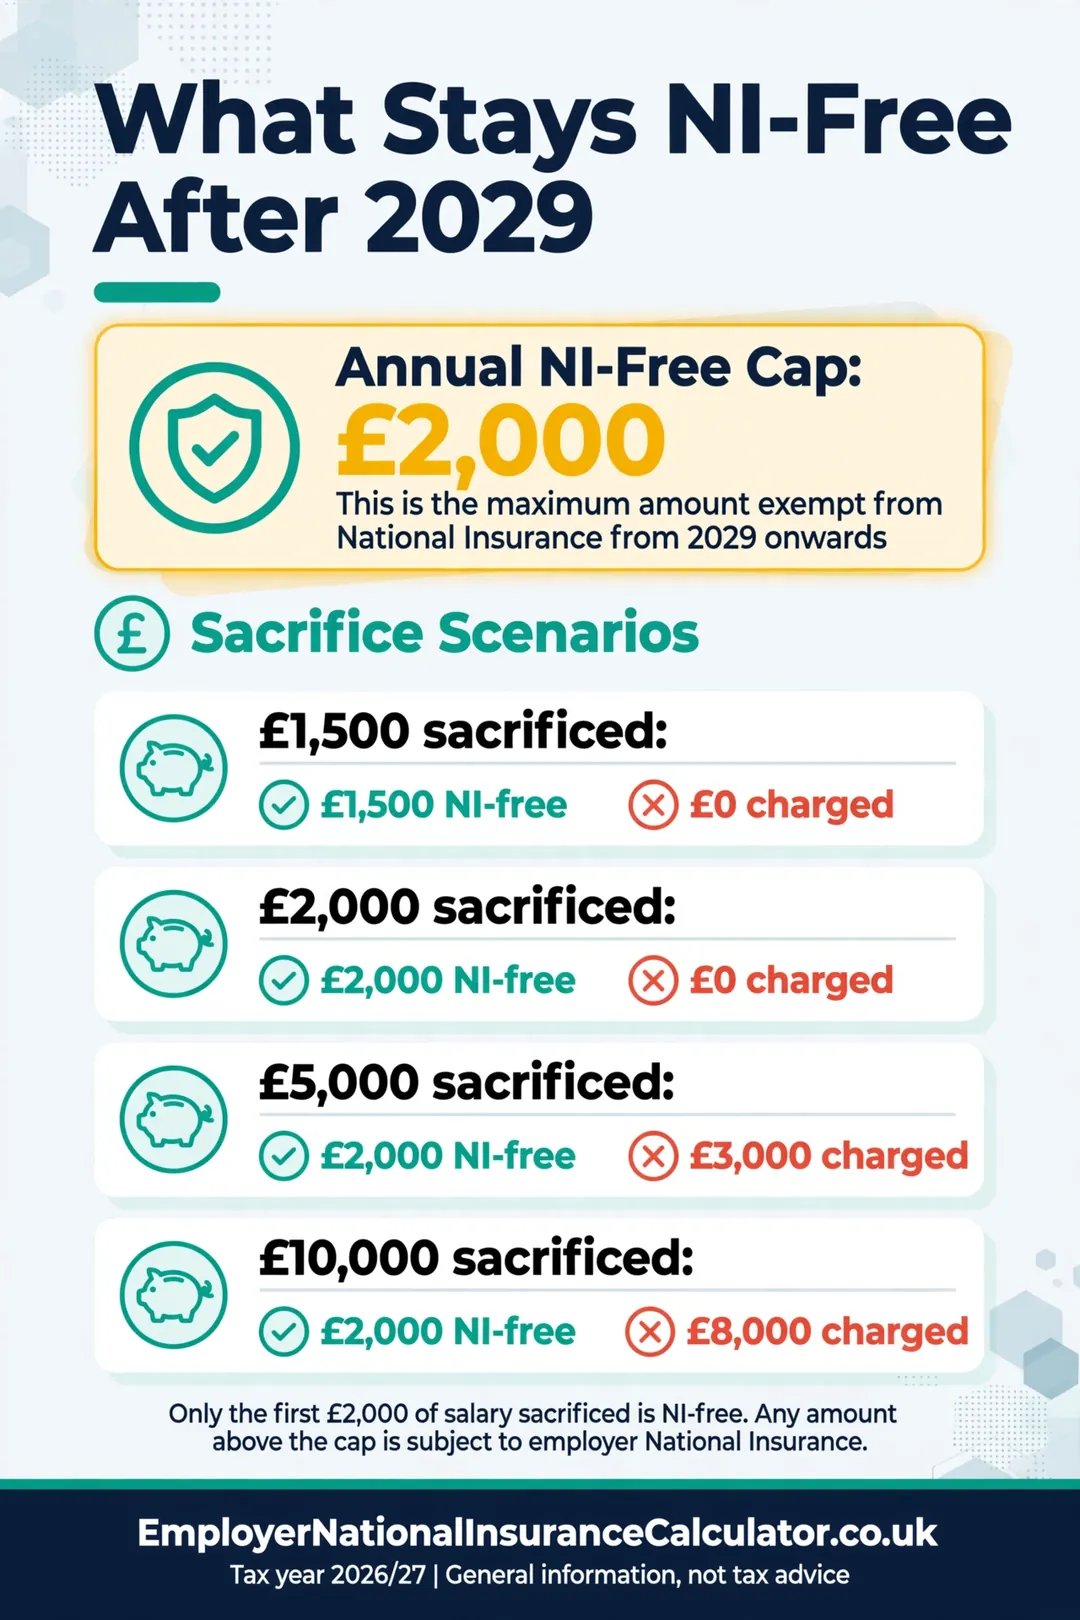
From 6 April 2029, the NI-free amount under pension salary sacrifice is limited to £2,000 a year per employee. Anything above £2,000 is treated as pay for NI purposes. Normal employer pension contributions, not made through sacrifice, are not affected.
| Salary sacrificed | NI-free from April 2029 | Charged NI | Extra employer NI |
|---|---|---|---|
| £1,500 | £1,500 | £0 | £0 |
| £2,000 | £2,000 | £0 | £0 |
| £5,000 | £2,000 | £3,000 | £450 |
| £10,000 | £2,000 | £8,000 | £1,200 |
What employers should do
- Keep paying the required employer contributions. They remain NI-free.
- If you use salary sacrifice, list your staff by the amount they sacrifice.
- Work out the cost after the cap for those above £2,000.
- Decide whether to change schemes before 2029.
Auto-enrolment in practice
Most employees aged 22 to State Pension age earning over £10,000 must be enrolled in a workplace pension. The employer must pay at least 3% of qualifying earnings, and the total minimum is 8%. This cost is on top of salary and does not attract NI.
| Three staff on £24,000 each | Employer NI | Employer pension at 3% of qualifying earnings |
|---|---|---|
| Per person | £2,850 | £532.80 |
| For three | £8,550 | £1,598.40 |
The pension cost does not change the NI bill. Both are costs of employing each person.
Bonus as pension contribution
A £5,000 bonus paid in cash costs £5,750 once employer NI is added. The same £5,000 paid into the employee’s pension costs £5,000. The employee gets a smaller amount in hand but more total value after tax and NI. This is a common choice for higher-paid staff. See employer NI on bonuses.
| £5,000 as | Cost to employer | Reaches the employee (basic-rate taxpayer) |
|---|---|---|
| Cash bonus | £5,750 | £3,600 after tax and NI |
| Pension contribution | £5,000 | £5,000 in the pension |
Mistakes to avoid
- Treating employee pension contributions as exempt from NI. They are not, unless through salary sacrifice.
- Putting a sacrifice in place without a written agreement.
- Ignoring the 2029 cap when you set up a long-term scheme. See the cap guide.
- Assuming a pension contribution counts towards the State Pension record. It does not.
Auto-enrolment costs for a whole team
A 20-person firm pays the employer pension contribution on top of salary. It does not change the NI figure, but both belong in the budget.
| Item | Per employee on £28,000 | For 20 employees |
|---|---|---|
| Employer NI | £3,450 | £69,000 |
| Employer pension at 3% of qualifying earnings | £652.80 | £13,056 |
| Total on-cost | £4,102.80 | £82,056 |
| After Employment Allowance (NI only) | £71,556 |
Employment Allowance only reduces the NI part. The pension contribution stays in full.
Which route is best?
| Goal | Route | NI effect |
|---|---|---|
| Meet the legal minimum | Employer contribution at 3% | No NI |
| Cut NI for staff who want to save more | Salary sacrifice | Employer and employee NI saved, up to £2,000 from April 2029 |
| Reward a director | Direct company contribution | No NI |
| Reward a team member tax-efficiently | Bonus paid into pension | No NI |
Getting the records right
Keep the contribution schedule from your pension provider. Check each month that the amount paid matches the payroll. A mismatch between payroll and provider is one of the most common audit questions.
Frequently asked questions
Do employers pay NI on pension contributions?
No. Employer contributions to a registered pension scheme have no employer or employee NI.
Do employees pay NI on pension contributions from their pay?
Yes. Under a standard scheme, NI is worked out on full pay. Only salary sacrifice cuts NI.
Does auto-enrolment add to my NI bill?
No. The 3% minimum employer contribution is outside NI.
What is the 2029 cap?
From April 2029, only £2,000 a year of salary sacrifice pension contributions are NI-free.
Does the cap affect ordinary employer contributions?
No. It applies only to contributions made through salary sacrifice.
Are director pension contributions the same?
Yes. See director pension contributions.
Do I need to pay a pension for staff who earn under £10,000?
They can ask to join, and you must pay in if they do and earn above the lower threshold. Check the current rules on GOV.UK.
Is the employer pension contribution deductible?
Yes, normally, as a staff cost for corporation tax or income tax.
Do I pay NI on a pension contribution that replaces a bonus?
Not if it is paid by the employer into a registered scheme.
Related guides
- Salary Sacrifice Employer NI Savings (2026/27)
- £2,000 Salary Sacrifice Pension Cap From April 2029
- Company Pension Contributions for Directors and NI
- How Employer National Insurance Is Calculated
- Employer NI on Bonuses (2026/27)
Official sources
- National Insurance rates and categories
- HMRC guidance on pension contributions and NI
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
One Comment
Comments are closed.