Freeport and Investment Zone Employer NI Relief
Employer NI calculator
Add each pay level in your team. Get the bill, the cost and the working.
Loading the calculator…
Estimate only. Independent tool, not affiliated with HMRC. Rates checked 20 October 2026. Real payroll rounds each pay period.
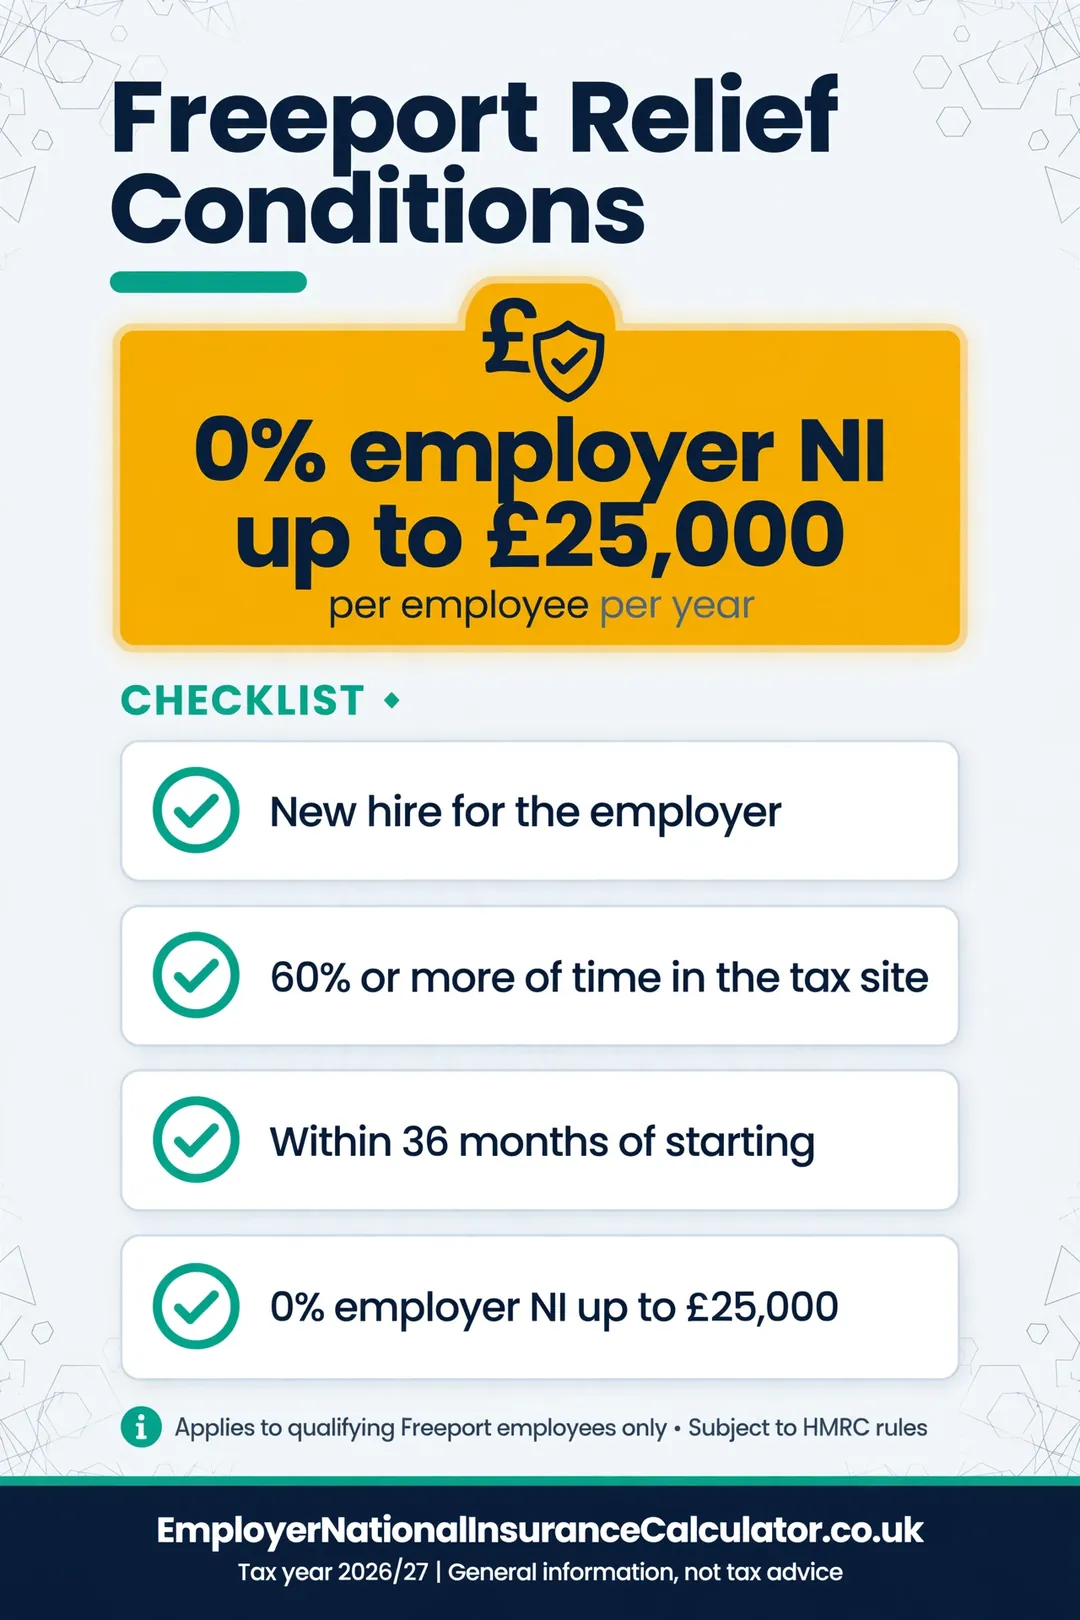
Employers in a UK Freeport or Investment Zone can pay 0% employer National Insurance on pay up to £25,000 a year for eligible employees. The relief lasts for 36 months from the start of each person’s employment. Above £25,000, the 15% rate applies. Use the calculator, then read who qualifies, how to apply the 60% test and what records to keep.
In this guide17 sections
Who qualifies
An employee counts if they meet all of these:
- They are a new hire for the employer, hired to work in the designated tax site.
- They spend at least 60% of their working time in the tax site.
- The site has the relevant status when they start.
- They are within their first 36 months of qualifying employment.
The employer must work out the 60% test over the pay period. Staff who mainly work elsewhere do not qualify, even if they sometimes visit the site.
How much you save
| Salary | Standard employer NI | Freeport relief | Saving |
|---|---|---|---|
| £20,000 | £2,250 | £0 | £2,250 |
| £25,000 | £3,000 | £0 | £3,000 |
| £32,000 | £4,050 | £1,050 | £3,000 |
| £50,000 | £6,750 | £3,750 | £3,000 |
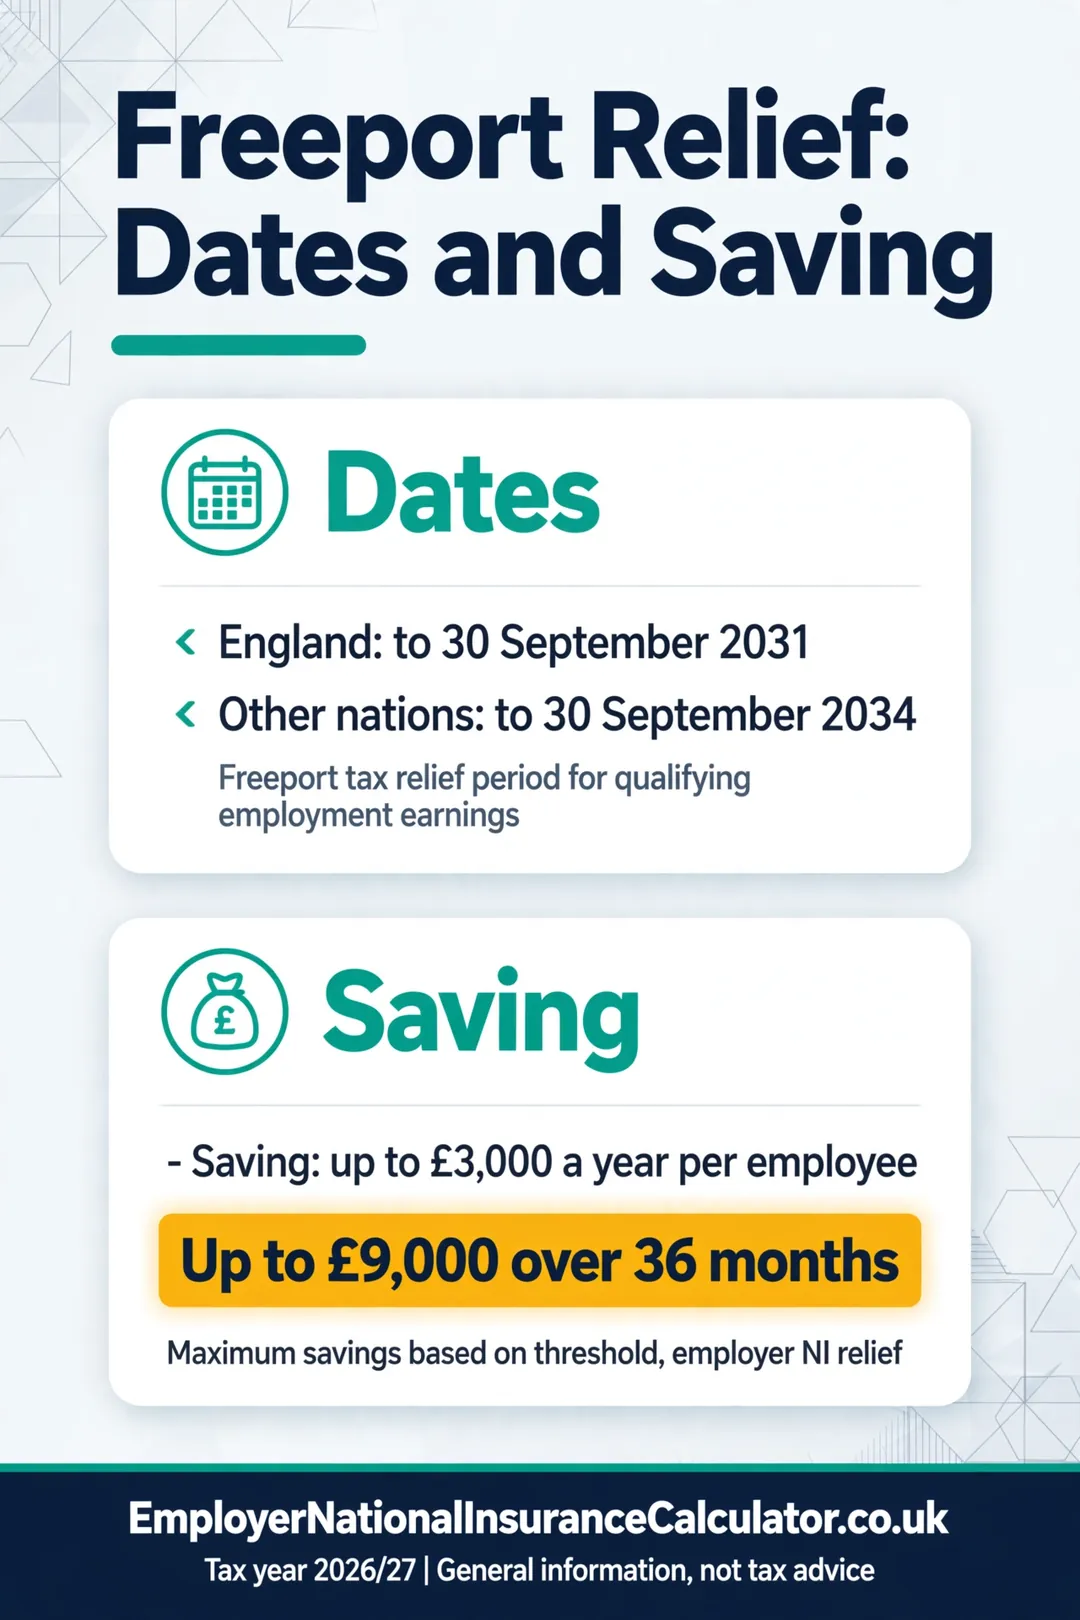
The maximum saving per employee is £3,000 a year: the £20,000 of pay between the normal £5,000 threshold and the £25,000 limit, times 15%. Over the 36 months, that is £9,000 per person.
How it compares
| Relief | Zero rate up to | Maximum yearly saving |
|---|---|---|
| Freeport and Investment Zone | £25,000 | £3,000 |
| Under 21, apprentice or veteran | £50,270 | £6,790.50 |
If a Freeport employee is also under 21 or an apprentice, you can choose the one with the bigger limit.
Dates and limits
The relief for Freeports is set to run to 30 September 2031 in England, and to 30 September 2034 in the rest of the UK. The employee’s 36 months starts on the date they begin work. Dates and sites change, so check GOV.UK before you rely on them.
Category letters
The Freeport and Investment Zone employer categories use their own letters, and the employee’s normal NI status affects which one you use. Check the category letters guide and the latest list on GOV.UK before you set up payroll.
Records you should keep
- A map or proof that the work location is within the tax site
- A record of the employee’s working time on and off site
- The employee’s start date and a note of the 36-month end
- The contract showing the role
The 60% test
An employee who works three days out of five on site spends 60% of their time there and passes. An employee who works two days out of five spends 40% and fails. Home working counts as time away from the site. Keep timesheets or rota evidence for each pay period.
Case study: ten hires at a Freeport site
A logistics firm hires ten new staff on £30,000 to work at a Freeport tax site.
| Item | Per person | For ten |
|---|---|---|
| Standard employer NI | £3,750 | £37,500 |
| With Freeport relief | £750 | £7,500 |
| Saving per year | £3,000 | £30,000 |
Over 36 months, the firm saves £90,000 if all ten stay and meet the conditions. With Employment Allowance, the bill after relief is £0.
What happens after 36 months
| Months 1 to 36 | From month 37 | |
|---|---|---|
| Employer NI on £30,000 | £750 | £3,750 |
| Change | £3,000 more a year |
Diary the end date for each hire. Moving to the standard category late means underpaying NI.
Mixing reliefs
A Freeport employee who is also under 21 can be placed in whichever category gives the best result, which is usually category M because its limit is £50,270. See the under-21 guide and the exemptions hub.
Mistakes to avoid
- Treating all staff at the site as eligible. Only new hires qualify.
- Not checking the 60% rule.
- Missing the 36-month end and overclaiming.
- Using the wrong letter.
- Assuming the dates and sites never change.
Planning a hire at a Freeport site
The relief rewards pay up to £25,000. Every pound above it is charged at the full 15%. That changes how you might set pay for a new role.
| Offered salary | Employer NI with relief | Extra NI for the last £1,000 of pay |
|---|---|---|
| £24,000 | £0 | £0 |
| £25,000 | £0 | £0 |
| £26,000 | £150 | £150 |
| £30,000 | £750 | £150 |
Pay up to the limit costs no extra NI. Pay above it costs 15p for each extra pound.
A checklist before you hire
- Confirm the work location is inside a designated tax site.
- Check the person is a genuine new hire and not a transfer from another part of your group.
- Write the working pattern into the contract so the 60% test can be shown.
- Set the correct Freeport category letter from day one.
- Diary the 36-month end date.
Freeport relief and Employment Allowance together
The relief lowers your bill first.
Employment Allowance then comes off what is left. A firm with eight Freeport hires on £30,000 has an NI bill of £6,000 after relief, which Employment Allowance covers in full. Without the relief the bill would be £30,000, and £19,500 would be left to pay after the allowance. The two reliefs work in sequence, so the saving from each depends on the size of your total bill.
See the Employment Allowance guide.
Frequently asked questions
What is the Freeport employer NI relief?
0% employer NI on pay up to £25,000 a year for eligible new hires who work in a Freeport or Investment Zone tax site.
How long does it last?
36 months for each employee, from the start of their employment.
Do all employees at the site qualify?
No. They must be new hires who spend at least 60% of their time in the tax site.
What is the maximum saving per year?
£3,000 per employee, which is £9,000 over 36 months.
When do the Freeport reliefs end?
They are set to end on 30 September 2031 for English sites and 30 September 2034 elsewhere. Check GOV.UK for the current dates.
Where do I check whether my site is eligible?
GOV.UK lists the designated Freeports and Investment Zones.
What if an employee moves jobs within the same business?
They may not count as a new hire for the site. Check the rules before applying the relief.
Does the relief apply to part-time staff?
Yes, if they meet the conditions. The £25,000 limit is a yearly pay limit and is not pro-rated for hours.
Can a director qualify?
A director can qualify if they meet the same conditions as other employees.
Related guides
- Employer NI Exemptions and Reliefs 2026/27
- NI Category Letters for Employers (2026/27)
- Employer NI Thresholds 2026/27: Weekly, Monthly, Yearly
- Cost of Employing Someone UK 2026/27: Calculator
- Employer NI for Under 21s (2026/27): 0% to £50,270
Official sources
- National Insurance rates and categories
- HMRC guidance on Freeport and Investment Zone relief
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
One Comment
Comments are closed.