£2,000 Salary Sacrifice Pension Cap From April 2029
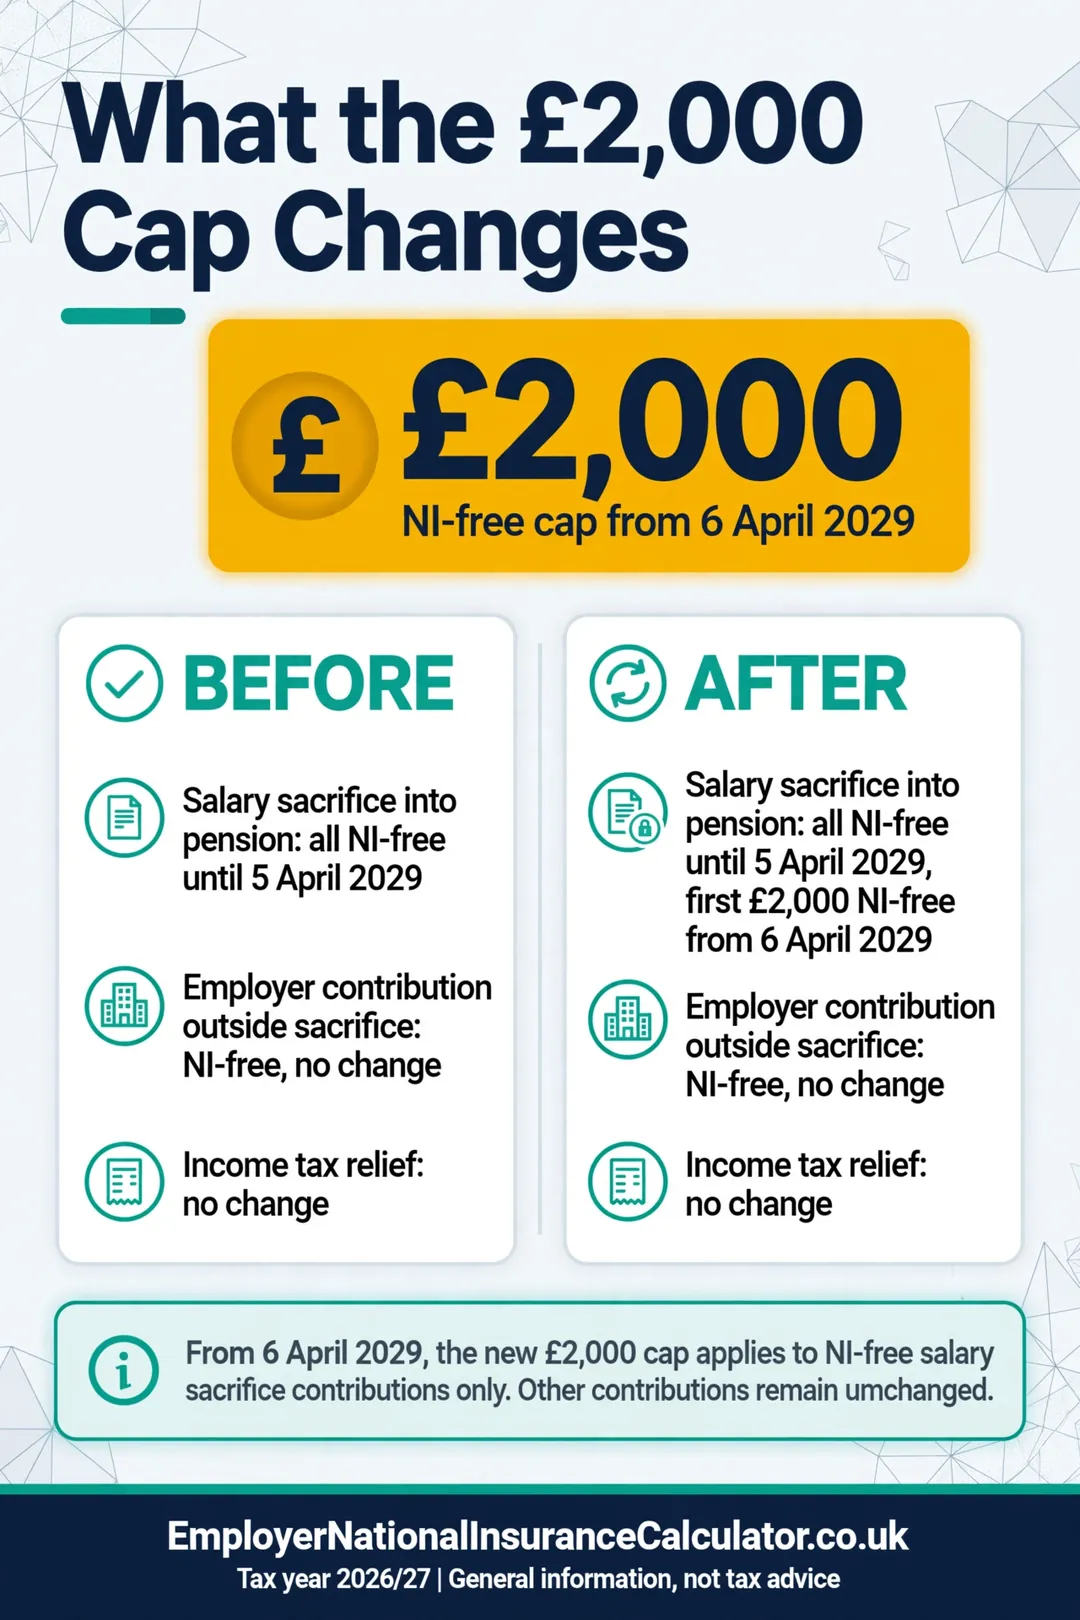
From 6 April 2029, only the first £2,000 of pension contributions made by salary sacrifice each year will be free of National Insurance. Anything above £2,000 will be charged NI as if it were pay. For an employer, that means an extra 15% on the sacrificed amount above the cap.
Nothing changes for 2026/27, but contracts you write now will still be running in 2029, so it pays to plan early.
In this guide16 sections
What changes and what does not
| Until 5 April 2029 | From 6 April 2029 | |
|---|---|---|
| Salary sacrifice into pension | Fully free of employer and employee NI | First £2,000 free, rest charged |
| Employer pension contribution (not sacrifice) | Free of NI | Free of NI |
| Employee contribution from pay | NI charged | NI charged |
| Income tax relief | Unchanged | Unchanged |
The cap affects NI only. Income tax relief on pension contributions is not changed.
Worked examples for an employer
The rate used is 15% employer NI.
| Salary sacrificed | Employer NI saved today | Employer NI saved after the cap | Extra cost to the employer |
|---|---|---|---|
| £1,500 | £225 | £225 | £0 |
| £2,000 | £300 | £300 | £0 |
| £4,000 | £600 | £300 | £300 |
| £6,000 | £900 | £300 | £600 |
| £10,000 | £1,500 | £300 | £1,200 |
For a company with 20 staff each sacrificing £6,000, the extra cost from April 2029 is £12,000 a year (20 × £600).
Worked examples for the employee
An employee sacrificing £6,000 at the 8% rate saves £480 today. After the cap they save only £160, since only £2,000 stays free. They lose £320 a year. Higher earners above £50,270 pay 2%, so their loss is smaller at £80.
What to do before 2029
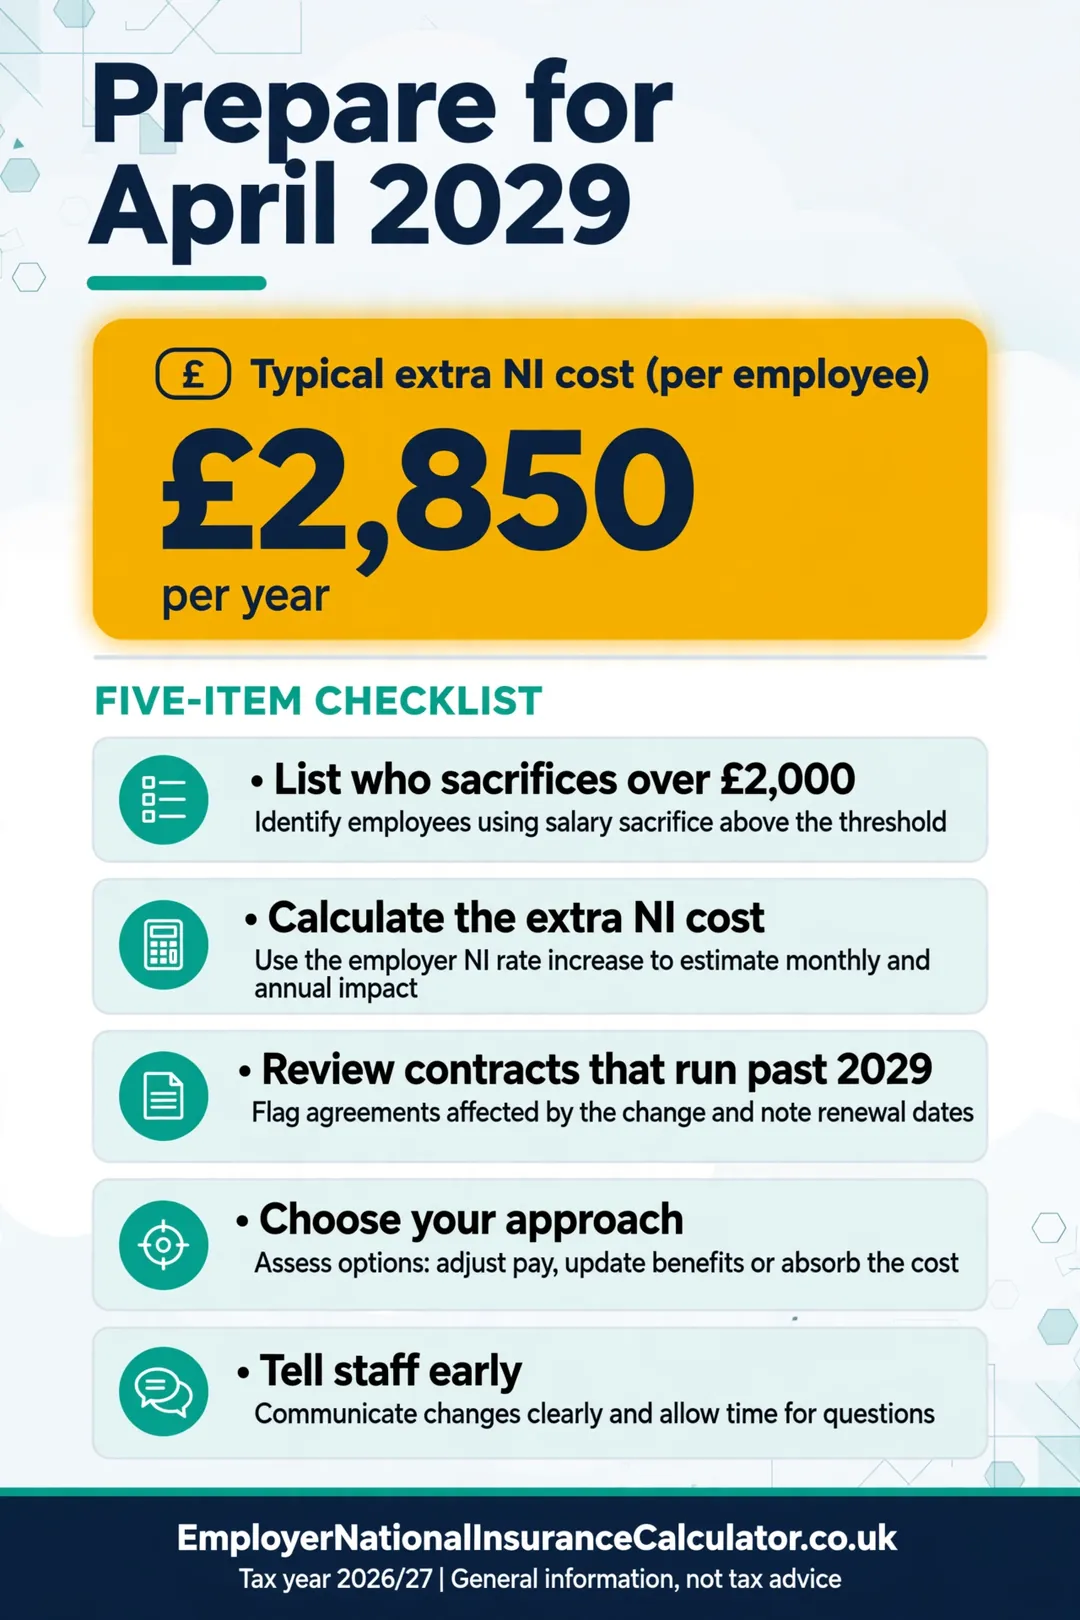
- List who sacrifices what. Count how many staff sacrifice more than £2,000.
- Calculate the extra cost. Use the salary sacrifice calculator and look at the amount above £2,000.
- Review contracts. Agreements that run past April 2029 may need a clause that deals with the change.
- Decide your approach. You can keep the scheme, reduce the sacrifice to £2,000, or move to another structure.
- Tell staff early. They need time to adjust.
Options for employers
- Cap the sacrifice at £2,000. Keeps the full NI saving and has no extra cost.
- Pay the higher contribution as a normal employer contribution. An employer pension contribution outside salary sacrifice stays NI-free. The employee then keeps normal pay, so you must adjust the package.
- Keep the scheme and absorb the cost. Simple, but the extra NI is a real cost.
- Review other benefits. Cycle-to-work and electric-car schemes are not covered by this cap.
| Option | Cost to the employer for an employee sacrificing £6,000 | Effect on staff |
|---|---|---|
| Keep the scheme and absorb the cost | £600 a year | None |
| Cap at £2,000 | £0 | £4,000 less in the pension, unless paid another way |
| Pay £4,000 as a normal employer contribution | £0 extra NI | Smaller pay package |
Who is most affected
Employers with many higher-earning staff who sacrifice large amounts. Law firms, tech companies and professional services businesses often have staff sacrificing £5,000 or more. Small businesses with a few staff are less affected, since the sums are smaller.
Case study: a 50-person firm
A firm has 50 staff. Twenty of them sacrifice an average of £5,000 into the pension.
| Item | Before April 2029 | After April 2029 |
|---|---|---|
| Sacrificed pay in total | £100,000 | £100,000 |
| NI-free amount | £100,000 | £40,000 (20 × £2,000) |
| Employer NI saved at 15% | £15,000 | £6,000 |
| Extra annual cost | n/a | £9,000 |
Staff lose out too. Their NI saving at 8% falls from £8,000 to £3,200 in total, a difference of £4,800.
Practical choices
The firm could cap each person’s sacrifice at £2,000 and pay the rest as a normal employer contribution. It could also share the lost saving with staff for a year or two. Or it could review the scheme and tell staff clearly what is changing. Whatever you choose, tell people at least six months before the change, and keep a note of the decision.
Timeline
| Date | What to do |
|---|---|
| Now | List your sacrifice schemes and staff amounts |
| By April 2028 | Decide your approach, model the cost |
| By October 2028 | Tell staff, update contracts |
| 6 April 2029 | Cap starts, payroll must apply it |
Where to check the latest rules
Details can change in future Budgets. Check GOV.UK each year. See also NI on pension contributions, director pension contributions and the 2026/27 changes.
Scenario planning for a larger employer
Take a firm with 200 pension salary sacrifice members. The effect of the cap depends on how much each member sacrifices.
| Group | Members | Average sacrifice | NI-free from April 2029 | Charged NI | Extra employer NI |
|---|---|---|---|---|---|
| Low savers | 100 | £1,200 | £1,200 | £0 | £0 |
| Mid savers | 70 | £3,000 | £2,000 | £1,000 | £10,500 |
| High savers | 30 | £8,000 | £2,000 | £6,000 | £27,000 |
| Total | 200 | £37,500 |
The 30 high savers account for most of the extra cost. A targeted conversation with them is more useful than a blanket change.
Options for the high savers
| Option | Cost to employer from 2029 | Effect on the member |
|---|---|---|
| Do nothing | £27,000 extra | Smaller NI saving |
| Cap sacrifice at £2,000 | £0 | £6,000 less into the pension unless replaced |
| Replace the excess with an employer contribution | £0 extra NI | Smaller take-home pay package |
| Share the lost saving | Part of £27,000 | Partly protected |
A practical communication plan
- Tell staff early that nothing changes before April 2029.
- Show each member their own figures.
- Offer a time-limited meeting with a pension adviser.
- Review the position every autumn, in case future Budgets change the rules again.
Frequently asked questions
When does the salary sacrifice cap start?
6 April 2029.
How much is the cap?
£2,000 per employee per tax year. Contributions above that are charged NI.
Does the cap apply to employer contributions made outside salary sacrifice?
No. Normal employer contributions remain free of NI.
Will income tax relief change?
No. The cap changes only the NI treatment of sacrificed pay.
Does it apply now?
No. Until April 2029, salary sacrifice pension contributions stay fully NI-free.
What should I do now?
Work out the extra cost from 2029, look at your contracts and decide on your approach well before the change.
Should I stop salary sacrifice before 2029?
Not necessarily. The first £2,000 stays NI-free, and income tax relief is unchanged. Model the cost first.
Does the cap affect employees over the higher-rate threshold?
Yes, but they pay 2% employee NI, so their NI saving is smaller to start with. Income tax relief is the bigger gain.
Does the cap apply to both employer and employee NI?
Yes. The NI-free limit covers both shares.
Are other salary sacrifice schemes affected?
The £2,000 cap applies to pension salary sacrifice. Check the current rules for other schemes on GOV.UK.
Related guides
- Salary Sacrifice Employer NI Savings (2026/27)
- Do Employers Pay NI on Pension Contributions?
- Company Pension Contributions for Directors and NI
- National Insurance Changes for 2026/27
- Cost of Employing Someone UK 2026/27: Calculator
Official sources
- National Insurance rates and categories
- HMRC guidance on salary sacrifice and pensions
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
One Comment
Comments are closed.