Class 1A National Insurance 2026/27: Rate and Deadlines
Class 1A NI calculator
Employer NI on company cars, medical cover and other benefits.
Loading the calculator…
Estimate only. Independent tool, not affiliated with HMRC. Rates checked 20 October 2026. Real payroll rounds each pay period.
Class 1A National Insurance is a yearly employer charge on most benefits in kind, such as company cars and private medical insurance. The rate for 2026/27 is 15% of the value of the benefits. You report the benefits on form P11D and pay the NI by 22 July after the tax year ends. Use the calculator above, then read what counts, the deadlines and how payrolling fits in.
In this guide17 sections
What Class 1A covers
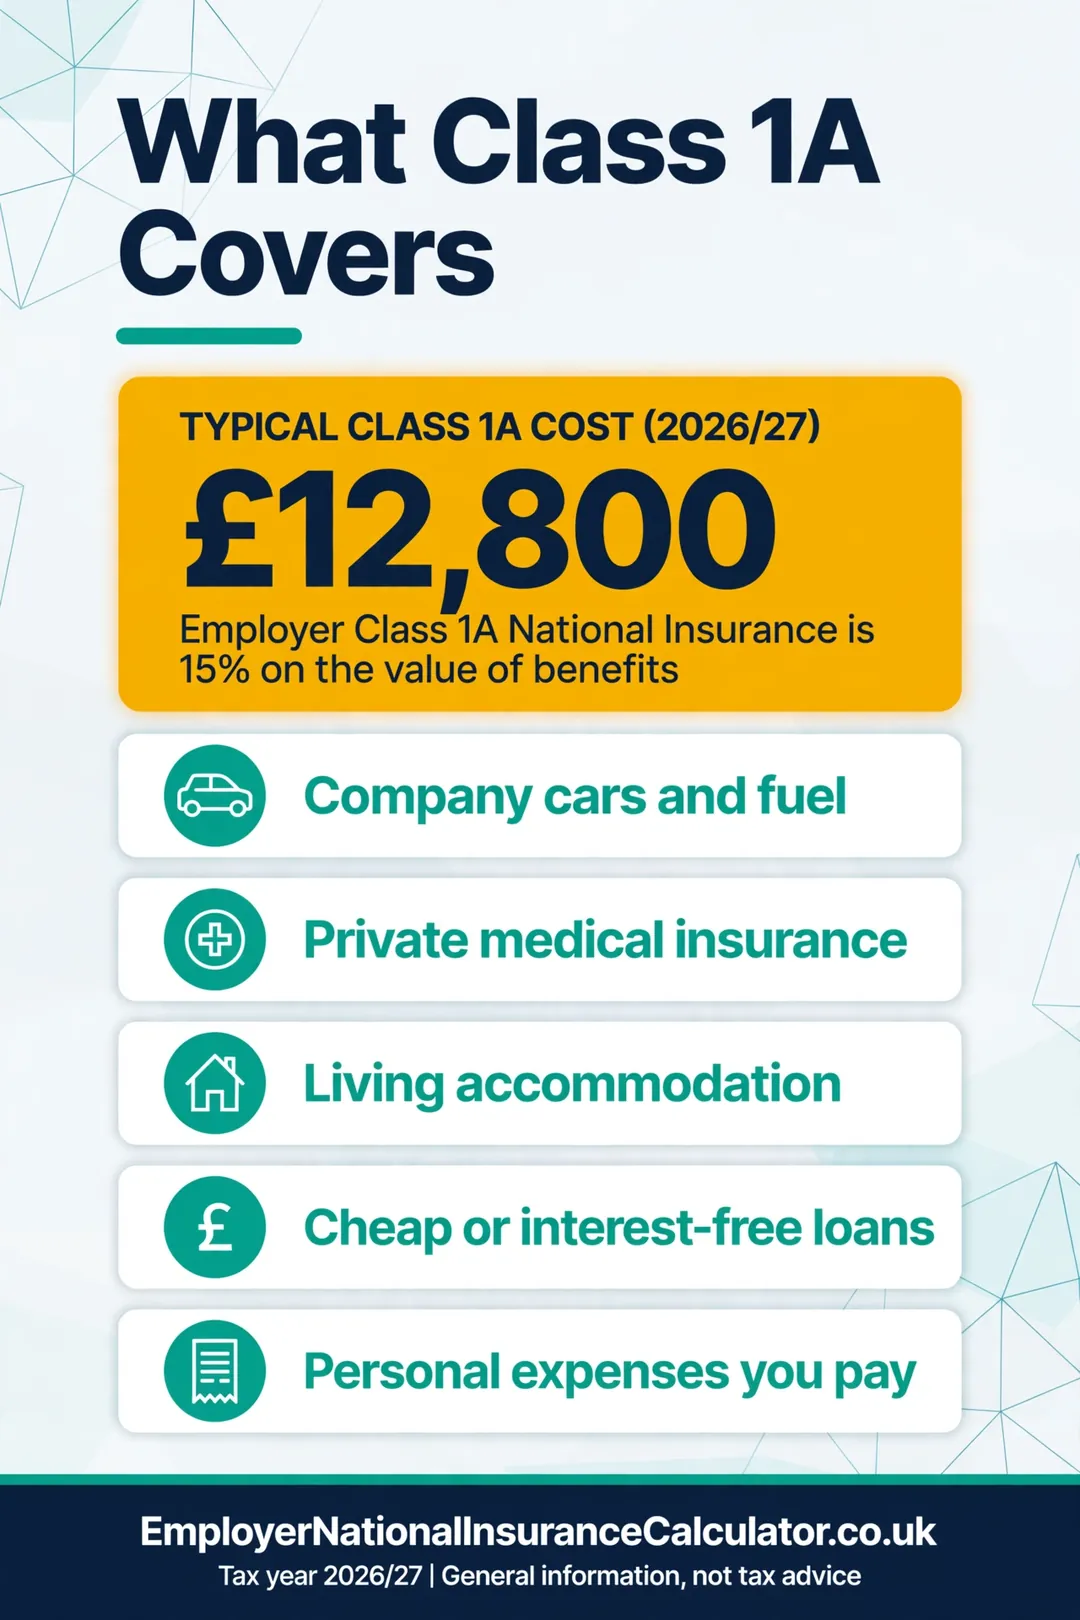
Class 1A applies to benefits you give to employees or directors that are taxable but not subject to Class 1 NI. Common examples:
- Company cars and fuel for private use
- Private medical insurance
- Living accommodation
- Loans on very low or no interest
- Personal expenses you pay for, if not covered by an exemption
Employees do not pay NI on these benefits. Only the employer pays Class 1A.
How it is worked out
Class 1A = taxable value of benefits × 15%
| Benefits in the year | Class 1A at 15% |
|---|---|
| £2,000 | £300 |
| £5,000 | £750 |
| £10,000 | £1,500 |
| £20,000 | £3,000 |
| £50,000 | £7,500 |
A company car with a taxable benefit of £8,000 a year costs £1,200 in Class 1A. The employee pays income tax on the £8,000 as well.
Example: a small business with three benefits
| Benefit | Value |
|---|---|
| Company car for a manager | £7,500 |
| Private medical insurance for two staff | £2,400 |
| Interest-free loan | £600 |
| Total | £10,500 |
Class 1A: £10,500 × 15% = £1,575, due by 22 July.
Key dates
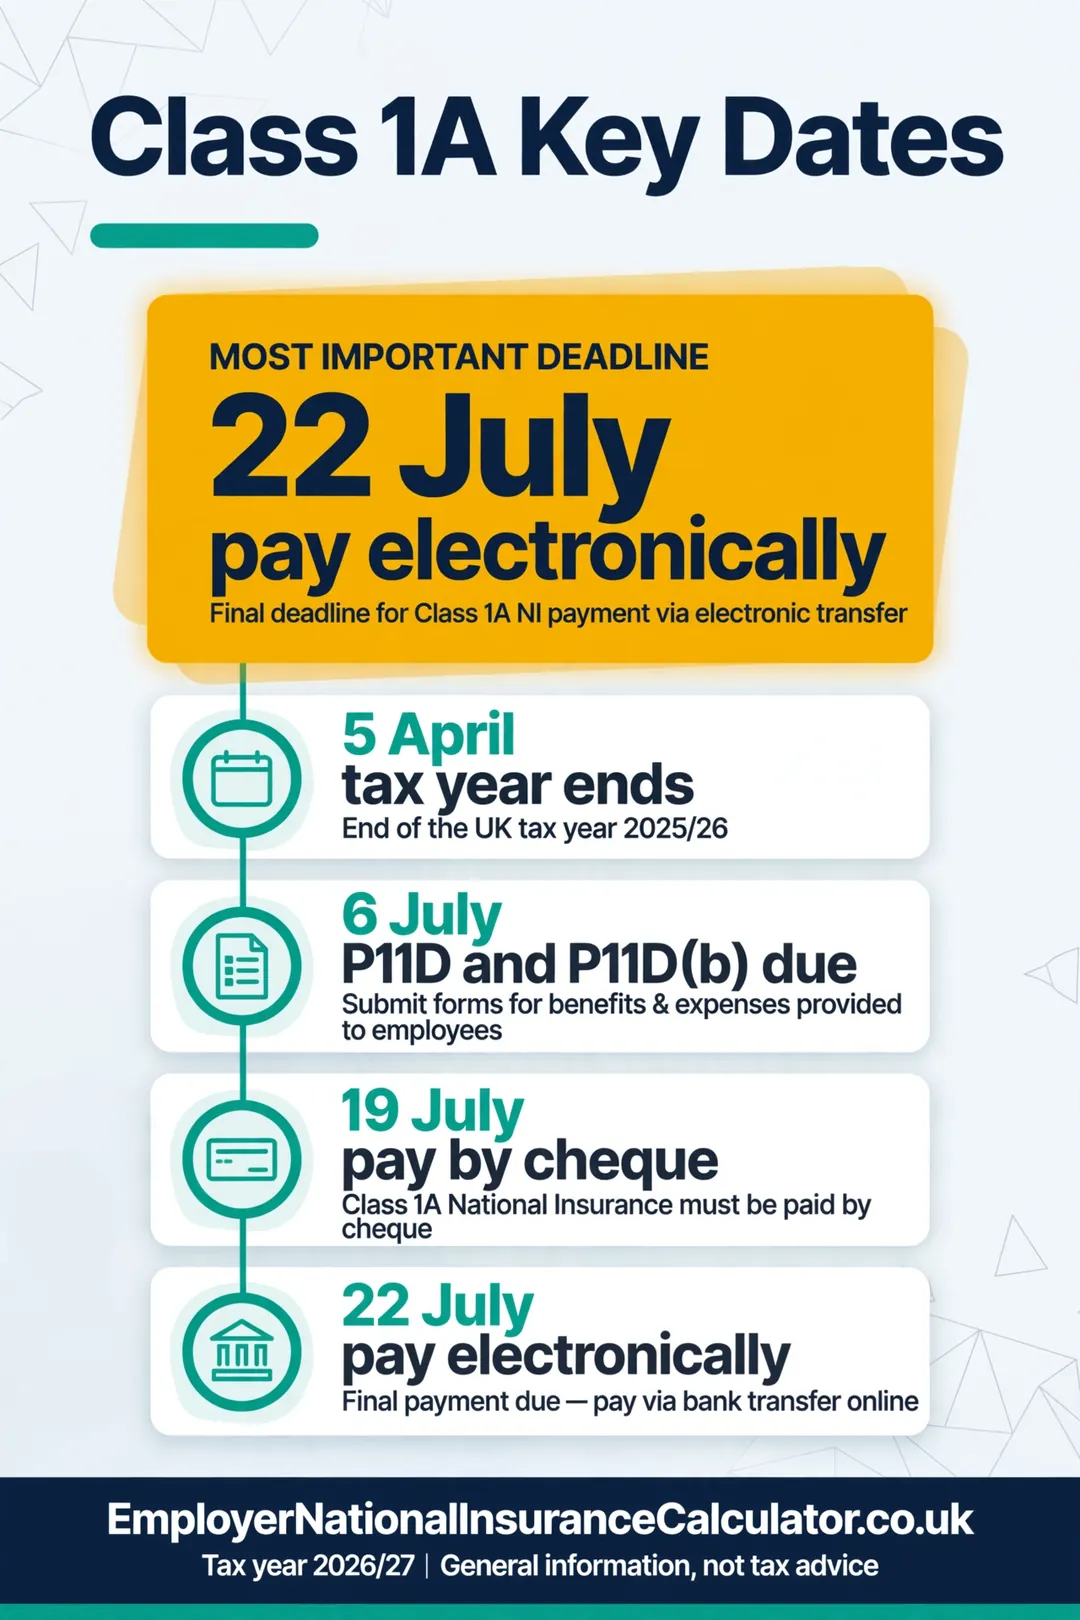
| Date | What |
|---|---|
| 5 April | Tax year ends |
| 6 July | Deadline for P11D and P11D(b) |
| 19 July | Class 1A payment due, cheque |
| 22 July | Class 1A payment due, electronic |
The P11D(b) is the form that shows the total Class 1A due. You must send it even if you have no benefits to report, unless you tell HMRC you no longer need to.
Benefits that do not attract Class 1A
- Benefits that are covered by the trivial benefits rule (£50 or less)
- Benefits covered by an HMRC exemption
- Items covered by a PAYE Settlement Agreement, which attract Class 1B instead
- Workplace parking and certain work-related training
What is payrolling?
Payrolling benefits means you report and tax them through your normal payroll during the year, instead of on a P11D after it. It changes how the employee’s income tax is collected. It does not remove Class 1A. You still pay Class 1A on payrolled benefits, and you report the total on a P11D(b) by 6 July, with payment by 22 July.
Payrolling can reduce paperwork and spread the employee’s tax across the year. The government has also announced plans to make payrolling of benefits compulsory in future years, so check the start date on GOV.UK.
Class 1A and Employment Allowance
Employment Allowance can reduce your Class 1A bill as well, if there is allowance left after your secondary Class 1 NI. Your payroll software handles this. See the Employment Allowance guide and how to pay HMRC.
| Business | Class 1 NI | Class 1A | Total | Allowance used | To pay |
|---|---|---|---|---|---|
| Small | £6,000 | £1,575 | £7,575 | £7,575 | £0 |
| Mid | £10,000 | £1,575 | £11,575 | £10,500 | £1,075 |
Case study: a company car
A company gives an employee a car with a taxable benefit of £9,000 a year.
| Item | Amount |
|---|---|
| Class 1A at 15% | £1,350 |
| Due date | 22 July after the tax year |
| Employee income tax at 20% on £9,000 | £1,800 |
| Employee income tax at 40% on £9,000 | £3,600 |
The employer pays the Class 1A. The employee pays the tax, either through a tax code adjustment or through payroll if the benefit is payrolled.
Calculating the cost of a benefit
When you offer a benefit, count the employer cost, not only the value to the employee.
| Benefit | Taxable value | Class 1A | Total employer cost (value plus Class 1A) |
|---|---|---|---|
| Private medical cover | £1,200 | £180 | £1,380 |
| Company car | £8,000 | £1,200 | £9,200 |
| Low-interest loan | £500 | £75 | £575 |
The comparison with paying the same value as salary is stark. Salary costs the employer 15% employer NI above the threshold as well, and the employee also pays 8% NI and income tax. A benefit usually costs the employer the same 15%, but the employee pays income tax only, with no employee NI.
Mistakes to avoid
- Missing the 6 July deadline for P11D forms. Penalties apply.
- Paying Class 1A late. Interest runs from the day after the due date.
- Treating benefits as expenses when they are really taxable.
- Forgetting that payrolled benefits still attract Class 1A.
- Not sending a P11D(b) when Class 1A is due.
Related reading
For the 15% rate across all classes, see the rates page. For payment deadlines in one place, see how to pay employer NI. For the other benefits-related charge, see Class 1B and PSAs.
Common benefits and their Class 1A cost
| Benefit | Example taxable value | Class 1A at 15% |
|---|---|---|
| Company car, mid-range | £6,000 | £900 |
| Electric company car | £2,000 | £300 |
| Private medical insurance, one employee | £900 | £135 |
| Medical insurance, 10 employees | £9,000 | £1,350 |
| Low-interest loan | £400 | £60 |
Company car values depend on list price, CO2 emissions and fuel type, so ask your payroll provider or use HMRC’s company car tool for your actual figure.
A year-end routine for Class 1A
| When | What to do |
|---|---|
| March | List all benefits given in the year |
| April | Gather values: invoices, car details, loan balances |
| By 6 July | File P11D forms and the P11D(b) |
| By 22 July | Pay Class 1A (19 July by cheque) |
| Afterwards | Keep copies for at least three years |
Reducing Class 1A
You can lower the Class 1A bill by not offering a taxable benefit, by choosing electric company cars, which have a low taxable value, or by offering exempt benefits instead. Any change should fit the needs of your staff, not only the tax bill.
Frequently asked questions
What is the Class 1A rate for 2026/27?
15%.
When do I pay Class 1A?
By 22 July after the tax year ends, if you pay electronically. By 19 July if you pay by cheque.
Do employees pay Class 1A?
No. Only the employer does.
What is the difference between Class 1 and Class 1A?
Class 1 is charged on pay through payroll. Class 1A is charged once a year on benefits that are reported on a P11D or payrolled.
Is Class 1A paid on company cars?
Yes, on the taxable benefit value of the car and any fuel.
What if I payroll my benefits?
Income tax is collected through payroll during the year. You still pay Class 1A on the benefits once a year.
Do I have to register to payroll benefits?
Yes. You must register with HMRC before the start of the tax year in which you begin.
Does Employment Allowance reduce Class 1A?
It can, if allowance remains after your secondary Class 1 NI. See the allowance guide.
How is Class 1A different from Class 1B?
Class 1B is paid on items in a PAYE Settlement Agreement. See Class 1B.
Related guides
- Class 1B NI and PAYE Settlement Agreements (2026/27)
- Employer NI Rates 2026/27: All Rates and Thresholds
- How and When to Pay Employer NI to HMRC
- Employer NI on Statutory Pay and Redundancy (2026/27)
- Employment Allowance 2026/27: £10,500 Off Employer NI
Official sources
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
One Comment
Comments are closed.