Employer NI Calculator 2025/26
Employer NI calculator
Add each pay level in your team. Get the bill, the cost and the working.
Loading the calculator…
Estimate only. Independent tool, not affiliated with HMRC. Rates checked 20 October 2026. Real payroll rounds each pay period.
For 2025/26 (6 April 2025 to 5 April 2026), employers paid 15% National Insurance on pay above £5,000 a year. Use this calculator for late payroll runs, year-end corrections and past records. It is already set to 2025/26.
In this guide15 sections
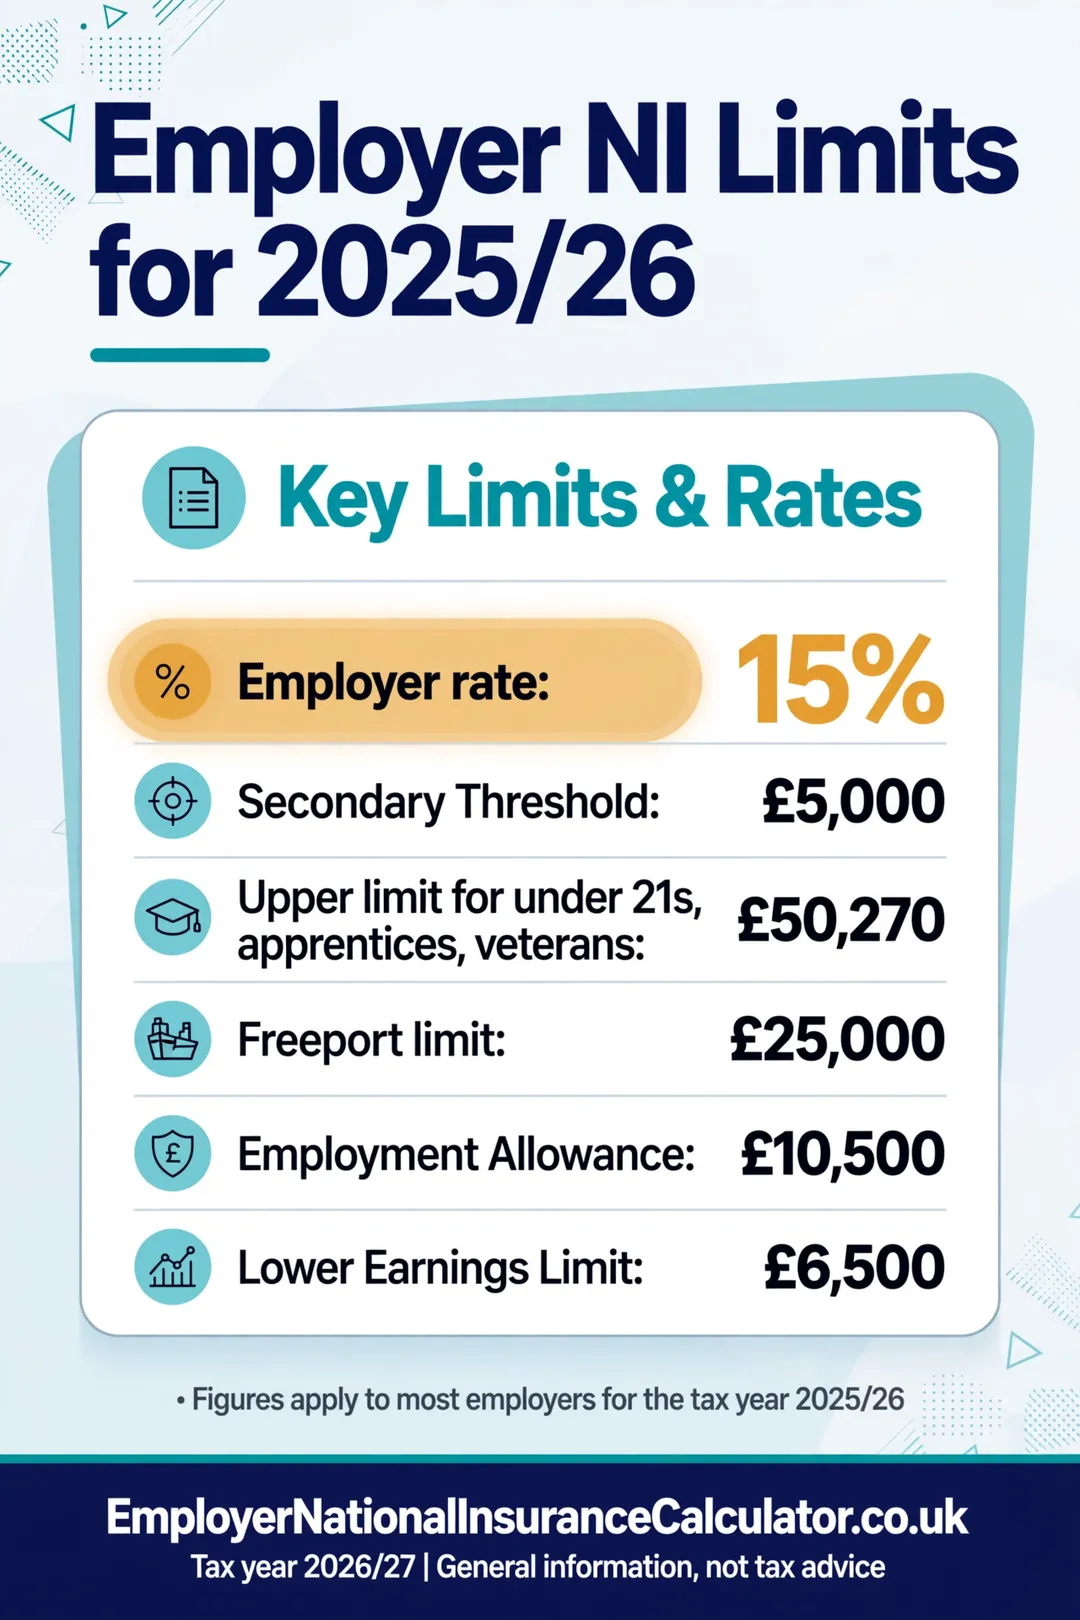
2025/26 rates and limits
| Item | 2025/26 |
|---|---|
| Employer rate | 15% |
| Secondary Threshold | £5,000 a year (£417 a month, £96 a week) |
| Upper Secondary Threshold (under 21, apprentices under 25, veterans) | £50,270 |
| Freeport and Investment Zone threshold | £25,000 |
| Employment Allowance | £10,500 |
| Lower Earnings Limit | £6,500 |
What differs from 2026/27
Very little. The rate and the main thresholds are the same. The Lower Earnings Limit rose from £6,500 to £6,708 in April 2026. If you are checking 2026/27 instead, use the main calculator.
| Item | 2025/26 | 2026/27 |
|---|---|---|
| Employer rate | 15% | 15% |
| Secondary Threshold | £5,000 | £5,000 |
| Employment Allowance | £10,500 | £10,500 |
| Lower Earnings Limit | £6,500 | £6,708 |
What differs from 2024/25
A lot. The rate was 13.8% and the threshold was £9,100 in 2024/25. Employment Allowance was £5,000, and firms with an NI bill over £100,000 could not claim it. All three changed from April 2025. See the rates history table for the full run.
Example for 2025/26
One employee on £30,000:
- Pay above £5,000: £25,000
- Employer NI at 15%: £3,750
- Total cost: £33,750
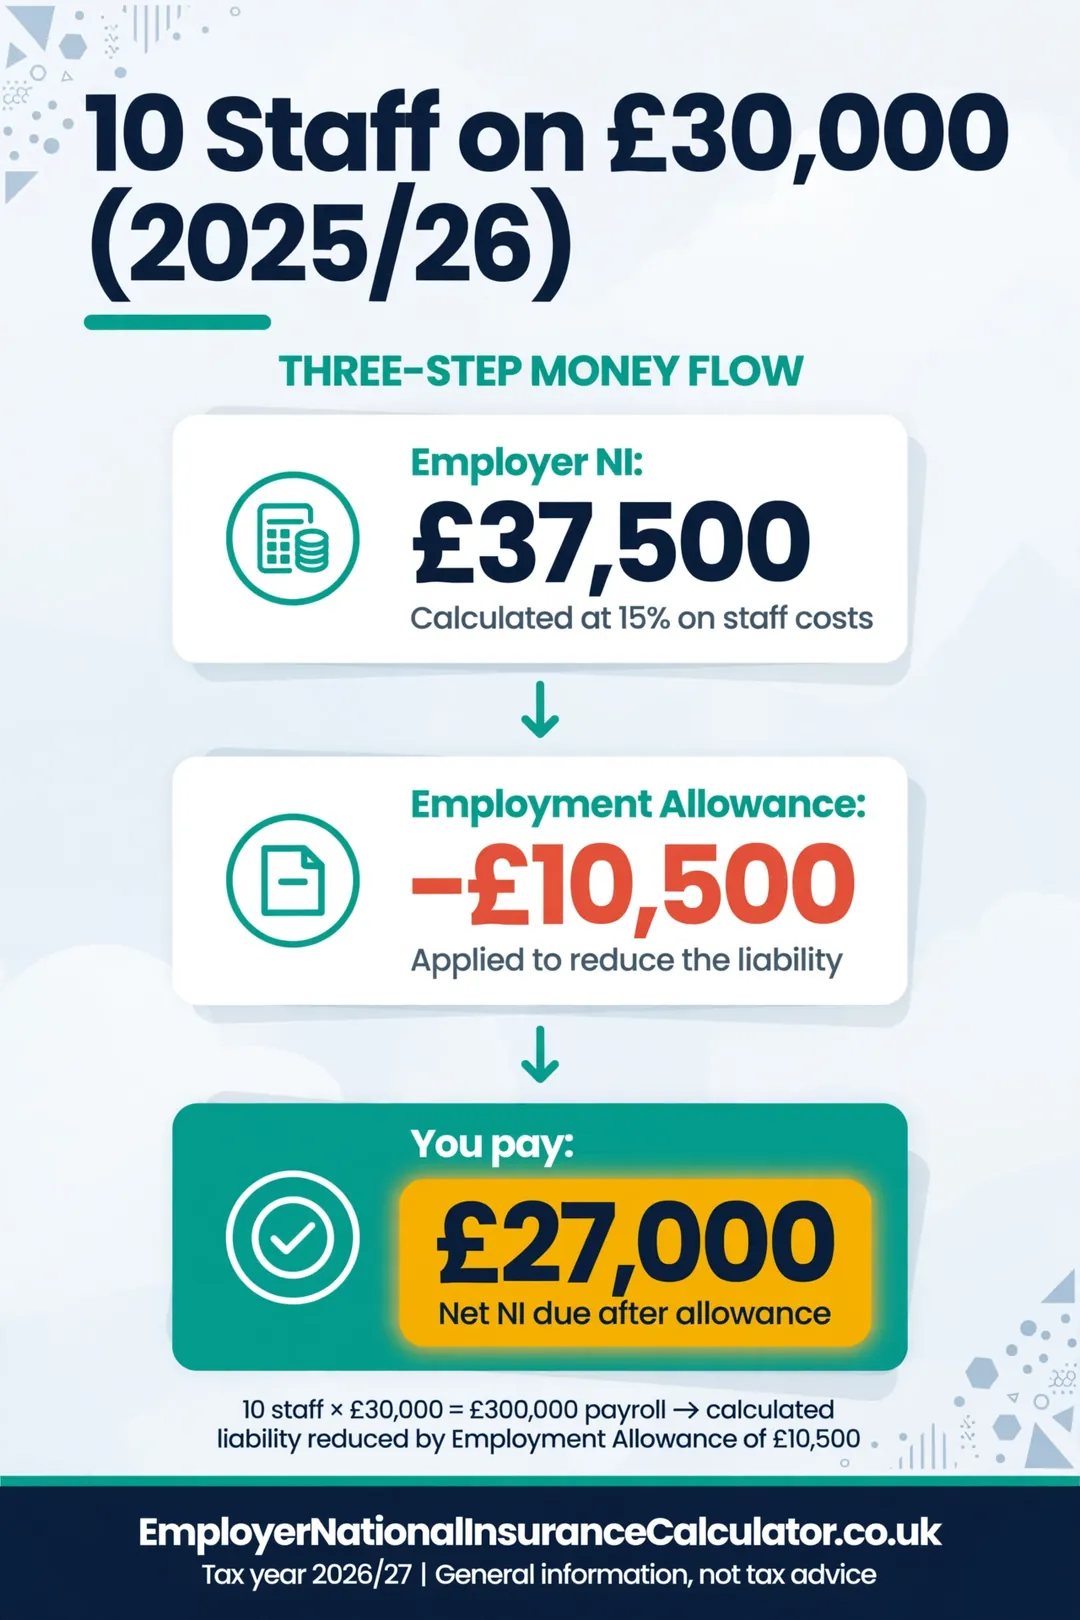
Ten employees on £30,000 would cost £37,500 in NI. After £10,500 Employment Allowance, you pay £27,000.
Missed the allowance last year?
If you were eligible for Employment Allowance in 2025/26 and forgot to claim it, you may be able to claim it now. Our guide to claiming Employment Allowance covers backdating.
For a business that paid £14,250 in employer NI in 2025/26 and did not claim, the missed allowance is worth £10,500. That is the difference between a £14,250 bill and a £3,750 bill.
When you still need 2025/26 figures
- Late or corrected payroll. If you find an error in last year’s run, you must correct it with the old year’s thresholds.
- Year-end accounts. A company with a year end of 31 December 2026 has three months in 2025/26 and nine months in 2026/27.
- Employment Allowance back-claims. HMRC checks the year you claim for, not the current one.
- Cost reviews. Comparing last year with this year shows whether a pay rise or a new hire changed your bill.
- Disputes and enquiries. If HMRC queries a year, you need the figures for that year.
Straddling two tax years
NI follows the tax year, which runs from 6 April to 5 April. Your accounting year may not. If your accounting year runs to 31 March, 30 June or 31 December, split payroll by the date pay was made.
| Pay date | Tax year | Rates to use |
|---|---|---|
| 5 April 2026 | 2025/26 | 2025/26 |
| 6 April 2026 | 2026/27 | 2026/27 |
| 31 March 2026 | 2025/26 | 2025/26 |
| 30 April 2026 | 2026/27 | 2026/27 |
Since 2025/26 and 2026/27 share the same rate and Secondary Threshold, the split matters mostly for the Lower Earnings Limit and for the Employment Allowance, which resets each April.
Example: five staff in 2025/26
A shop pays five staff £24,000 each across 2025/26.
- Employer NI per person: (£24,000 − £5,000) × 15% = £2,850
- Total for five: £14,250
- Employment Allowance: £10,500
- Left to pay: £3,750
In 2024/25 the same shop would have paid 5 × (£24,000 − £9,100) × 13.8% = £10,281, less a £5,000 allowance, which is £5,281. The 2025/26 bill was £1,531 lower even with the higher rate, because of the larger allowance.
Example: a larger employer in 2025/26
A firm of 60 employees averages £27,000 each.
| Item | Amount |
|---|---|
| Employer NI per person | £3,300 |
| Total for 60 employees | £198,000 |
| Employment Allowance | −£10,500 |
| Bill to pay | £187,500 |
For a firm this size the allowance cuts the bill by less than 2%. Reliefs, such as the 0% rate for under-21s and apprentices, matter more. See the exemptions guide.
Where the 2025/26 calculator is different
Only the year switch. The 2025/26 setting uses the Lower Earnings Limit of £6,500 and the same 15% rate. If you want the sums for 2024/25, choose that year in the main calculator, where the rate is 13.8% and the threshold £9,100. The “Compare years” tab shows all three side by side for the same payroll.
Reading last year’s rates against this year’s
Compare the two years side by side on the 2025/26 rates page and the 2026/27 rates page. The only change in the headline table is the Lower Earnings Limit. If you are reconciling year-end payroll, make sure the software used the right year for each pay date.
A reconciliation checklist
- Total the employer NI from your payroll reports for the year.
- Compare it with HMRC’s end-of-year statement in your online account.
- Check that Employment Allowance appears as a credit.
- Check that the category letters were right all year, especially for under-21s, apprentices and veterans.
- Investigate any difference larger than a few pounds.
- Keep the working papers for at least three years after the end of the tax year.
Frequently asked questions
What was the employer NI rate in 2025/26?
15% on pay above £5,000 a year. It rose from 13.8% on 6 April 2025.
Was Employment Allowance £10,500 in 2025/26?
Yes. It was £5,000 in 2024/25 and rose to £10,500 from April 2025. The £100,000 cap on who could claim was also removed.
Can I still run payroll for 2025/26?
You can submit corrections for earlier years through payroll or by writing to HMRC. Use the 2025/26 thresholds, not the current ones, for those figures.
How do I switch to the current year?
Use the tax year box on the main calculator, or open the 2026/27 rates page.
Can I claim Employment Allowance for 2025/26 now?
In many cases yes. You can usually claim for up to four previous tax years by sending an amended Employer Payment Summary. See how to claim.
Which year’s rates do I use for a payment made in April 2026?
Use the date of payment. Pay on or after 6 April 2026 falls into 2026/27, and pay on or before 5 April 2026 falls into 2025/26.
Is the 2025/26 employer NI calculator the same as the 2026/27 one?
It works in the same way. Only the year setting changes. The employer rate and Secondary Threshold are the same, but the Lower Earnings Limit differs.
Can I check last year’s total against HMRC’s figure?
Yes. Your online PAYE account shows what HMRC holds for each tax year.
What is the monthly threshold for 2025/26?
£417 a month, £385 every four weeks and £96 a week, the same as in 2026/27.
How long should I keep 2025/26 payroll records?
At least three years after the end of the tax year. For 2025/26 that means until at least 5 April 2029.
Related guides
- Employer National Insurance Calculator 2026/27
- Employer NI Rates 2025/26: Rates and Thresholds
- Employer NI Rates History: 2023/24 to 2026/27
- How to Claim Employment Allowance (Step by Step)
Official sources
- National Insurance rates and categories
- HMRC: Rates and thresholds for employers 2025 to 2026
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.