Employer NI Rates 2026/27: All Rates and Thresholds
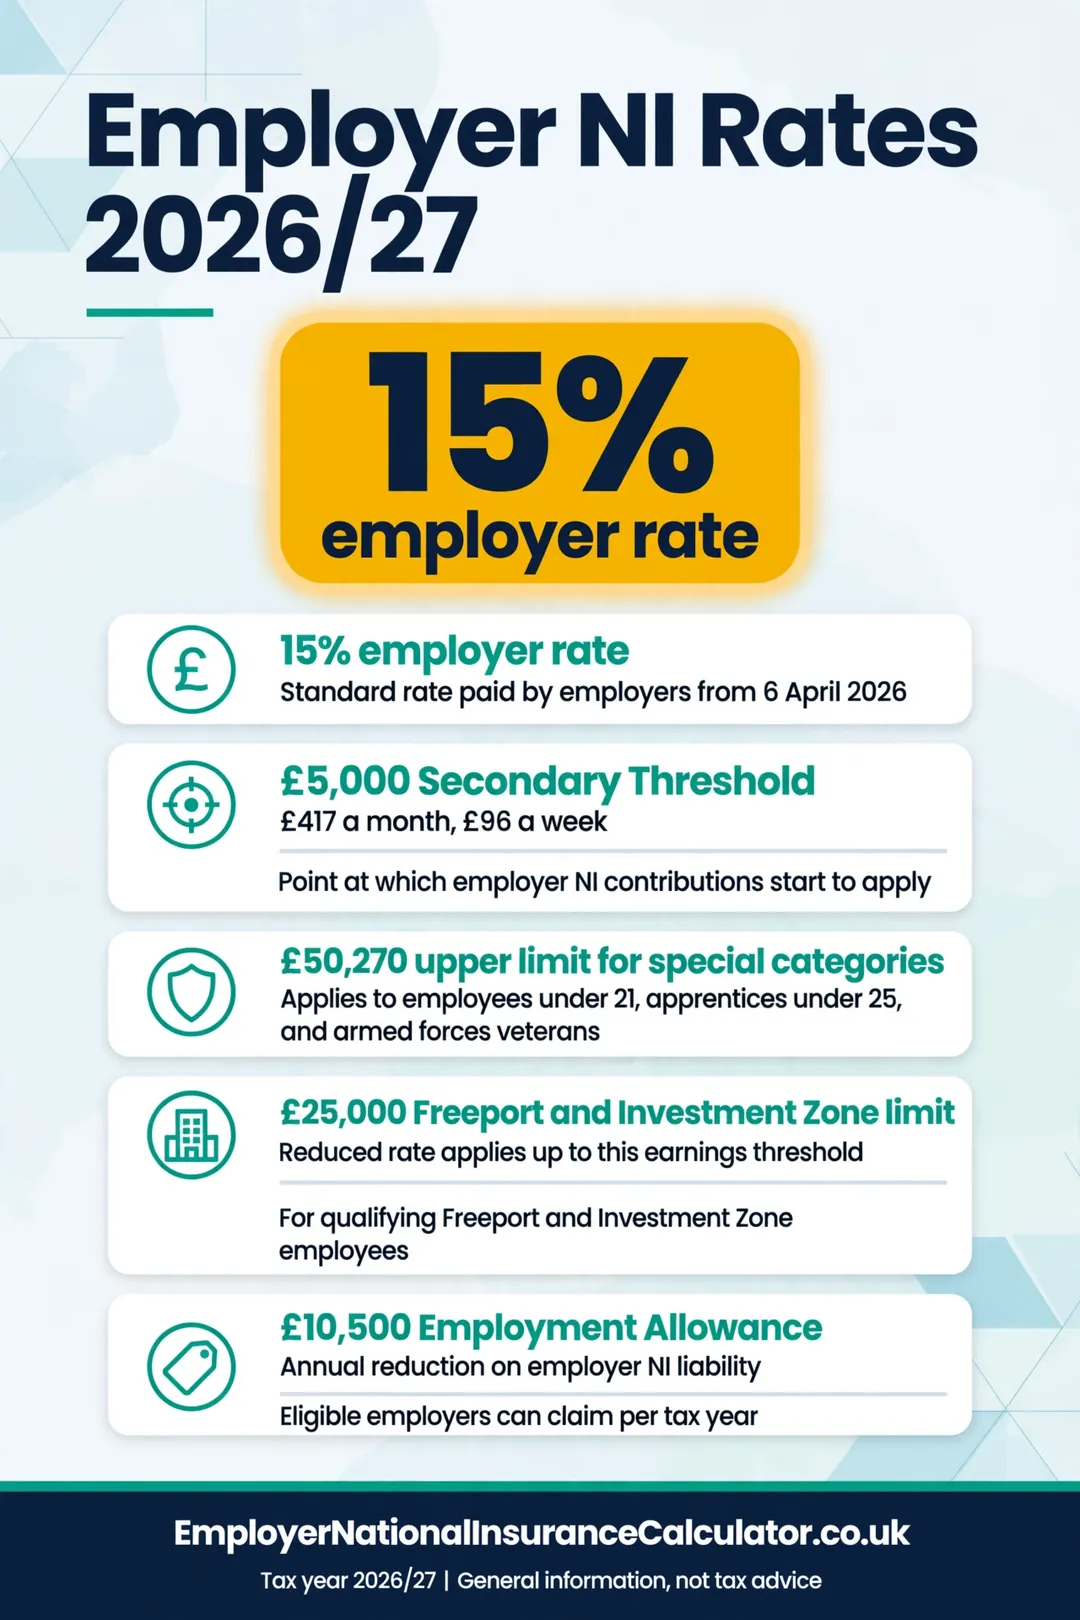
The employer National Insurance rate for 2026/27 is 15%. You pay it on each employee’s earnings above £5,000 a year. Class 1A on benefits is also 15%. Employment Allowance can cut your yearly bill by up to £10,500. This page lists every rate and shows what each one means in pounds.
In this guide15 sections
Employer NI rates at a glance
| Item | 2026/27 |
|---|---|
| Employer Class 1 rate | 15% |
| Class 1A rate (benefits in kind) | 15% |
| Class 1B rate (PAYE Settlement Agreements) | 15% |
| Secondary Threshold | £5,000 a year (£417 a month, £96 a week) |
| Upper Secondary Threshold | £50,270 a year |
| Freeport and Investment Zone threshold | £25,000 a year |
| Employment Allowance | £10,500 |
The Secondary Threshold is frozen at £5,000 until April 2031. Each pay rise therefore pulls more pay into the 15% charge.
How much is that in pounds?
| Annual salary | Employer NI | Cost to employ |
|---|---|---|
| £20,000 | £2,250 | £22,250 |
| £30,000 | £3,750 | £33,750 |
| £50,000 | £6,750 | £56,750 |
| £80,000 | £11,250 | £91,250 |
| £120,000 | £17,250 | £137,250 |
For any other salary, use the employer NI calculator. The salary table covers more pay levels.
The two numbers that matter most
Two figures decide almost every employer NI bill: the 15% rate and the £5,000 threshold. Together they give one simple rule.
Employer NI = 15% × (pay − £5,000)
Everything else on this page changes either the rate or the threshold for a particular type of employee. The relief rates raise the threshold to £50,270 or £25,000. Employment Allowance takes a fixed amount off the total at the end.
Employee rates, for comparison
Employees pay National Insurance too, but at lower rates. They pay 8% on earnings between £12,570 and £50,270, and 2% above that. This is taken from their pay, and it is separate from your cost. See employer NI vs employee NI.
| Pay band | Employer rate | Employee rate |
|---|---|---|
| Up to £5,000 | 0% | 0% |
| £5,000 to £12,570 | 15% | 0% |
| £12,570 to £50,270 | 15% | 8% |
| Above £50,270 | 15% | 2% |
The employer always pays more than the employee on the same pay. At £30,000 the employer pays £3,750 and the employee pays £1,394.40.
Rates that cut the bill to nil
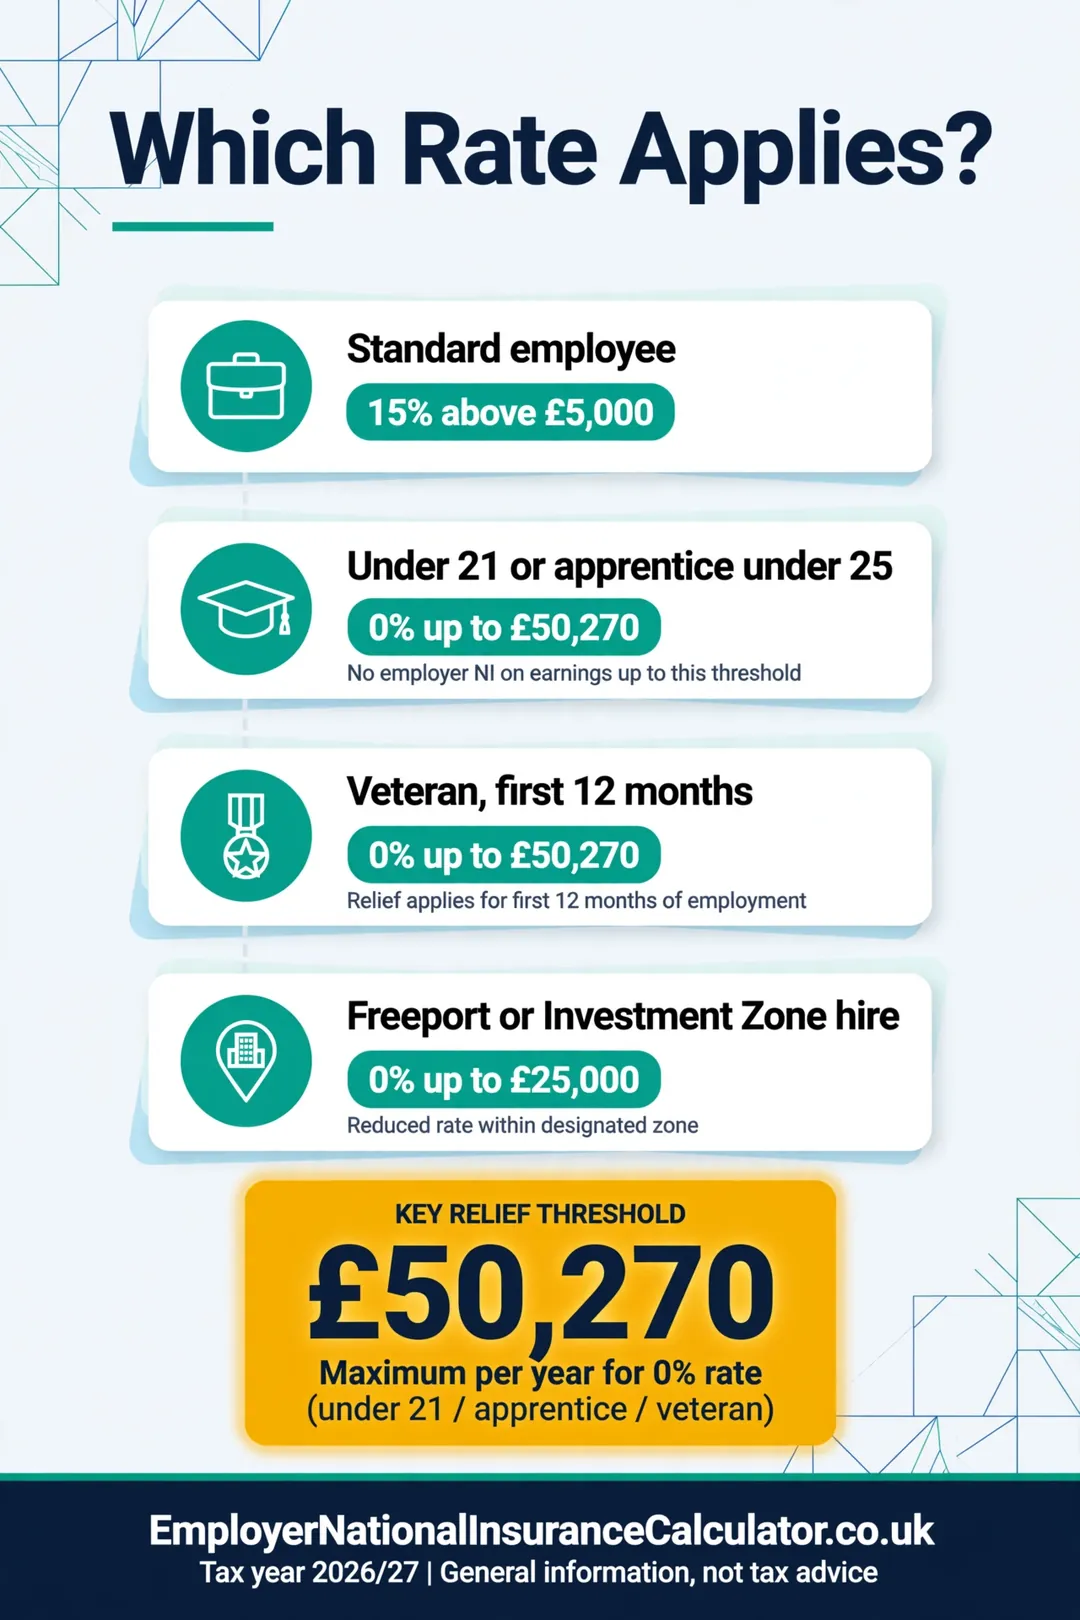
Some staff attract a 0% employer rate up to £50,270 a year. These are employees under 21, apprentices under 25 and veterans in their first year of civilian work. Staff working at a Freeport or Investment Zone have a 0% rate up to £25,000. Details are in the exemptions guide.
Which rate applies to whom
- Standard employees are charged 15% above £5,000.
- Under-21s (category M) and apprentices under 25 (category H) are charged 0% up to £50,270.
- Veterans (category V) are charged 0% up to £50,270 for their first 12 months.
- Freeport and Investment Zone staff are charged 0% up to £25,000.
- Directors are charged on annual earnings, not monthly.
What each relief is worth on the same £30,000 salary:
| Employee | Rate up to the limit | Employer NI |
|---|---|---|
| Standard (A) | 15% above £5,000 | £3,750 |
| Freeport (F) | 0% up to £25,000 | £750 |
| Under 21 (M) | 0% up to £50,270 | £0 |
| Apprentice (H) | 0% up to £50,270 | £0 |
| Veteran (V), first 12 months | 0% up to £50,270 | £0 |
Class 1A and Class 1B explained
Class 1A is paid on work benefits you give employees, such as company cars and private medical insurance. The rate is 15% of the value of the benefits. It is due by 22 July after the tax year ends. Read the full guide at Class 1A National Insurance.
Class 1B is paid if you have a PAYE Settlement Agreement. The rate is also 15%. See Class 1B and PSAs.
Neither of these is deducted from the employee’s pay. They are extra costs for the employer.
| Type | What it covers | Rate | Due |
|---|---|---|---|
| Class 1 secondary | Pay above the threshold | 15% | Monthly through PAYE |
| Class 1A | Benefits such as cars and medical cover | 15% | 22 July after the year ends |
| Class 1B | Items in a PAYE Settlement Agreement | 15% | 22 October after the year ends |
Rates by NI category letter
| Category | Who | Employer rate up to the limit |
|---|---|---|
| A | Most employees | 15% above £5,000 |
| H | Apprentices under 25 | 0% up to £50,270 |
| M | Employees under 21 | 0% up to £50,270 |
| V | Veterans in first year of civilian work | 0% up to £50,270 |
| F, I, L, S | Freeport and Investment Zone staff | 0% up to £25,000 |
Above each limit, 15% applies. The letter is set in your payroll software. A wrong letter means a wrong bill, so check each new starter. The NI category letters guide has the full list.
How the rate works across pay periods
The 15% rate is the same however often you pay. What changes is the threshold you subtract first.
| Pay period | Threshold | Employer NI on pay of £2,000 in that period |
|---|---|---|
| Weekly | £96 | £285.60 |
| Four-weekly | £385 | £242.25 |
| Monthly | £417 | £237.45 |
Smaller periods have smaller thresholds, so the same pay produces a bigger bill per period. Over a whole year the totals come out close together. See the monthly calculator.
Which rate applies? A five-minute check
- Is the employee under 21? Use category M.
- Are they an apprentice under 25 on an approved apprenticeship? Use category H.
- Are they a veteran in their first 12 months of civilian employment? Use category V.
- Do they work mainly at a Freeport or Investment Zone tax site? Check the Freeport rules.
- Otherwise, use the standard letter and the 15% rate.
What a three-person business pays
| Employee | Salary | Category | Employer NI |
|---|---|---|---|
| Sales manager | £42,000 | A | £5,550 |
| Apprentice (age 19) | £20,000 | H | £0 |
| Admin (age 30) | £26,000 | A | £3,150 |
Total: £8,700. Employment Allowance of £10,500 would cover all of it.
What a ten-person business pays
A trade business has ten staff. Two are apprentices under 25, one is under 21, and seven are standard employees.
| Group | Staff | Pay each | Employer NI each | Total |
|---|---|---|---|---|
| Standard | 7 | £34,000 | £4,350 | £30,450 |
| Apprentices | 2 | £20,000 | £0 | £0 |
| Under 21 | 1 | £24,000 | £0 | £0 |
| Bill before allowance | £30,450 | |||
| After Employment Allowance | £19,950 |
Using the right category letter for three of the ten staff saves £7,350 a year.
Frequently asked questions
What is the employer NI rate for 2026/27?
15% on earnings above £5,000 a year per employee. It is the same as 2025/26.
Has the employer NI threshold changed for 2026/27?
No. The Secondary Threshold stays at £5,000 a year and is frozen until April 2031.
Is there a cap on employer NI?
No. The 15% rate applies to all pay above the threshold, with no upper limit. The £50,270 limit only matters for the special 0% categories.
Do small businesses pay a lower rate?
No. They pay the same 15%. They can claim Employment Allowance of up to £10,500 to reduce the bill.
What is the Class 1A rate for 2026/27?
15%. It is charged on the cash-equivalent value of benefits such as company cars.
Do employers pay National Insurance on the first £5,000?
No. The first £5,000 of each employee’s annual pay is free of employer NI.
Are the employer rates the same across the UK?
Yes, the standard rates and thresholds are the same in England, Scotland, Wales and Northern Ireland. The Freeport limit applies only in designated sites.
Where can I find the official rates?
GOV.UK publishes them in the National Insurance rates and letters pages, and HMRC publishes a yearly rates and thresholds table for employers.
Is the employer rate different for directors?
No. Directors attract the same 15% above £5,000. The difference is that the thresholds are applied to the whole year, not each pay period.
Do I pay employer NI on employees over State Pension age?
Yes. Employees over State Pension age pay no NI themselves, but you still pay employer NI at 15% above £5,000. They use category C. See the category letters guide.
Will the 15% rate change next year?
No change to the 15% rate has been announced for 2026/27. See the rate history for how the figures have moved.
Related guides
- Employer NI Thresholds 2026/27: Weekly, Monthly, Yearly
- NI Category Letters for Employers (2026/27)
- Employer NI Exemptions and Reliefs 2026/27
- Employer National Insurance Calculator 2026/27
- Employer NI Rates History: 2023/24 to 2026/27
Official sources
- National Insurance rates and categories
- HMRC: Rates and thresholds for employers 2026 to 2027
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
One Comment
Comments are closed.