Company Pension Contributions for Directors and NI
A limited company can pay into a director’s pension without any employer or employee National Insurance. The payment is normally an allowable business expense for corporation tax. This makes it one of the most efficient ways to take money out of a company, subject to annual limits. This page shows the numbers, the limits and the mistakes to avoid.
In this guide16 sections
Why company pension contributions save NI
Pay a director as salary and the company owes 15% employer NI on pay above £5,000. A pension contribution is not pay. It goes straight into the director’s pension, so there is no employer NI and no employee NI. Corporation tax relief usually applies as well, if the contribution meets the “wholly and exclusively” test.
Salary against company pension contribution
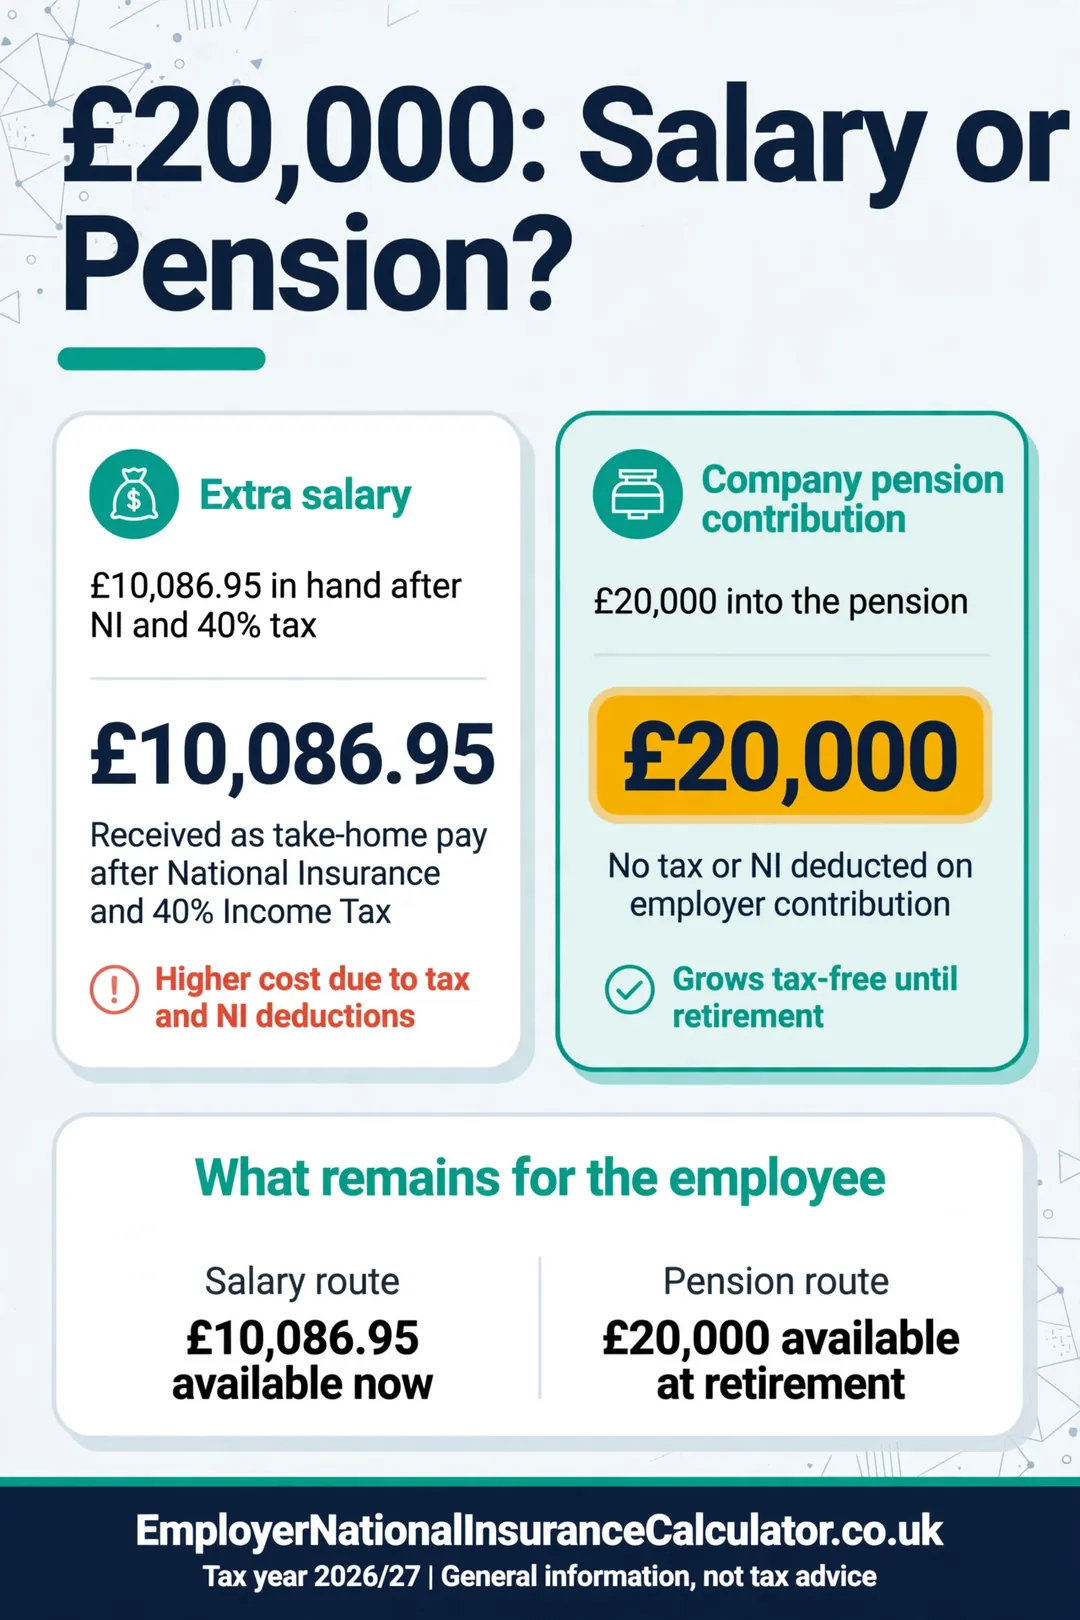
Suppose a company has £20,000 it wants to give to a director who is a higher-rate taxpayer and already above £50,270. To spend £20,000 in total through salary, the company must pay salary of £20,000 ÷ 1.15, because employer NI is added on top.
| Extra salary | Company pension contribution | |
|---|---|---|
| Amount the company spends | £20,000 | £20,000 |
| Employer NI | £2,608.70 | £0 |
| Paid to or for the director | £17,391.30 | £20,000 |
| Employee NI at 2% (above £50,270) | £347.83 | £0 |
| Income tax at 40% | £6,956.52 | £0 |
| Net to director in hand | £10,086.96 | £0 in hand, £20,000 in pension |
The pension route puts the whole £20,000 away for later. Withdrawals later are subject to income tax rules, with a part tax-free. The salary route gives money now but loses a lot to NI and tax.
The limits
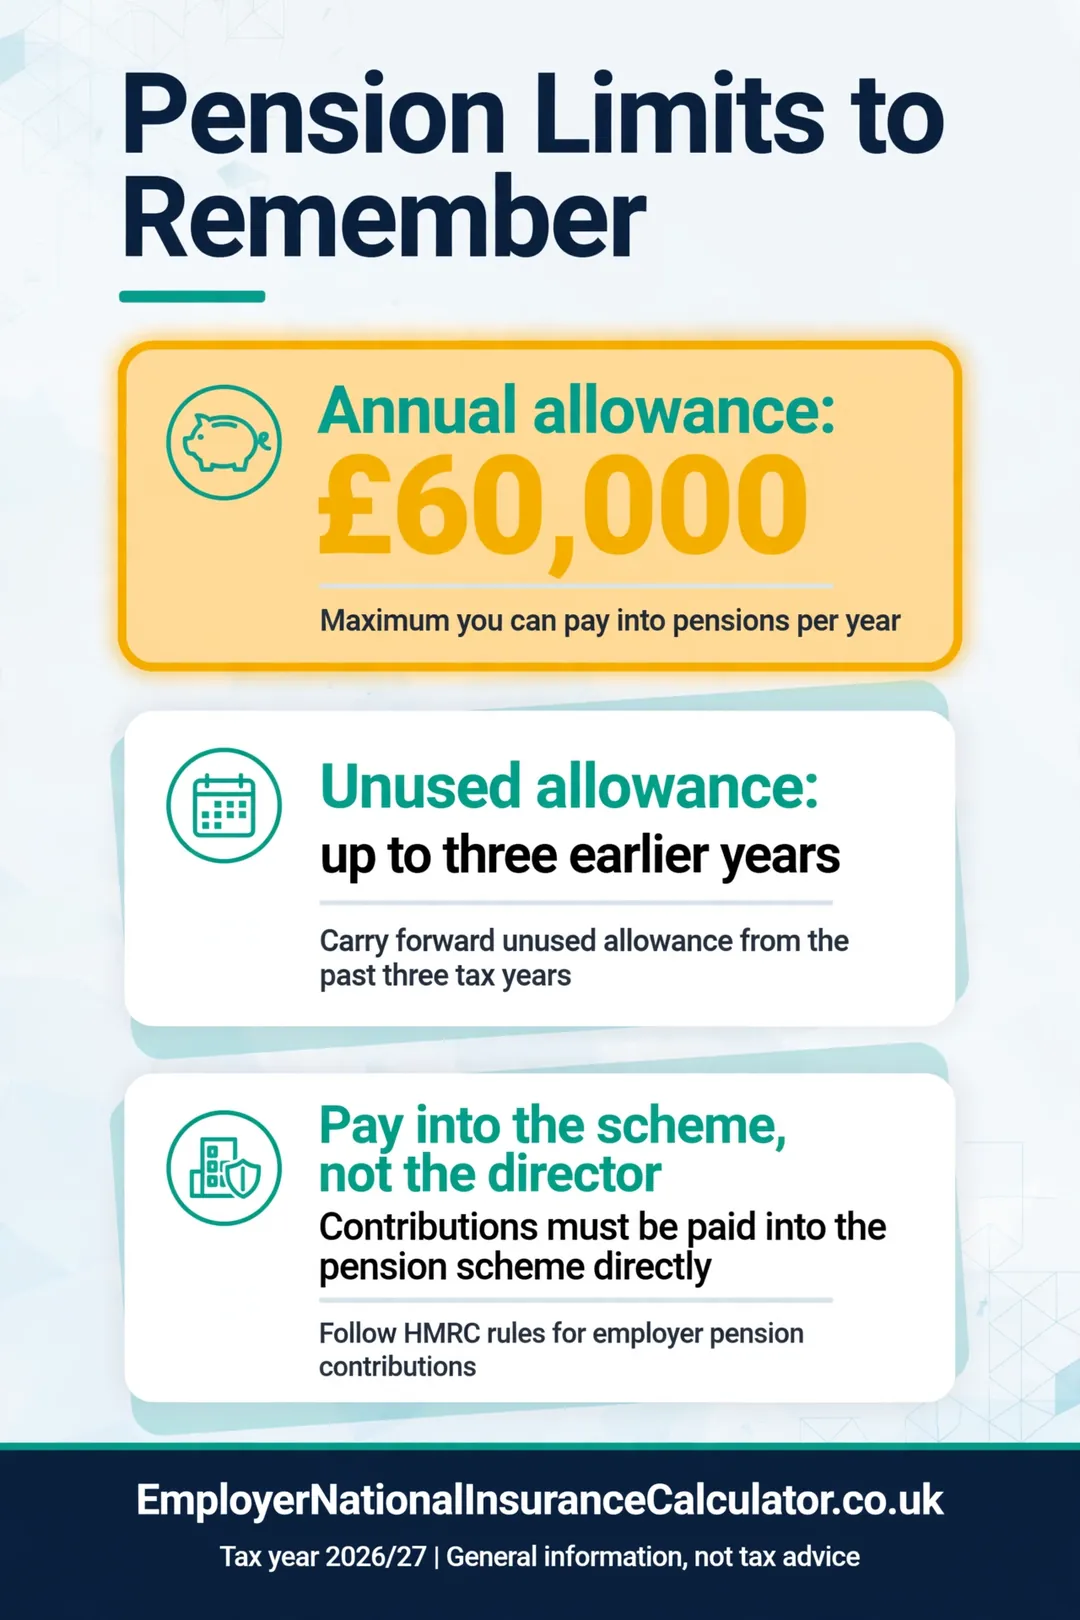
The standard annual allowance is £60,000 across all pension contributions for the year, including the company’s. The company can use unused allowances from the three earlier years, subject to conditions. Very high earners have a lower, tapered allowance. Contributions above the limit can lead to a tax charge.
HMRC also checks that the amount is not so large that it is not a genuine business cost. A contribution of £60,000 in a year when the director’s pay is £12,570 and the company has profits of £70,000 may attract attention.
Which schemes work
- Personal pension (SIPP). The company pays directly into the director’s scheme.
- Small self-administered scheme (SSAS). Allows more control but more complexity.
- Workplace pension. Auto-enrolment schemes accept director contributions too.
Pay through the scheme’s own process. Do not pay the money to the director first.
What it does to the director’s NI record
A pension contribution does not count as earnings. So a director with no salary above £6,708 does not get a qualifying NI year from it. Many directors pay a small salary for the NI record and use pension contributions for the rest. See director salary options.
Salary sacrifice for directors
A director can give up salary in exchange for an employer pension contribution. This can reduce NI as well. From April 2029, the NI saving is capped at £2,000 of sacrificed pay a year. A direct company contribution, not a salary sacrifice, is not affected by the cap. Read the 2029 cap guide.
Example: £30,000 from the company
A company has £30,000 of spare profit and wants to reward its director, who is already above the NI thresholds.
| Route | Cost to the company | Reaches the director |
|---|---|---|
| Extra salary | £30,000 (salary £26,086.96 plus employer NI £3,913.04) | About £15,130.43 after tax and NI |
| Pension contribution | £30,000 | £30,000 in the pension |
Corporation tax relief applies to both. The pension route is clearly more efficient for money the director does not need today. The director gets the money later, taxed under pension rules, with a part tax-free subject to limits.
Example: a director on a basic-rate income
A director takes £12,570 salary and wants to move £15,000 out of the company. As a basic-rate or lower-rate taxpayer, the comparison is closer, because the tax on the alternative is lower.
| Route | Company cost | Reaches the director |
|---|---|---|
| Extra salary | £15,000 | £9,391.30 after 20% tax and 8% NI |
| Pension contribution | £15,000 | £15,000 in the pension |
Even for a basic-rate taxpayer, the pension route avoids the 15% employer NI and keeps more money working. The cost is that the money is locked in until minimum pension age.
When a pension contribution is not the right choice
- The director needs the cash now, for a mortgage or a major purchase.
- The company does not have the profit to support the contribution.
- The contribution would exceed the annual allowance.
- The director is close to the age when benefits can be taken, and wants to use other planning.
Timing and records
Pay the contribution in the accounting year you want to claim it. Keep the scheme’s confirmation. Record it as a company expense, not a director’s loan. If you are not sure about the “wholly and exclusively” test for a large payment, ask your accountant before the year end. See NI on pension contributions for the NI rules in general, and salary sacrifice savings for staff schemes.
Annual allowance and carry-forward: an example
A director’s company wants to contribute £90,000 in 2026/27. The standard annual allowance is £60,000, so the rest has to be covered by carry-forward from earlier years.
| Year | Unused allowance |
|---|---|
| 2023/24 | £20,000 |
| 2024/25 | £15,000 |
| 2025/26 | £10,000 |
| Total carried forward | £45,000 |
2026/27 allowance of £60,000 plus £45,000 of unused allowance gives £105,000 of room. A £90,000 contribution fits, provided the director has the right pension scheme membership in those earlier years. Your adviser must confirm the figures. The numbers in this table are only an example.
Questions to ask before a large payment
- Is the contribution wholly and exclusively for the business?
- Does the company have the cash and profits to support it?
- Is the contribution within the director’s available allowance?
- Does the scheme accept it?
- Is the director near any other limits?
A balanced approach
Many directors use a small salary for the State Pension record, dividends for living costs and company pension contributions for long-term saving. The right mix depends on profits, other income and plans. See the director salary guide for the first step, and NI on pension contributions for the NI rules.
Frequently asked questions
Do company pension contributions for directors attract NI?
No. Employer contributions into a registered pension scheme are not liable to employer or employee NI.
Are they deductible for corporation tax?
Usually yes, if they are wholly and exclusively for the business and are not excessive.
How much can a company pay into a director’s pension?
There is no set company limit, but the annual allowance of £60,000 caps tax-free contributions for the year. Unused allowance from three years back can be used.
Does a pension contribution count as a qualifying NI year?
No. Only earnings count.
Can I pay my pension from the company bank account?
Yes, as long as the payment goes to the scheme and is recorded as a company contribution.
Should I take advice?
Yes. Pension rules and tax limits are detailed, and mistakes can be costly.
Should a director pay into a pension from the company or personally?
A company payment avoids employer and employee NI and usually gets corporation tax relief. A personal payment gets income tax relief but no NI saving.
Is there a minimum contribution?
There is no minimum for a director’s own scheme. Auto-enrolment rules set minimums for staff.
Can I take the money out when I like?
No. Pension savings can usually only be accessed from the minimum pension age. Check the current rules on GOV.UK.
Related guides
- Do Employers Pay NI on Pension Contributions?
- Salary Sacrifice Employer NI Savings (2026/27)
- Director Salary 2026/27: £5,000, £6,708 or £12,570?
- Director National Insurance Calculator 2026/27
- £2,000 Salary Sacrifice Pension Cap From April 2029
Official sources
- National Insurance rates and categories
- HMRC guidance on pension tax relief
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
2 Comments
Comments are closed.