Salary Sacrifice Employer NI Savings (2026/27)
Salary sacrifice NI savings
See what you and your staff save by paying into pensions through salary sacrifice.
Loading the calculator…
Estimate only. Independent tool, not affiliated with HMRC. Rates checked 20 October 2026. Real payroll rounds each pay period.
In 2026/27, an employer saves 15% National Insurance on every pound an employee gives up through pension salary sacrifice. An employee who sacrifices £3,000 saves their employer £450 and themselves £240. From 6 April 2029, only the first £2,000 a year will stay NI-free. Use the calculator, then read on for the examples, the 2029 effect and the checks to make first.
In this guide15 sections
What is salary sacrifice?
The employee agrees to a lower salary, and the employer pays the difference into the employee’s pension. Because the employee’s pay is lower, there is less pay for NI to be charged on. Both sides save. The pension contribution is the same as it would have been through a normal scheme, or larger if the employer shares its saving.
Example: £3,000 sacrificed
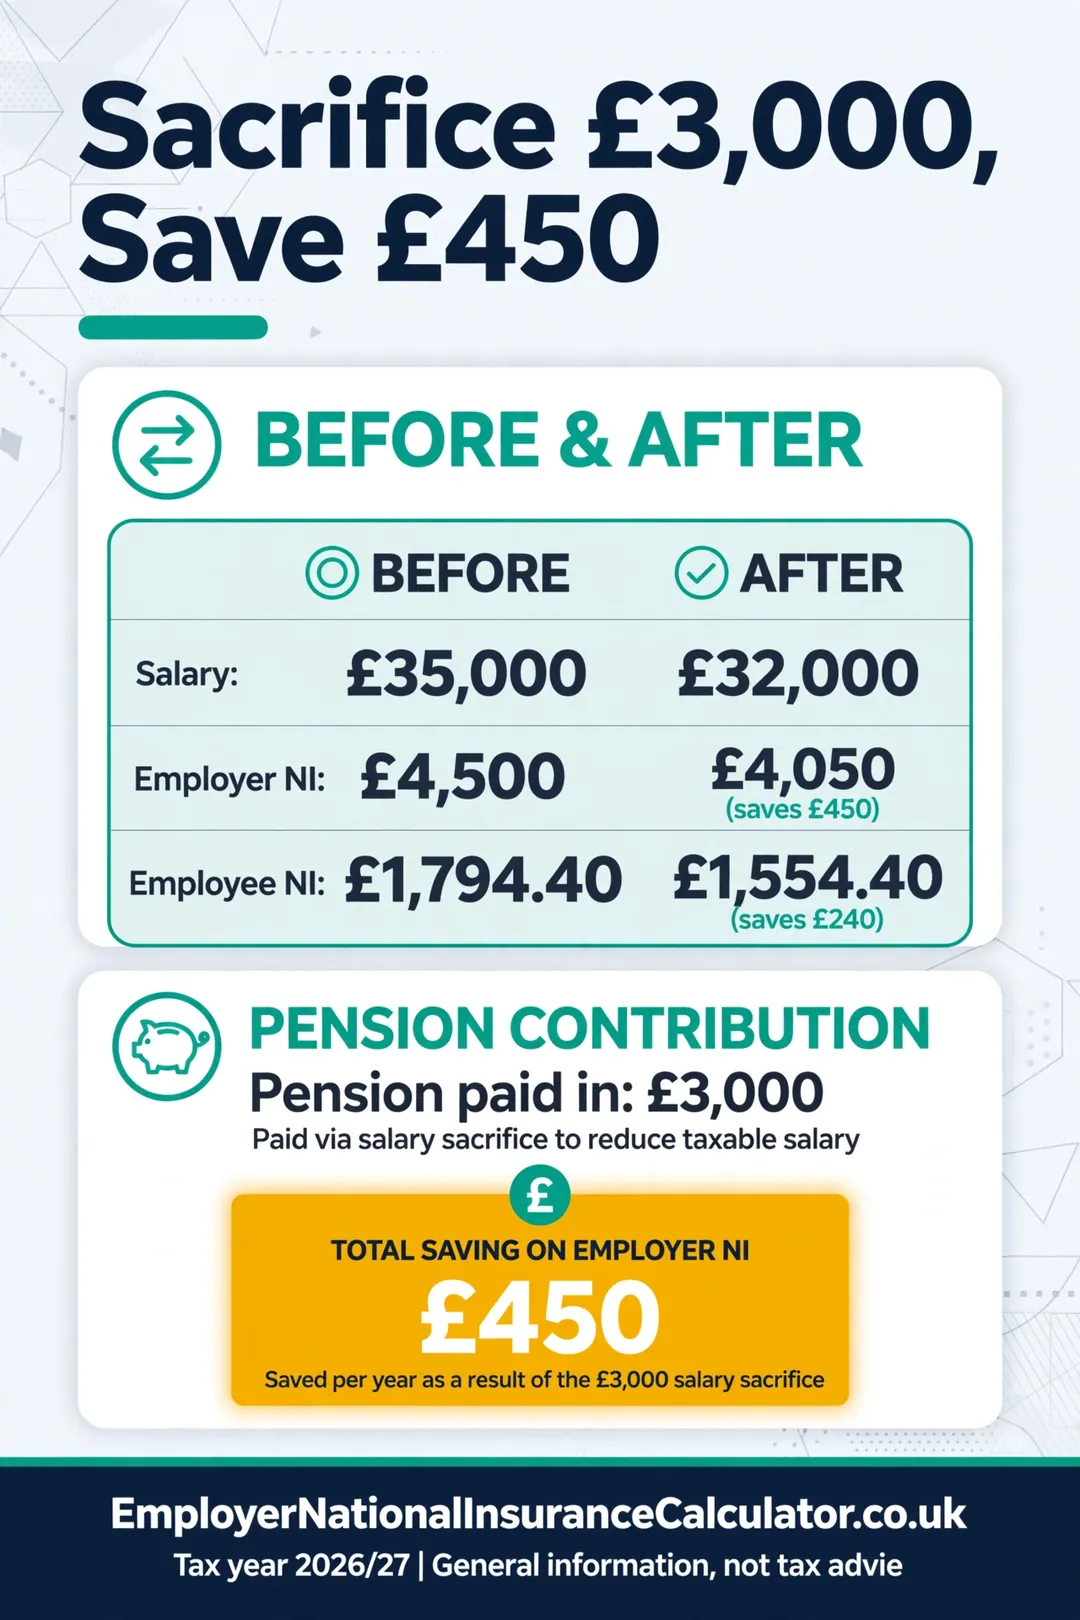
An employee earns £35,000 and sacrifices £3,000 a year into a pension.
| Before | After | |
|---|---|---|
| Salary | £35,000 | £32,000 |
| Employer NI | £4,500 | £4,050 |
| Employee NI | £1,794.40 | £1,554.40 |
| Pension paid in | £0 | £3,000 |
- Employer saving: £450 a year
- Employee NI saving: £240 a year
- Plus the employee’s income tax saving on £3,000 at 20%: £600
Savings at different amounts (before the 2029 cap)
| Sacrificed | Employer NI saved | Employee NI saved at 8% | Employee NI saved at 2% (above £50,270) |
|---|---|---|---|
| £1,000 | £150 | £80 | £20 |
| £2,000 | £300 | £160 | £40 |
| £3,000 | £450 | £240 | £60 |
| £5,000 | £750 | £400 | £100 |
| £10,000 | £1,500 | £800 | £200 |
The employer saving is always 15%. The employee saving depends on pay: 8% in the main band and 2% above £50,270.
The same saving after the cap
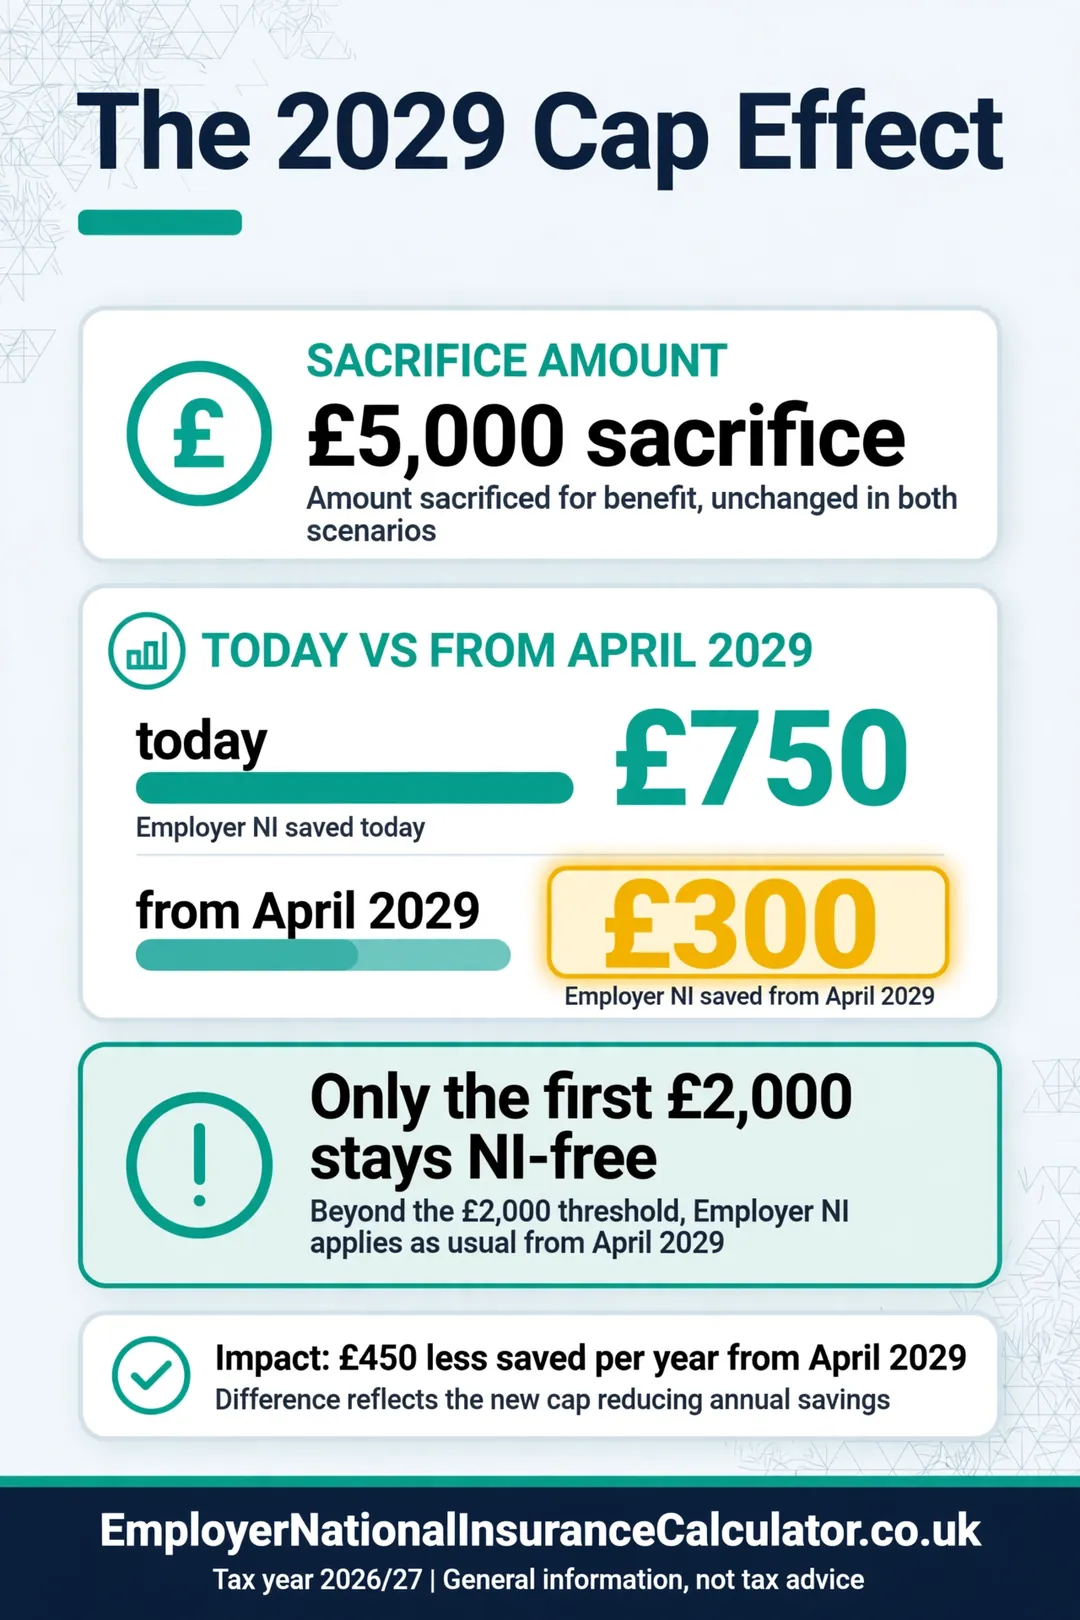
From April 2029, only £2,000 is NI-free. The table shows the employer saving before and after.
| Sacrificed | Saving now | Saving from April 2029 | Lost |
|---|---|---|---|
| £1,500 | £225 | £225 | £0 |
| £2,000 | £300 | £300 | £0 |
| £3,000 | £450 | £300 | £150 |
| £5,000 | £750 | £300 | £450 |
| £10,000 | £1,500 | £300 | £1,200 |
Passing the saving on
Many employers pass some or all of their saving into the pension. If the employer passes on its 15%, then £3,000 given up becomes £3,450 in the pension. Making this clear in the employee’s contract helps staff see the benefit.
Things to check before you start
- National Minimum Wage. Pay after the sacrifice must not drop below the minimum for hours worked.
- Other benefits. Mortgage applications, life cover and statutory pay may be worked out on the lower salary.
- Contract change. A written agreement must be in place before the pay is earned.
- Staff communication. Staff need to understand that their salary is lower, even though total reward is not.
- Payroll set-up. The sacrificed amount must be recorded as an employer contribution.
The 2029 cap
From 6 April 2029, only the first £2,000 of pension contributions made through salary sacrifice will be free of NI each year. If an employee sacrifices £5,000, then £3,000 is charged NI. With a 15% rate, the employer would save £300 instead of £750. See the full explanation in salary sacrifice pension cap 2029.
Who gains most
Employers with many staff benefit the most, because each person’s saving adds up. A company with 30 staff each sacrificing £2,000 saves £9,000 a year in employer NI. Higher-paid staff also gain, as they save 2% to 8% NI plus income tax.
Case study: a 12-person firm
A design agency has 12 staff who each sacrifice £2,400 a year into the pension.
| Item | Per person | For 12 staff |
|---|---|---|
| Employer NI saved today | £360 | £4,320 |
| Employee NI saved at 8% | £192 | £2,304 |
| Employer NI saved from April 2029 (first £2,000 only) | £300 | £3,600 |
From 2029 the agency loses £720 a year of savings. If it shares half of its saving with staff, it adds £180 per person to the pension today. Staff might notice and value this, which makes it a useful recruitment tool.
The employee’s view
An employee on £35,000 who sacrifices £3,000 loses £3,000 of gross pay. Their take-home falls by £3,000 less £600 income tax and £240 NI, which is £2,160. The pension rises by £3,000, or more if the employer shares its saving. For staff who want to save for retirement, this is more efficient than paying from net pay.
Common mistakes
- Not updating the contract before the sacrifice starts.
- Letting pay fall below the National Minimum Wage.
- Forgetting that statutory pay and some benefits may be based on lower pay.
- Not telling staff about the 2029 change. See the cap guide.
- Treating all employee pension payments as salary sacrifice. Only contracts that reduce pay count.
Compare with other ways to save
Salary sacrifice is one of several ways to reduce employer NI. Employer pension contributions outside sacrifice carry no NI either, see NI on pension contributions. Reliefs for younger staff are in the exemptions guide. Directors have their own options in director pension contributions.
Frequently asked questions
How much employer NI does salary sacrifice save?
15% of the sacrificed amount in 2026/27. On £3,000 it is £450.
Is employer NI paid on salary sacrifice pension contributions?
Not today. From April 2029, contributions above £2,000 a year will be charged.
Does salary sacrifice reduce the employee’s pay below the minimum wage?
It must not. The employer has to check that pay after the sacrifice is at or above the National Minimum Wage.
Can salary sacrifice be used for things other than pension?
Yes, for some benefits like cycle-to-work and electric cars. The pension rules are the ones capped in 2029.
Do I have to share the saving with staff?
No. It is a choice. Many employers pass on some or all to attract and keep staff.
Does salary sacrifice reduce State Pension?
Not directly, but a lower salary could reduce earnings records if pay falls below the Lower Earnings Limit.
Is salary sacrifice worth it for small employers?
It can be, for firms with several staff who save into a pension. Each person saves the firm 15% of the amount sacrificed.
Does salary sacrifice affect life cover?
Death-in-service cover is often a multiple of salary, so a lower salary may mean lower cover. Check the policy.
Can I mix salary sacrifice and a normal pension scheme?
Yes. Some staff use sacrifice for part and pay the rest from net pay.
Does salary sacrifice affect Employment Allowance?
Indirectly. It lowers your employer NI bill, so a smaller part of the £10,500 allowance is used.
Related guides
- £2,000 Salary Sacrifice Pension Cap From April 2029
- Do Employers Pay NI on Pension Contributions?
- Cost of Employing Someone UK 2026/27: Calculator
- Employer NI by Salary 2026/27: Table and Calculator
- Company Pension Contributions for Directors and NI
Official sources
- National Insurance rates and categories
- HMRC guidance on salary sacrifice
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
2 Comments
Comments are closed.