Is Employer NI Tax Deductible? Yes, With Examples
Yes. Employer National Insurance is an allowable business expense. A limited company deducts it from profits before corporation tax. A sole trader or partnership deducts it before income tax. The real cost after tax relief is therefore lower than the NI bill, though it is never free. This page shows the saving at each tax rate, with examples.
In this guide16 sections
How much tax it saves
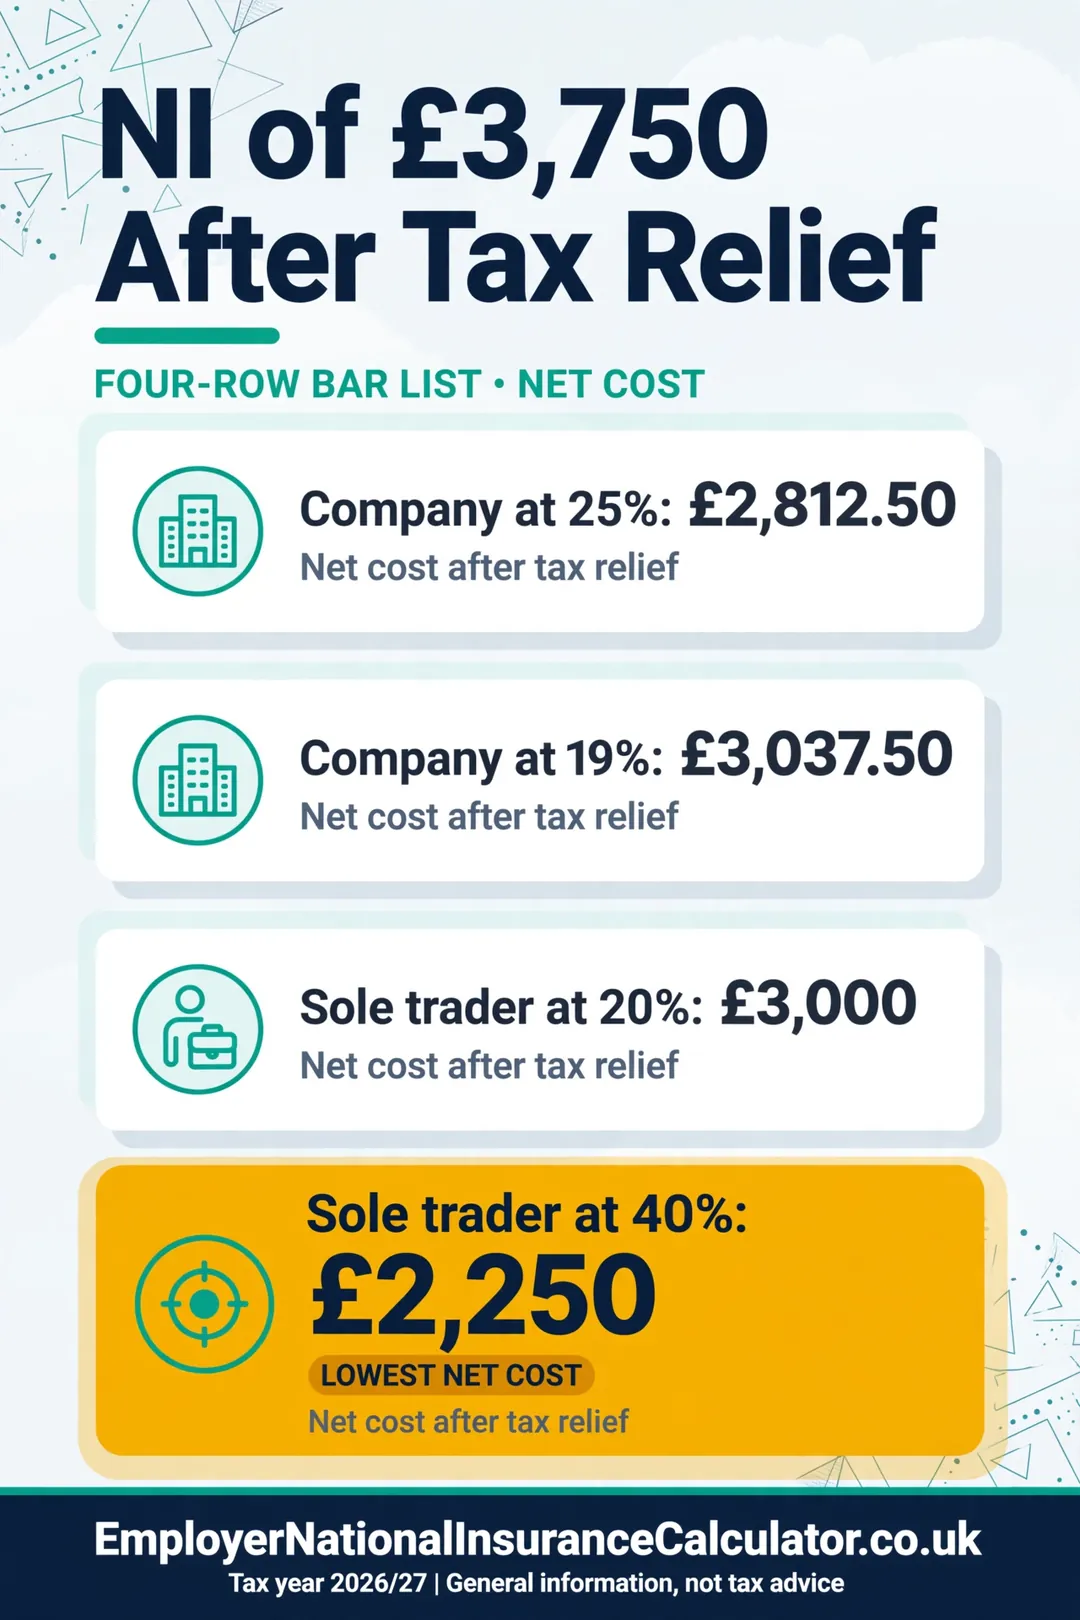
| Business type | Tax rate on profits | Employer NI of £3,750 costs, after tax relief |
|---|---|---|
| Company, profits over £250,000 | 25% | £2,812.50 |
| Company, profits £50,000 or less | 19% | £3,037.50 |
| Sole trader, basic rate | 20% (plus Class 4 NI) | £3,000 |
| Sole trader, higher rate | 40% (plus Class 4 NI) | £2,250 |
The figures show the cost after relief, using the rate of tax that applies at the margin. Companies with profits between £50,000 and £250,000 pay between 19% and 25%, with marginal relief. Check your own position. Sole traders also save Class 4 NI on the profit they no longer have, so the true saving is a little higher.
Example: a company with two staff
A company has two employees on £30,000 each. Employer NI is £7,500 before Employment Allowance, and £0 after the £10,500 allowance.
- If it can claim the allowance, there is no NI cost, and no deduction.
- If it cannot, the £7,500 is deductible. At 25%, it saves £1,875. The net cost is £5,625.
Remember to deduct only the NI that was actually paid. The allowance reduces what you pay and what you deduct.
What else is deductible
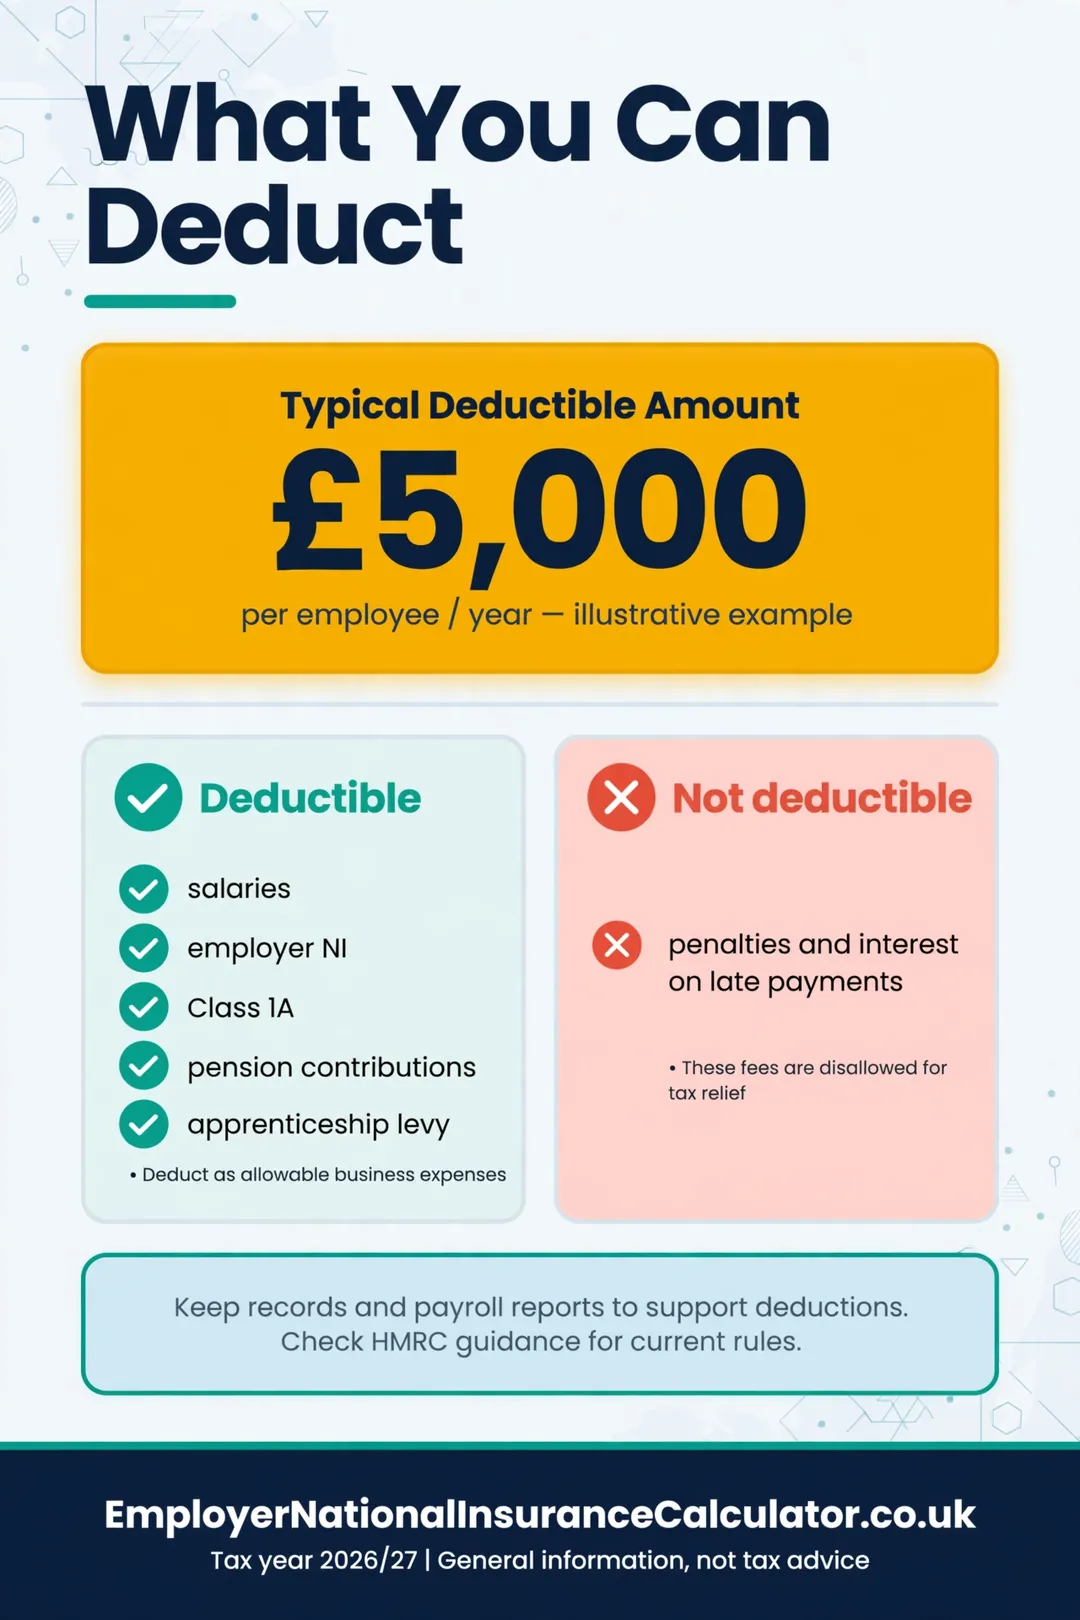
| Item | Deductible? |
|---|---|
| Salaries and wages | Yes |
| Employer NI | Yes |
| Employer pension contributions | Yes, if wholly and exclusively for the business |
| Class 1A NI | Yes |
| Apprenticeship levy | Yes |
| Employment Allowance | It reduces the cost, so less to deduct |
| Penalties and interest on late payments | No |
Where it goes in your accounts
Employer NI is shown with staff costs, either as part of wages or as “social security costs”. Your accountant will record it when it is due, not only when you pay it, if you use accrual accounting.
What about NI on owners?
A sole trader’s own Class 4 NI is not deductible. A company director’s salary and the employer NI on it are deductible. Dividends are not, as they come out of profits after tax. See the director salary guide.
| Item | Deductible for corporation tax? |
|---|---|
| Director salary of £12,570 | Yes |
| Employer NI on it (£1,135.50) | Yes |
| Dividends | No |
| Director’s own employee NI | Not a company cost |
When it might not be deductible
- Penalties and interest on late payments are not allowable.
- The “wholly and exclusively” test applies. Pay that is far above the market rate may be challenged.
- If the cost is of a capital nature, rules differ, though NI on salaries is not.
Case study: a company with £100,000 of profit
A company makes £100,000 before staff costs of £8,000 employer NI.
| Item | Without the NI cost | With the NI cost |
|---|---|---|
| Profit | £100,000 | £92,000 |
| Corporation tax at 25% | £25,000 | £23,000 |
| Profit after tax | £75,000 | £69,000 |
The NI of £8,000 reduces profit after tax by £6,000, since £2,000 is saved in tax. This is how relief works for any allowable cost. The profit used in the example is simplified. Check the correct rate for your profit level.
Hiring decisions with tax relief
When you plan a hire, the after-tax cost is what the business really bears.
| Hire at £30,000 | Cost before tax | Corporation tax saved at 25% | Net cost |
|---|---|---|---|
| Salary | £30,000 | £7,500 | £22,500 |
| Employer NI | £3,750 | £937.50 | £2,812.50 |
| Total | £33,750 | £8,437.50 | £25,312.50 |
This assumes the company is profitable and pays corporation tax at 25%. A loss-making company gets less benefit from the deduction.
Accounting for NI correctly
Record employer NI as a staff cost. If you use accrual accounting, record it for the period of the payroll, not when you pay it. Keep the payroll summary as evidence. Where Employment Allowance applies, record only the NI you actually owe. See the allowance guide.
Related costs and reliefs
If you are weighing hires, read the cost of employing someone to see the full cost and employer NI for small businesses to see how the allowance changes the bill. For benefits, see Class 1A, which is also deductible. The tax saving makes the true cost of NI lower, but it never makes it free.
When the tax relief arrives
Tax relief is not instant. It comes through your tax return or corporation tax payment.
| Business | When the relief is felt |
|---|---|
| Limited company | Lower corporation tax bill, normally due 9 months and 1 day after the year end |
| Sole trader | Lower income tax bill at the next self-assessment payment dates |
| Partnership | Lower tax for each partner, through their returns |
So a hire made today costs the full NI now and gets relief later. Plan cash flow on the gross cost, and treat the relief as a later benefit.
Examples across structures
| NI of £5,000 paid | Tax rate | Tax saved | Net cost |
|---|---|---|---|
| Company, 19% | 19% | £950 | £4,050 |
| Company, 25% | 25% | £1,250 | £3,750 |
| Sole trader, basic rate | 20% | £1,000 | £4,000 |
| Sole trader, higher rate | 40% | £2,000 | £3,000 |
Loss-making businesses
A business making a loss gets no tax saving this year. The loss can often be carried forward or back, depending on the structure, and the NI cost is then part of that loss. Ask your accountant how losses interact with your tax position.
Frequently asked questions
Is employer NI tax deductible for a limited company?
Yes. It is an allowable cost against profits for corporation tax.
Is employer NI deductible for a sole trader?
Yes, if you employ staff. It is deducted from your profits for income tax.
Is employer NI deductible if it is paid late?
The NI is, but any penalties and interest are not.
Is Employment Allowance taxable?
It reduces your NI cost. You only deduct the NI after the allowance.
Do I deduct my own NI as a sole trader?
No. Your own Class 4 contributions are not allowable.
Should I ask an accountant?
Yes. The savings depend on your profits and structure.
Do I deduct employer NI in the year it is earned or paid?
Usually in the period the pay relates to if you use accrual accounting. Ask your accountant about your method.
Is the apprenticeship levy deductible?
Generally yes, as a staff cost. Check with your accountant.
Does tax relief make employer NI free?
No. It reduces the cost by your tax rate. A 25% rate cuts the cost by a quarter.
Is Class 1A also deductible?
Yes. It is an employment cost, treated in the same way as employer NI on pay.
Related guides
- Employer NI for Small Businesses: Hiring Cost and Cash Flow
- Cost of Employing Someone UK 2026/27: Calculator
- Director Salary 2026/27: £5,000, £6,708 or £12,570?
- Employment Allowance 2026/27: £10,500 Off Employer NI
- Class 1A National Insurance 2026/27: Rate and Deadlines
Official sources
- National Insurance rates and categories
- HMRC guidance on allowable business expenses
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.