Employment Allowance Eligibility: Who Can Claim?
Most employers who pay Class 1 employer NI can claim Employment Allowance in 2026/27. The main exceptions are a company where the only paid employee is also the director, employers of domestic staff, and public bodies. Connected companies share a single allowance. This page lets you check your position in a few minutes, with examples for the grey areas.
In this guide14 sections
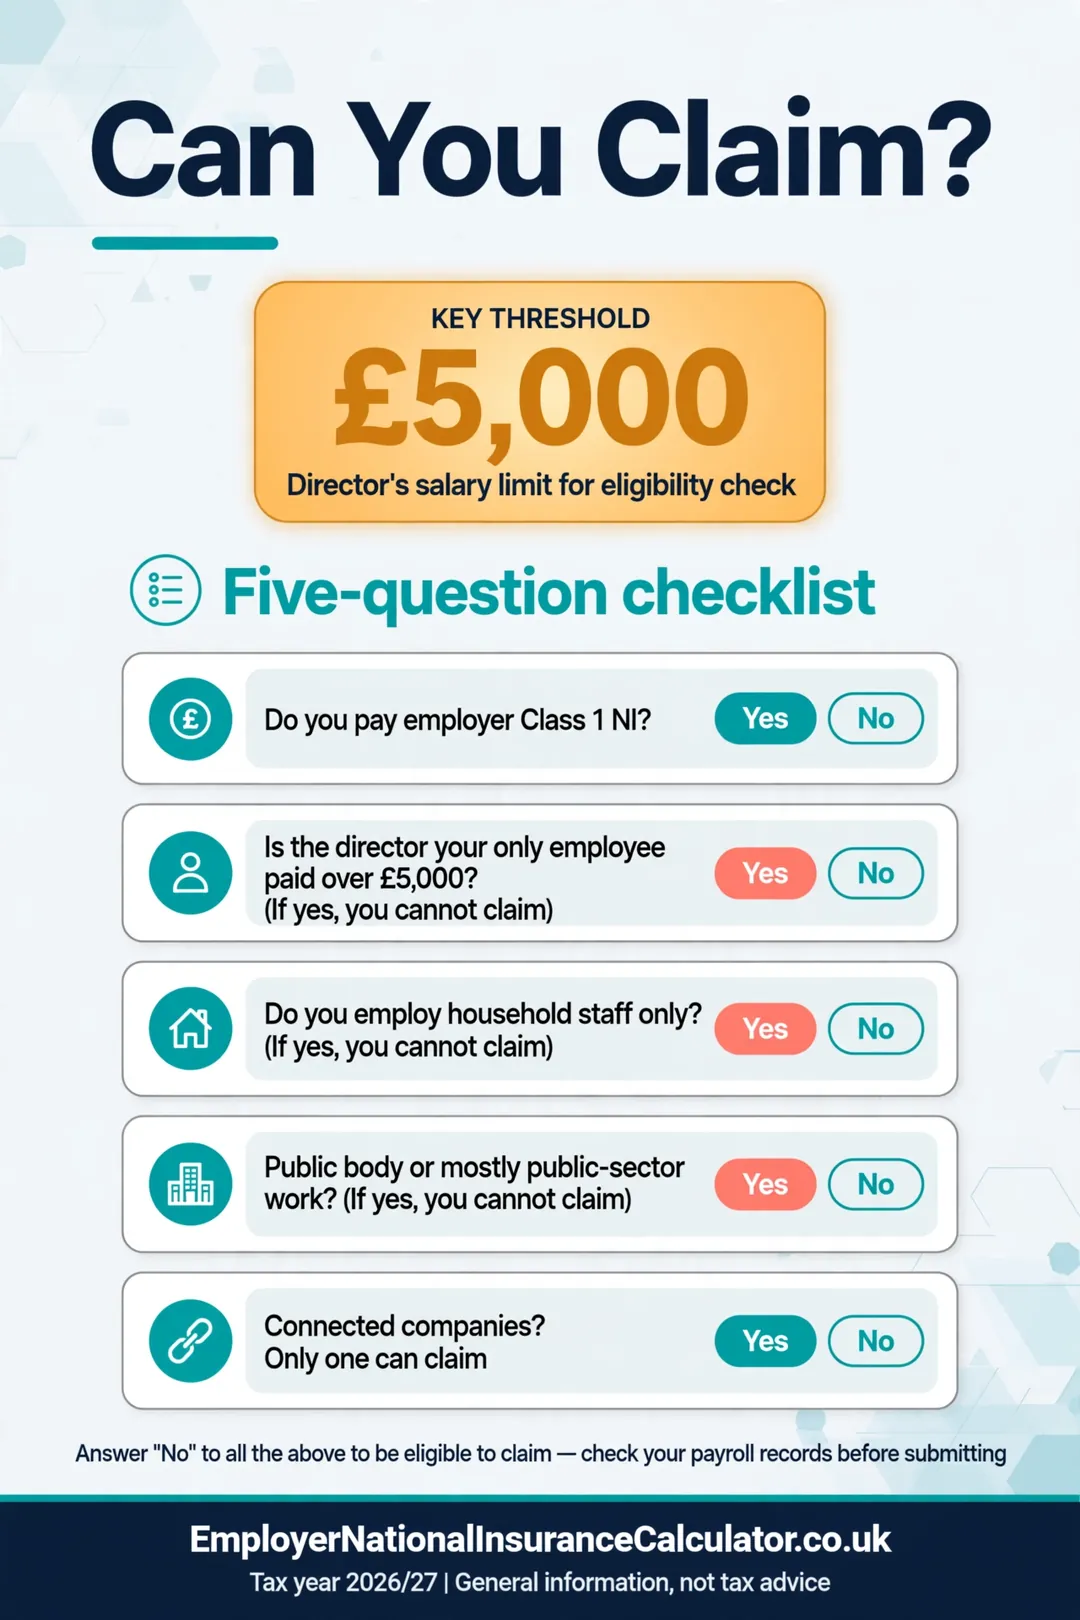
Quick eligibility check
Answer these in order.
- Do you pay employer Class 1 NI? If your bill is nil, there is nothing to reduce.
- Are you a company with one employee paid above the Secondary Threshold, and is that person a director? If yes, you cannot claim.
- Do you employ someone for personal or household reasons only? If yes, you cannot claim for that work.
- Are you a public body, or do you do mostly public-sector work? If yes, you usually cannot claim. Charities are not excluded.
- Are you connected with other companies? If yes, only one of you can claim.
If none of the exclusions apply, you can claim.
The sole director rule
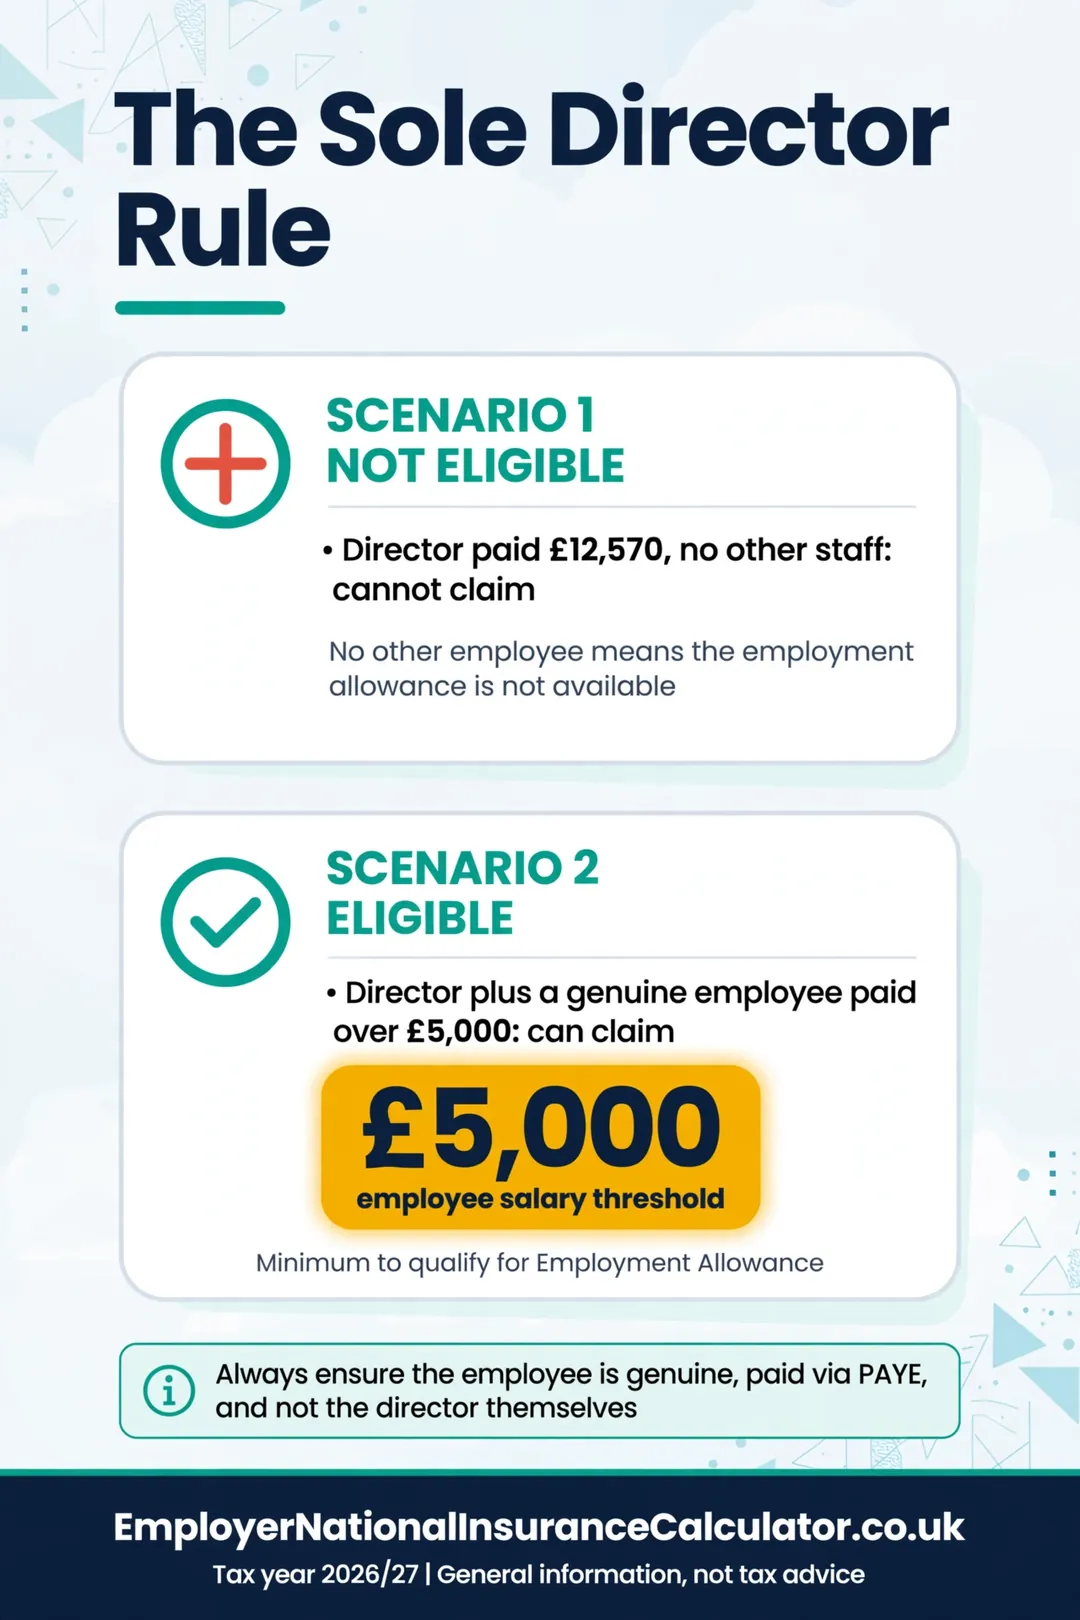
A company cannot claim if the director is the only employee paid above the Secondary Threshold of £5,000. It is easy to meet the threshold by accident, so look at the numbers.
| Situation | Can claim? |
|---|---|
| Director paid £12,570, no other staff | No |
| Director paid £12,570 plus a second employee paid £8,000 | Yes, because two people are paid above £5,000 |
| Two directors, both paid £12,570 | Yes |
| Director paid £12,570 plus an assistant paid £4,000 | No, because the assistant is below £5,000 |
| Director paid £12,570 plus an assistant paid £6,000 | Yes |
The second person must be a genuine employee doing real work for a fair wage. HMRC looks closely at arrangements set up only to get the allowance.
What the allowance is worth in these cases
| Company | Employer NI before | Employment Allowance | Employer NI to pay |
|---|---|---|---|
| Sole director on £12,570 | £1,135.50 | £0, not eligible | £1,135.50 |
| Director on £12,570 plus an employee on £8,000 | £1,585.50 | £1,585.50 | £0 |
Do not hire someone to qualify for the allowance unless you need them. The rule is meant for genuine employers, and HMRC can ask for repayment.
Connected companies
Companies are connected if one controls the other, or the same person or people control both. A group can only make one claim. Many groups put the whole £10,500 on the company with the biggest NI bill. A sole trader with several businesses counts as a single employer too.
| Situation | Connected? | Result |
|---|---|---|
| Two companies owned by the same person | Yes | One allowance in total |
| A sole trader with two shops | Same employer | One allowance in total |
| Two unrelated companies sharing an office | No | Each can claim |
| A parent company and its subsidiaries | Yes | One allowance in total |
How to allocate the allowance in a group
Pick the company with the largest NI bill, and set the Employment Allowance indicator there. Other companies in the group must not claim. Record the decision in writing. If circumstances change, you can move the claim, with care. Ask an accountant first.
Household employers
If you employ a nanny, carer or cleaner for personal reasons, you cannot claim for them. If you run a business and also employ domestic staff, you can still claim for the business employees. The allowance only covers the business payroll. See employer NI for small businesses.
Public sector limits
Public authorities cannot claim. Neither can businesses that do more than half of their work for public bodies. Charities and voluntary groups may claim. Check how much of your income comes from public contracts.
Subsidy rules
Employment Allowance counts as public financial support under the UK subsidy control rules. Most small employers never come close to any limit, but if you receive other support, ask your accountant.
Examples of businesses that can and cannot claim
| Business | Can claim? | Why |
|---|---|---|
| Café with 4 staff | Yes | Pays employer NI on several employees |
| Limited company, one director, no staff | No | Only the director is paid |
| Limited company, director plus part-time employee on £9,000 | Yes | The employee is paid above £5,000 |
| Hospital trust | No | Public body |
| Charity shop with 3 paid staff | Yes | Charities can claim |
| Family with a nanny | No | Domestic employment |
| Sole trader with one employee on £20,000 | Yes | Employer NI is due and no exclusion applies |
| Builder with all staff on a 0% category (all under 21) | Yes, but nothing to claim | The employer NI bill is nil |
What happens if you claim wrongly
HMRC can ask you to pay back the allowance with interest, and may charge a penalty. If you find an error, correct it through payroll and tell HMRC as soon as you can.
What to do if you are unsure
Write down who is paid, how much, and what the person does. Keep it with your payroll records. If it is unclear, ask HMRC or your accountant before you claim. A wrong claim leads to repayment. If you qualify, follow the claim steps.
Keep evidence
For each year you claim, keep:
- A list of staff and what each was paid
- Proof that at least one employee other than the director was paid above £5,000, if you are a company with a director
- Group structure notes, if you are connected with other companies
- A copy of the claim you sent
Related reading
See the Employment Allowance guide and director salary options for the small-company angle.
Frequently asked questions
Can a sole director claim Employment Allowance?
Not if the director is the only employee paid above £5,000. If someone else on the payroll earns more than £5,000, the company can claim.
Can I claim if my spouse is the only other employee?
Yes, if they are a genuine employee paid above the Secondary Threshold for real work.
Can sole traders claim it?
Yes, if they employ staff and pay employer NI. A sole trader with no employees cannot.
Can a charity claim Employment Allowance?
Yes, in most cases, as charities are not excluded.
Can I claim for more than one company?
Only one company in a connected group can claim.
Can I claim if I employ a nanny?
Not for the nanny. You can claim for your business employees if you run a business as well.
What if I don’t know whether I’m eligible?
Ask HMRC or your accountant before you tick the box. A wrong claim leads to repayment.
Can two directors of the same company claim?
Yes, if both are paid above £5,000, because then more than one person is paid above the threshold.
Do the connected company rules apply to sole traders?
A sole trader counts as one employer, even with several businesses, and has a single allowance.
Can I claim if all my staff are apprentices or under 21?
You can claim, but you can only reduce a bill that exists. If employer NI is nil, there is nothing to take off.
Does a recently started company qualify?
Yes. There is no minimum trading period. You claim from the first payroll run if the other conditions are met.
Related guides
- Employment Allowance 2026/27: £10,500 Off Employer NI
- How to Claim Employment Allowance (Step by Step)
- Director Salary 2026/27: £5,000, £6,708 or £12,570?
- Employer NI for Small Businesses: Hiring Cost and Cash Flow
- Can You Claim Back Employer NI? Yes, in These Cases
Official sources
- Employment Allowance
- HMRC guidance on Employment Allowance eligibility
This page is independent information, not tax advice, and has no link with HMRC. Figures were checked on 20 October 2026 for the 2026/27 tax year. Always confirm the final figures with HMRC or your payroll provider.
One Comment
Comments are closed.